F-4/A: Registration of securities, foreign private issuers, business combinations
Published on May 22, 2025
As filed with the Securities and Exchange Commission on May 22, 2025.
Registration Statement No. 333-282863
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
–––––––––––––––––––––––––––
Amendment No. 3 to
FORM F-4
REGISTRATION STATEMENT
UNDER
THE SECURITIES ACT OF 1933
–––––––––––––––––––––––––––
PLUM III MERGER CORP.
(Exact name of Registrant as Specified in its Charter)
N/A
(Translation of registrant’s name into English)
–––––––––––––––––––––––––––
|
British Columbia |
6770 |
Not Applicable |
||
|
(State or other jurisdiction of |
(Primary Standard Industrial |
(IRS Employer |
2021 Fillmore St., #2089
San Francisco, California 94115
(929) 529-7125
(Address, including zip code, and telephone number, including area code, of registrant’s principal executive offices)
–––––––––––––––––––––––––––
CT Corporation System
28 Liberty Street
New York, New York 10005
(212) 894-8940
(Name, address, including zip code, and telephone number, including area code, of agent for service)
–––––––––––––––––––––––––––
With copies to:
|
Bill Nelson |
Richard Aftanas |
Francesco Gucciardo |
Desmond Balakrishnan |
–––––––––––––––––––––––––––
Approximate date of commencement of proposed sale of the securities to the public: As soon as practicable after the effectiveness of this registration statement and upon completion of the business combination described in the enclosed proxy statement/prospectus.
If this Form is filed to register additional securities for an offering pursuant to Rule 462(b) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If this Form is a post-effective amendment filed pursuant to Rule 462(d) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If applicable, place an X in the box to designate the appropriate rule provision relied upon in conducting this transaction:
Exchange Act Rule 13e-4(i) (Cross-Border Issuer Tender Offer) ☐
Exchange Act Rule 14d-1(d) (Cross-Border Third Party Tender Offer) ☐
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933.
Emerging growth company ☒
If an emerging growth company that prepares its financial statements in accordance with U.S. GAAP, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards† provided pursuant to Section 7(a)(2)(B) of the Securities Act. ☐
____________
† The term “new or revised financial accounting standard” refers to any update issued by the Financial Accounting Standards Board to its Accounting Standards Codification after April 5, 2012.
The registrant hereby amends this registration statement on such date or dates as may be necessary to delay its effective date until the registrant shall file a further amendment which specifically states that this registration statement shall thereafter become effective in accordance with Section 8(a) of the Securities Act, or until this registration statement shall become effective on such date as the Securities and Exchange Commission, acting pursuant to said Section 8(a), may determine.
TABLE OF ADDITIONAL REGISTRANTS
|
Name of Additional Registrant(1) |
Jurisdiction of Incorporation or |
IRS Employer ID Number |
||
|
Tactical Resources Corp. |
British Columbia |
Not Applicable |
____________
(1) The address, including zip code, and telephone number, including area code, of each additional registrant’s principal executive offices are Suite 1500 – 1055 West Georgia Street, Vancouver, British Columbia, Canada V6E 4N7, phone number (778) 588-5483
The information contained in this document is subject to completion or amendment. A registration statement relating to these securities has been filed with the United States Securities and Exchange Commission. These securities may not be sold nor may offers to buy be accepted prior to the time the registration statement becomes effective. This document is not an offer to sell these securities and it is not soliciting an offer to buy these securities, nor shall there be any sale of these securities, in any jurisdiction in which such offer, solicitation or sale is not permitted or would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction.
PRELIMINARY — SUBJECT TO COMPLETION, DATED MAY 22, 2025
PROXY STATEMENT FOR EXTRAORDINARY GENERAL MEETING OF SHAREHOLDERS OF
PLUM ACQUISITION CORP. III
PROSPECTUS FOR
58,847,367 CLASS A COMMON SHARES,
12,059,166 WARRANTS AND 12,059,166 CLASS A COMMON SHARES
ISSUABLE UPON EXERCISE OF WARRANTS OF PLUM III MERGER CORP.
PROPOSED BUSINESS COMBINATION — YOUR PARTICIPATION IS VERY IMPORTANT
Dear Shareholders of Plum Acquisition Corp. III:
You are cordially invited to attend the extraordinary general meeting (the “Plum Shareholders’ Meeting”) of shareholders of Plum Acquisition Corp. III (“Plum” and such shareholders, the “Plum Shareholders”), which will be held at 10:00 a.m., Eastern Time, on [•], 2025, virtually pursuant to the procedures described in the accompanying proxy statement/prospectus for the purposes of Cayman Islands law and Plum’s Amended and Restated Memorandum and Articles of Association (the “Plum Articles”).
On August 22, 2024, Plum, Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum (“Amalco”), Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia (“PubCo”), and Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia (“TRC”), entered into a Business Combination Agreement (as may be amended, supplemented or otherwise modified from time to time, the “Business Combination Agreement,” and the transactions contemplated thereby, collectively, the “Business Combination”), pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement, and the plan of arrangement attached hereto as Annex B (the “Plan of Arrangement”) (i) Plum shall transfer by way of continuation from the Cayman Islands to the Province of British Columbia in accordance with the Cayman Islands Companies Act (As Revised) (the “Companies Act”) and continue as a corporation under the Laws of the Province of British Columbia in accordance with the applicable provisions of the Business Corporations Act (British Columbia) (the “BCBCA”) (the “Domestication”), (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation.
Pursuant to the Plum Amalgamation, which will take place after the Domestication and on the date on which the closing of the Business Combination will occur (the “Closing” and such date the “Closing Date”):
• each Plum Unit shall be automatically divided, and the holder thereof shall be deemed to hold one Plum Class A Share, par value $0.0001 per share (a “Plum Class A Share”) and one-third of one Plum Warrant in accordance with the terms of the applicable Plum Unit;
• each Plum Class A Share and Plum Class B ordinary share, par value $0.0001 per share (a “Plum Class B Share” and together with the Plum Class A Shares, the “Plum Common Shares”), will be exchanged on a one-for-one basis, for a common share in the authorized share capital of PubCo (a “PubCo Common Share”); and
• each Plum Warrant shall automatically be converted into a warrant (each, a “PubCo Assumed Plum Warrant”) to purchase a number of PubCo Common Shares determined in accordance with the terms of such Plum Warrant.
On the Closing Date, pursuant to the TRC Amalgamation, among other things:
• each TRC Common Share (other than any Cancelled TRC Shares or Dissenting Shares) shall automatically be exchanged for the right to receive a number of PubCo Common Shares equal to the TRC Exchange Ratio (the aggregate of all such PubCo Common Shares, the “Arrangement Consideration Shares”). Any Arrangement Consideration Shares exchanged for TRC Common Shares which were subject to any vesting or forfeiture terms shall continue to be governed by such terms from and after the TRC Amalgamation Effective Time;
• each of the Dissenting Shares shall be cancelled and shall thereafter represent only the right to receive the applicable payments set forth in the Plan of Arrangement;
• each TRC Option shall be assumed by PubCo and converted into an option to purchase PubCo Common Shares (each, a “Converted TRC Option”), subject to the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such Converted TRC Option shall
be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
• each TRC RSU shall be assumed by PubCo and converted into a restricted stock unit in respect of PubCo Common Shares (each, a “Converted TRC RSU”), subject to the same terms and conditions as were previously applicable thereto, except that such Converted TRC RSU shall be in respect of a number of PubCo Common Shares equal to the product of (A) the number of shares previously subject to such TRC RSU and (B) the TRC Exchange Ratio;
• each TRC Warrant shall automatically be converted into a warrant to purchase PubCo Common Shares (each, a “PubCo Assumed TRC Warrant”), and such PubCo Assumed TRC Warrant shall continue to be governed by the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such PubCo Assumed TRC Warrant shall be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
• the TRC Convertible Debenture shall survive the TRC Amalgamation in accordance with the terms thereof (subject to the conversion rights of the holder set forth therein); and
• each Amalco Share shall automatically be exchanged for one validly-issued, fully paid and nonassessable common share of TRC.
At the Plum Shareholders’ Meeting, Plum Shareholders will be asked to consider and vote upon proposals to approve, (i) by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and the Companies Act and the domestication of Plum as a British Columbia corporation in accordance with the applicable provisions of the BCBCA, including the adoption of the Domestication Articles (the “Domestication Proposal” or “Proposal No. 1”); and (ii) by Ordinary Resolution, the Business Combination Agreement, a copy of which is attached to the accompanying proxy statement/prospectus as Annex A, and approve the transactions contemplated thereby, including the Business Combination (the “Business Combination Proposal” or “Proposal No. 2”).
In connection with the submission of the Business Combination to a shareholder vote, holders of Plum Common Shares, including Plum’s sponsor, Mercury Capital LLC (“Sponsor”), Alpha Partners Technology Merger Sponsor LLC (“Former Sponsor”), and certain other Plum Shareholders set forth therein (together with Sponsor and Former Sponsor, the “Sponsor Parties”) have agreed to vote any Plum Class A Shares (except for any Plum Class A Shares purchased as described below under “The Business Combination — Potential Purchases of Public Shares”) and Plum Class B Shares owned by them in favor of the Business Combination. The consummation of the Business Combination is not subject to the approval of a majority of unaffiliated Plum Public Shareholders. Since the Sponsor Parties own approximately 87.4% of the Plum Shares entitled to vote at the Plum Shareholders’ Meeting, the Sponsor Parties have sufficient votes to approve all of the Proposals without the vote of any of the Plum Public Shareholders.
In addition to the Domestication Proposal and the Business Combination Proposal, Plum Shareholders are being asked to consider and vote upon:
• proposals to approve on a non-binding advisory basis, by Ordinary Resolution the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately in accordance with U.S. Securities and Exchange Commission guidance (the “Advisory Organizational Documents Proposals” or “Proposal No. 3”). The full text of the PubCo Closing Articles are attached to the accompanying proxy statement/prospectus as Annex E . Proposal No. 3 is separated into sub-proposals submitted to Plum Shareholders to approve on a non-binding advisory basis, by Ordinary Resolution, those governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights as described in the following paragraphs (a)–(d):
(a) the proposed PubCo Closing Articles would change the authorized share capital from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal par value of $0.0001 each, to an unlimited number of PubCo Common Shares (the “Authorized Capital Proposal” or “Proposal No. 3A”);
(b) the proposed PubCo Closing Articles would reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting (the “Quorum Proposal” or “Proposal No. 3B”);
(c) the proposed PubCo Closing Articles would change the name of the company from “Plum III Merger Corp.” to “Tactical Resources Corporation” (the “Name Change Proposal” or “Proposal No. 3C”); and
(d) the proposed PubCo Closing Articles would not include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters (the “Other Matters Proposal” or “Proposal No. 3D” and, together with the Authorized Capital Proposal, the Quorum Proposal and the Name Change Proposal, the “Sub-Proposals”);
• Incentive Plan Proposal — To approve, by Ordinary Resolution, for the purposes of complying with the rules of the Nasdaq Stock Market, the issuance of PubCo Common Shares pursuant to the PubCo Omnibus Equity Incentive Plan (the “Incentive Plan Proposal” or “Proposal No. 4”). A copy of the Incentive Plan is attached to this proxy statement/prospectus as Annex K;
• Adjournment Proposal — if put to Plum Shareholders for a vote, a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the foregoing proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals (the “Adjournment Proposal” or “Proposal No. 5” and, together with the Domestication Proposal, the Business Combination Proposal, the Incentive Plan Proposal and the Advisory Organizational Documents Proposals, the “Proposals”). If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Each of the Proposals is more fully described in the accompanying proxy statement/prospectus, which each Plum Shareholder is encouraged to read carefully.
The approval of the Domestication Proposal requires a special resolution under Cayman Islands Companies Law (a “Special Resolution”), being the affirmative vote of at least a two-thirds (66 2/3%) majority of the votes cast by the holders of the Plum Common Shares present in person or represented by proxy at the Extraordinary General Meeting and entitled to vote on such matter. The approval of each of the Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and the Adjournment Proposal requires an ordinary resolution under the Cayman Islands Company Law (an “Ordinary Resolution”), being the affirmative vote of at least a majority of the votes cast by the holders of the Plum Common Shares present in person or represented by proxy at the Extraordinary General Meeting and entitled to vote on such matter.
In connection with the Business Combination, we expect to enter into one or more subscription agreements with certain PIPE Investors to purchase PubCo Common Shares in a separate private placement transaction as described below under “The Business Combination — PIPE Investment.” The final terms of the PIPE Investment have yet to be determined and are subject to negotiation between us, TRC, PubCo and the PIPE Investors. This proxy statement/prospectus does not constitute an offer to sell nor is soliciting an offer to buy any securities in connection with the PIPE Investment.
The Plum Class A Shares and Plum Warrants, which are exercisable for Plum Class A Shares under certain circumstances, are currently qualified on the OTC Markets Group Pink (the “OTC Pink”) under the symbols “PLMJF” and “PLMWF,” respectively. In addition, certain of the Plum Class A Shares and Plum Public Warrants currently trade as Plum Units, consisting of one Plum Class A Share and one-third of one Plum Public Warrant, and are qualified on the OTC Pink under the symbol “PLMUF”. At the Plum Amalgamation Effective Time, the Plum Units will automatically separate into the component PubCo Common Shares and PubCo Public Warrants. PubCo
has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the Nasdaq Capital Market (“NASDAQ”). Listing is subject to the approval of the NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing, the PubCo Common Shares and PubCo Public Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively. Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX Venture Exchange (the “TSX-V”), and TRC will apply to have TRC cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
Sponsor Compensation
Pursuant to the SEC’s rules governing special purpose acquisition companies (“SPACs”), securities of Plum and promissory notes issued by Plum to the Sponsor, the Former Sponsor, any entity and/or person primarily responsible for organizing, directing or managing the business and affairs of Plum, such as the Sponsor, may be considered “compensation” awarded to or earned by the Sponsor. The table set forth below summarizes the existing interests in Plum private placement securities and the anticipated interests of Former Sponsor, Sponsor, Plum management, and the lender under a subscription agreement in PubCo as of Closing along with the value of such interests based on (i) in the case of Sponsor’s and Plum management’s interests, the closing price of the Plum Public Warrants and Plum Class A Shares as of [•], 2025, which would be lost if an Initial Business Combination is not completed by Plum by the Deadline Date, and (ii) the transaction value:
|
Name of Holder |
Type of |
Total |
Number of |
Number of |
Value of |
Number of |
Number of |
Value of |
|||||||||
|
Mercury Capital, LLC |
Sponsor |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Alpha Partners Technology Merger Sponsor, LLC |
Former Sponsor |
$ |
6,675,000 |
665,000 |
221,667 |
1,128,992 |
376,331 |
||||||||||
|
Palmeira Investment |
Lender to Sponsor |
$ |
750,000 |
0 |
0 |
637,500 |
0 |
||||||||||
|
Kanishka Roy |
CEO & |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Steven Handwerker |
CFO |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Hume Kyle |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Alan Black |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
David Sable |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
The Sponsor will not receive any direct compensation for services rendered in connection with the Business Combination. Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting. Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•]. Since all Founder Units have been issued, this compensation will not result in a material dilution to the equity interests of non-redeeming shareholders upon consummation of the Business Combination.
Plum has borrowed certain amounts from the Sponsor pursuant to (i) a promissory note (the “Working Capital Note”) which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants (the “Sponsor Warrants for Working Capital Note”) at a price of $1.50 per warrant, to be issued at Closing, and (ii) a promissory note, as amended, which provides
for up to $100,000 in working capital loans, which shall be repaid in cash on the earlier of (i) consummation of the Plum’s initial merger, share exchange, asset acquisition, share purchase, recapitalization, reorganization or similar business combination with one or more businesses or entities, (ii) the date of the liquidation of Plum or (iii) 270 calendar days. The warrants that may be issuable pursuant to the promissory note to the Sponsor at Closing as reimbursement, if exercised, would result in the issuance of up to 1,466,667 additional Plum Class A Ordinary Shares upon Closing. See “Notes to Unaudited Pro Forma Condensed Consolidated Financial Information” for further information on the dilution. Assuming that all Plum Public Warrants and Plum Private Placement Warrants are exercised, this compensation will not result in a material dilution of the equity interests of non-redeeming Plum Public Shareholders.
See “The Business Combination — Interests of Certain Persons in the Business Combination” for a description of all compensation to be paid to the Sponsor, it affiliates and promoters in connection with the Business Combination.
The Plum Board has unanimously determined that the Business Combination and the transactions contemplated by the Business Combination Agreement are advisable and in the best interests of Plum and its shareholders. For more information about the Plum Board’s decision-making process, see the subsection entitled “The Business Combination — Plum Board’s Reasons for Approving the Business Combination.” In considering the unanimous recommendation of the Plum Board to vote in favor of the Business Combination, Plum Public Shareholders should be aware that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, those of other Plum Public Shareholders generally. Plum’s directors were aware of and considered these interests, among other matters, in evaluating the Business Combination, and in recommending to Plum Shareholders that they approve the Business Combination. Plum Shareholders should take these interests into account in deciding whether to approve the Business Combination. In addition, aside from their interests as shareholders, members of TRC management have interests in the Business Combination that are different from, or in addition to, those of other TRC shareholders generally. TRC’s directors were aware of and considered these interests, among other matters, in evaluating the Business Combination. See “The Business Combination — Interests of Certain Persons in the Business Combination” for a description of such potential conflicts of interest.
Plum is providing the accompanying proxy statement/prospectus and accompanying proxy card to Plum Shareholders in connection with the solicitation of proxies to be voted at the Plum Shareholders’ Meeting and at any adjournments or postponements of the Plum Shareholders’ Meeting. Information about the Plum Shareholders’ Meeting, the Business Combination and other related business to be considered by Plum Shareholders at the Plum Shareholders’ Meeting is included in the accompanying proxy statement/prospectus. Whether or not you plan to attend the Plum Shareholders’ Meeting, all Plum Shareholders are urged to read carefully and in its entirety the accompanying proxy statement/prospectus, including the annexes and the accompanying financial statements of TRC and Plum. In particular, you are urged to carefully read the section entitled “Risk Factors” beginning on page 70 of the accompanying proxy statement/prospectus.
The Board of Directors of Plum (the “Plum Board”) has unanimously approved the Business Combination Agreement and the transactions contemplated therein, and unanimously recommends that Plum Shareholders vote “FOR” the adoption of the Business Combination Agreement and approval of the transactions contemplated thereby, including the Business Combination, and “FOR” all other Proposals presented to Plum Shareholders in the accompanying proxy statement/prospectus. When you consider the Plum Board’s recommendation of the Proposals, you should keep in mind that certain members of Plum management have interests in the Business Combination that may conflict with your interests as a shareholder. Please see the subsection entitled “The Business Combination — Interests of Certain Persons in the Business Combination” for additional information.
Your vote is very important, regardless of the number of Plum Common Shares you own. To ensure your representation at the Plum Shareholders’ Meeting, please complete, sign, date and return the enclosed proxy card in the postage-paid envelope provided or submit your proxy by telephone or over the internet by following the instructions on your proxy card. If you hold your Plum Common Shares in “street name,” which means your shares are held of record by a broker, bank or other nominee, you should follow the instructions provided by your broker, bank or nominee to ensure that votes related to the shares you beneficially own are properly counted. In accordance with the Business Corporations Act (British Columbia), please submit your
proxy promptly, whether or not you expect to attend the Plum Shareholders’ Meeting, but in any event, no later than [•], 2025, at 11:59 p.m., Eastern Time, which is two business days prior to the Plum Shareholders’ Meeting.
On behalf of the Plum Board, I would like to thank you for your support of Plum Acquisition Corp. III and look forward to a successful completion of the Business Combination.
Sincerely,
|
/s/ Kanishka Roy |
||
|
Kanishka Roy |
NEITHER THE U.S. SECURITIES AND EXCHANGE COMMISSION NOR ANY STATE SECURITIES REGULATORY AGENCY HAS APPROVED OR DISAPPROVED THE TRANSACTIONS DESCRIBED IN THE ACCOMPANYING PROXY STATEMENT/PROSPECTUS, PASSED UPON THE MERITS OR FAIRNESS OF THE BUSINESS COMBINATION OR RELATED TRANSACTIONS OR PASSED UPON THE ADEQUACY OR ACCURACY OF THE DISCLOSURE IN THE ACCOMPANYING PROXY STATEMENT/PROSPECTUS. ANY REPRESENTATION TO THE CONTRARY CONSTITUTES A CRIMINAL OFFENSE.
Investing in Plum and PubCo securities involves a high degree of risk. Before making an investment decision, please read the information under the section entitled “Risk Factors” elsewhere in the accompanying proxy statement/prospectus and under similar headings or in any amendment or supplement to the accompanying proxy statement/prospectus.
PubCo is a “foreign private issuer” under the Exchange Act and therefore is exempt from certain rules under the Exchange Act, including the proxy rules, which impose certain disclosure and procedural requirements for proxy solicitations for U.S. and other issuers. Accordingly, after the Business Combination, PubCo Shareholders may receive less or different information about PubCo than they would receive about a U.S. domestic public company. See “Risk Factors — Risks Related to Ownership of PubCo’s Securities — As a “foreign private issuer” under the rules and regulations of the SEC, PubCo will be, permitted to, and may, file less or different information with the SEC than a company incorporated in the United States or otherwise not filing as a “foreign private issuer,” and may follow certain home country corporate governance practices in lieu of certain NASDAQ requirements applicable to U.S. issuers.”
The accompanying proxy statement/prospectus is dated [•], 2025, and is expected to be first mailed or otherwise delivered to Plum Shareholders on or about [•], 2025.
ADDITIONAL INFORMATION
No person is authorized to give any information or to make any representation with respect to the matters that this proxy statement/prospectus describes other than those contained in this proxy statement/prospectus, and, if given or made, the information or representation must not be relied upon as having been authorized by PubCo, Plum or TRC. This proxy statement/prospectus does not constitute an offer to sell or a solicitation of an offer to buy securities or a solicitation of a proxy in any jurisdiction where, or to any person to whom, it is unlawful to make such an offer or a solicitation. Neither the delivery of this proxy statement/prospectus nor any distribution of securities made under this proxy statement/prospectus will, under any circumstances, create an implication that there has been no change in the affairs of PubCo, Plum or TRC since the date of this proxy statement/prospectus or that any information contained herein is correct as of any time subsequent to such date.
PLUM ACQUISITION CORP. III
2021 Fillmore St., #2089, San Francisco, California 94115
NOTICE OF EXTRAORDINARY GENERAL MEETING OF SHAREHOLDERS OF
PLUM ACQUISITION CORP. III
TO BE HELD [•], 2025
To the shareholders of Plum Acquisition Corp. III (“Plum”):
NOTICE IS HEREBY GIVEN that the extraordinary general meeting (the “Plum Shareholders’ Meeting”) of shareholders of Plum (the “Plum Shareholders”) will be held at 10:00 a.m., Eastern Time, on [•], 2025, virtually pursuant to the procedures described in the accompanying proxy statement/prospectus for the purposes of Cayman Islands law and Plum’s Amended and Restated Memorandum and Articles of Association (the “Plum Articles”).
At the Plum Shareholders’ Meeting, Plum Shareholders will be asked to consider and vote upon the following proposals:
• The Domestication Proposal — To approve, by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and Cayman Islands Companies Act (As Revised) (the “Companies Act”) and the domestication of Plum (the “Domestication”) as a British Columbia corporation in accordance with the applicable provisions of the Business Corporations Act (British Columbia) (the “BCBCA”), including the adoption of the Domestication Articles (the “Domestication Proposal” or “Proposal No. 1”);
• Business Combination Proposal — To approve, by Ordinary Resolution, the Business Combination Agreement, dated as of August 22, 2024 (as may be amended, supplemented or otherwise modified from time to time, the “Business Combination Agreement” and the transactions contemplated thereby, collectively, the “Business Combination”) by Plum, Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum (“Amalco”), Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia (“PubCo”), and Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia (“TRC”), including the Arrangement Resolution pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement attached hereto as Annex B, (i) Plum shall effect the Domestication, (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation (the “Business Combination Proposal” or “Proposal No. 2”). A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A;
• Advisory Organization Documents Proposals — To approve on a non-binding advisory basis, by Ordinary Resolution, the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately in accordance with U.S. Securities and Exchange Commission guidance (the “Advisory Organizational Documents Proposals” or “Proposal No. 3”). The full text of the PubCo Closing Articles are attached to the accompanying proxy statement/prospectus as Annex E. Proposal No. 3 is separated into sub-proposals submitted to Plum Shareholders to approve on a non-binding advisory basis, by Ordinary Resolution, those governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights as described in the following paragraphs (a)–(d):
(a) the proposed PubCo Closing Articles would change the authorized share capital from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal or par value of $0.0001 each, to an unlimited number of PubCo Common Shares (the “Authorized Capital Proposal” or “Proposal No. 3A”);
(b) the proposed PubCo Closing Articles would reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting (the “Quorum Proposal” or “Proposal No. 3B”);
(c) the proposed PubCo Closing Articles would change the name of the company from “Plum III Merger Corp.” to “Tactical Resources Corporation” (the “Name Change Proposal” or “Proposal No. 3C”); and
(d) the proposed PubCo Closing Articles would not include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters (the “Other Matters Proposal” or “Proposal No. 3D” and, together with the Authorized Capital Proposal, the Quorum Proposal and the Name Change Proposal, the “Sub-Proposals”);
• Incentive Plan Proposal — To approve, by Ordinary Resolution, for the purposes of complying with the rules of the Nasdaq Stock Market, the issuance of PubCo Common Shares pursuant to the PubCo Omnibus Equity Incentive Plan (the “Incentive Plan Proposal” or “Proposal No. 4”). A copy of the Incentive Plan is attached to this proxy statement/prospectus as Annex K;
• Adjournment Proposal — If put to Plum Shareholders for a vote, a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the foregoing proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals (the “Adjournment Proposal” or “Proposal No. 5” and, together with the Domestication Proposal, the Business Combination Proposal, the Incentive Plan Proposal and the Advisory Organizational Documents Proposals, the “Proposals”). If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
The record date for the Plum Shareholders’ Meeting is [•], 2025. Only holders of record of Plum Class A ordinary shares, par value $0.0001 per share (the “Plum Class A Shares”), and Plum Class B ordinary shares, par value $0.0001 per share (the “Plum Class B Shares” and together with the Plum Class A Shares, the “Plum Common Shares”), at the close of business on [•], 2025 are entitled to notice of, and to vote at, the Plum Shareholders’ Meeting and any adjournments or postponements thereof.
The approval of the Domestication Proposal requires a special resolution under Cayman Islands Companies Law (a “Special Resolution”), being the affirmative vote of at least a two-thirds (66 2/3%) majority of the votes cast by the holders of the Plum Common Shares present in person or represented by proxy at the Extraordinary General Meeting and entitled to vote on such matter. The approval of each of the Business Combination Proposal, the Advisory Organizational Documents Proposal, the Incentive Plan Proposal and the Adjournment Proposal requires an ordinary resolution under the Cayman Islands Company Law (an “Ordinary Resolution”), being the affirmative vote of at least a majority of the votes cast by the holders of the Plum Common Shares present in person or represented by proxy at the Extraordinary General Meeting and entitled to vote on such matter.
Plum is providing the accompanying proxy statement/prospectus and accompanying proxy card to the Plum Shareholders in connection with the solicitation of proxies to be voted at the Plum Shareholders’ Meeting and at any adjournments of the Plum Shareholders’ Meeting. Information about the Plum Shareholders’ Meeting, the Business Combination and other related business to be considered by Plum Shareholders at the Plum Shareholders’ Meeting is included in the accompanying proxy statement/prospectus.
Whether or not you plan to attend the Plum Shareholders’ Meeting, all Plum Shareholders are urged to read the accompanying proxy statement/prospectus, including the annexes and other documents referred to therein, carefully and in their entirety. In particular, you should carefully consider the matters discussed under “Risk Factors” beginning on page 70 of the accompanying proxy statement/prospectus.
Whether or not you plan to attend the Plum Shareholders’ Meeting, please submit your proxy by completing, signing, dating and mailing the enclosed proxy card in the pre-addressed postage paid envelope or submit your proxy by telephone or over the internet by following the instructions on your proxy card. If your Plum Common Shares are held in an account at a brokerage firm or bank, you must instruct your broker or bank on how to vote your Plum Common Shares or, if you wish to attend the Plum Shareholders’ Meeting and vote online, you must obtain a proxy from your broker or bank.
Pursuant to the Plum Articles, a holder of Plum Class A Shares issued as part of the units sold in Plum’s initial public offering (the “Plum IPO,” such shares, the “Plum Public Shares” and, holders of such Plum Public Shares the “Plum Public Shareholders”) may request that PubCo redeem all or a portion of its Plum Public Shares for cash if the Business Combination is consummated. As a holder of Plum Public Shares, you will be entitled to exercise your redemption rights if you:
• hold Plum Public Shares, or if you hold Plum Public Shares through Plum units sold in the Plum IPO (the “Plum Units”), you elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising your redemption rights;
• submit a written request to Continental Stock Transfer & Trust Company, Plum’s transfer agent, in which you (i) request the exercise of your redemption rights with respect to all or a portion of your Plum Public Shares for cash, and (ii) identify yourself as the beneficial holder of the Plum Public Shares and provide your legal name, phone number and address; and
• deliver your Plum Public Shares to Continental Stock Transfer & Trust Company, Plum’s transfer agent, physically or electronically through The Depository Trust Company.
Holders must complete the procedures for electing to redeem their Plum Public Shares in the manner described above prior to 10:30 a.m., Eastern Time, on [•], 2025 (two business days before the Plum Shareholders’ Meeting) in order for their shares to be redeemed.
Holders of Plum Units must elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising their redemption rights with respect to the Plum Public Shares. If Plum Public Shareholders hold their Plum Units in an account at a brokerage firm or bank, such Plum Public Shareholders must notify their broker or bank that they elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants, or if a holder holds Plum Units registered in its own name, the holder must contact Continental Stock Transfer & Trust Company, Plum’s transfer agent, directly and instruct it to do so. The redemption rights include the requirement that a holder must identify itself to Plum in order to validly exercise its redemption rights. Plum Public Shareholders may elect to exercise their redemption rights with respect to their Plum Public Shares even if they vote “FOR” the Business Combination Proposal. If the Business Combination is not consummated, the Plum Public Shares will be returned to the respective holder, broker or bank. If the Business Combination is consummated, and if a Plum Public Shareholder properly exercises its redemption rights with respect to all or a portion of the Plum Public Shares that it holds and timely delivers its shares to Continental Stock Transfer & Trust Company, PubCo will redeem the related common shares in the authorized share capital of PubCo (“PubCo Common Shares”) for a per share price, payable in cash, equal to the pro rata portion of the trust account established at the consummation of the Plum IPO, including interest earned on the funds held in the trust account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination. For illustrative purposes, as of [•], 2025, this would have amounted to approximately $[•] per issued and outstanding Plum Public Share. If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation, and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practicable after consummation of the Business Combination. Please see the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” in the accompanying proxy statement/prospectus for a detailed description of the procedures to be followed if you wish to exercise your redemption rights with respect to your Plum Public Shares.
Plum may not consummate the Business Combination unless the Domestication Proposal and the Business Combination Proposal are approved at the Plum Shareholders’ Meeting. The Advisory Organizational Documents Proposals are non-binding and are not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. In the event the Adjournment Proposal is put forth at the Plum Shareholders’ Meeting, it
will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Approval of the Domestication Proposal requires the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of not less than two thirds (662⁄3%) of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. The Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal require the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of a majority of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. Abstentions and broker non-votes, while considered present for the purposes of establishing a quorum, will not count as votes cast at the Plum Shareholders’ Meeting (assuming a quorum is present). Accordingly, a Plum Shareholder’s failure to vote by proxy or to vote online at the Plum Shareholders’ Meeting will not, if a valid quorum is established, have any effect on the outcome of any vote on any of the Proposals.
YOUR VOTE IS VERY IMPORTANT, REGARDLESS OF THE NUMBER OF PLUM COMMON SHARES YOU OWN. To ensure your representation at the Plum Shareholders’ Meeting, please complete and return the enclosed proxy card or submit your proxy by telephone or over the internet by following the instructions on your proxy card. Please submit your proxy promptly, whether or not you expect to attend the Plum Shareholders’ Meeting. If you hold your Plum Common Shares in “street name,” you should instruct your broker, bank or other nominee how to vote in accordance with the voting instruction form you received from your broker, bank or other nominee.
The board of directors of Plum has unanimously approved the Business Combination Agreement and the transactions contemplated thereby and recommends that you vote “FOR” the Domestication Proposal, “FOR” the Business Combination Proposal, “FOR” the Advisory Organizational Documents Proposals, “FOR” the Incentive Plan Proposal, and (if put) “FOR” the Adjournment Proposal. Signed and dated proxies received by Plum without an indication of how the Plum Shareholder intends to vote on a Proposal will be voted “FOR” each Proposal being submitted to a vote of the Plum Shareholders at the Plum Shareholders’ Meeting.
Your attention is directed to the proxy statement/prospectus accompanying this notice (including the financial statements and annexes attached thereto) for a more complete description of the proposed Business Combination and related transactions and each of the Proposals. Plum encourages you to read this proxy statement/prospectus carefully. If you have any questions or need assistance voting your shares, please call Plum’s proxy solicitor, [•], at [•], or banks and brokerage firms, please call collect at [•].
[•], 2025
|
By Order of the Board of Directors |
||
|
/s/ Kanishka Roy |
||
|
Kanishka Roy |
|
Page |
||
|
1 |
||
|
1 |
||
|
2 |
||
|
14 |
||
|
QUESTIONS AND ANSWERS ABOUT THE Plum SHAREHOLDERS’ MEETING AND THE BUSINESS COMBINATION |
22 |
|
|
44 |
||
|
70 |
||
|
108 |
||
|
110 |
||
|
117 |
||
|
MATERIAL U.S. FEDERAL INCOME TAX CONSIDERATIONS FOR U.S. HOLDERS |
172 |
|
|
193 |
||
|
206 |
||
|
UNAUDITED PRO FORMA CONDENSED CONSOLIDATED FINANCIAL INFORMATION |
208 |
|
|
218 |
||
|
219 |
||
|
Plum MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS |
229 |
|
|
241 |
||
|
264 |
||
|
TRC MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS |
274 |
|
|
289 |
||
|
300 |
||
|
314 |
||
|
321 |
||
|
329 |
||
|
332 |
||
|
334 |
||
|
336 |
||
|
PROPOSAL NO. 3 — THE ADVISORY ORGANIZATIONAL DOCUMENTS PROPOSALS |
338 |
|
|
341 |
||
|
344 |
||
|
345 |
||
|
345 |
||
|
345 |
||
|
346 |
||
|
346 |
||
|
346 |
||
|
SERVICE OF PROCESS AND ENFORCEABILITY OF CIVIL LIABILITIES UNDER U.S. SECURITIES LAWS |
347 |
|
|
348 |
||
|
F-1 |
||
|
A-1-1 |
||
|
ANNEX A-2 — AMENDMENT NO 1 TO BUSINESS COMBINATION AGREEMENT |
A-2-1 |
|
|
ANNEX A-3 — AMENDMENT NO 2 TO BUSINESS COMBINATION AGREEMENT |
A-3-1 |
|
|
B-1 |
i
|
Page |
||
|
C-1 |
||
|
D-1 |
||
|
E-1 |
||
|
F-1 |
||
|
G-1 |
||
|
H-1 |
||
|
I-1 |
||
|
J-1 |
||
|
K-1 |
||
|
L-1 |
||
|
M-1 |
||
|
N-1 |
||
|
O-1 |
ii
ABOUT THIS PROXY STATEMENT/PROSPECTUS
This proxy statement/prospectus, which forms part of a registration statement on Form F-4 filed with the SEC by PubCo, as it may be amended or supplemented from time to time (File No. 333-[•]) (the “Registration Statement”), serves as:
• A notice of meeting and proxy statement of Plum under Section 14(a) of the Exchange Act, for the Plum Shareholders’ Meeting being held on [•], 2025, where Plum Shareholders will vote on, among other things, the proposed Business Combination and related transactions and each of the Proposals described herein; and
• A prospectus of PubCo under Section 5 of the Securities Act with respect to the (i) PubCo Common Shares that Plum Shareholders and TRC shareholders will receive in the Business Combination; (ii) PubCo Warrants that Plum Warrant Holders will receive in the Business Combination; and (iii) PubCo Common Shares that may be issued upon exercise of the PubCo Warrants.
This information is available without charge to you upon written or oral request. To make this request, you should contact Plum’s proxy solicitor at:
[We expect to engage a proxy solicitation agent and incur customary fees in connection therewith.]
To obtain timely delivery of requested materials, you must request the information no later than five business days prior to the date of the Plum Shareholders’ Meeting.
You may also obtain additional information about Plum from documents filed with the SEC by following the instruction in the section entitled “Where You Can Find More Information.”
This proxy statement/prospectus contains estimates, projections, and other information concerning PubCo’s and TRC’s industry and business, as well as data regarding market research, estimates, forecasts and projections prepared by PubCo’s and TRC’s management. Information that is based on market research, estimates, forecasts, projections, or similar methodologies is inherently subject to uncertainties, and actual events or circumstances may differ materially from events and circumstances that are assumed in this information. The industry in which PubCo and TRC operate, and PubCo will operate, is subject to a high degree of uncertainty and risk due to a variety of factors, including those described in the section titled “Risk Factors.” Unless otherwise expressly stated, PubCo and TRC obtained industry, business, market, and other data from reports, research surveys, studies, and similar data prepared by market research firms and other third parties, industry and general publications, government data, and similar sources. While PubCo and TRC have compiled, extracted, and reproduced industry data from these sources, PubCo and TRC have not independently verified the data. Forecasts and other forward-looking information with respect to industry, business, market, and other data are subject to the same qualifications and additional uncertainties regarding the other forward-looking statements in this proxy statement/prospectus. See “Cautionary Note Regarding Forward-Looking Statements.”
1
TRADEMARKS AND TRADE NAMES
TRC and Plum own or have rights to various trademarks, service marks and trade names that they use in connection with the operation of their respective businesses. This proxy statement/prospectus also contains trademarks, service marks and trade names of third parties, which are the property of their respective owners. The use or display of third parties’ trademarks, service marks, trade names or products in this proxy statement/prospectus is not intended to create, and does not imply, a relationship with TRC, PubCo or Plum, or an endorsement or sponsorship by or of TRC, PubCo or Plum. Solely for convenience, the trademarks, service marks and trade names referred to in this proxy statement/prospectus may appear without the ®, ™ or ℠ symbols, but such references are not intended to indicate, in any way, that TRC, PubCo or Plum will not assert, to the fullest extent under applicable law, their rights or the right of the applicable licensor to these trademarks, service marks and trade names.
PRESENTATION OF FINANCIAL INFORMATION
This proxy statement/prospectus contains:
• the audited consolidated financial statements of Plum as of and for the fiscal years ended December 31, 2024 and 2023 and the unaudited financial statements of Plum as of and for the three months ended March 31, 2025 and 2024;
• the audited financial statements of TRC as of and for the fiscal years ended July 31, 2024 and 2023, and the unaudited financial statements of TRC as of and for the three and six months ended January 31, 2025 and 2024; and
• the audited financial statements of PubCo as of and for the period ended December 31, 2024 and the unaudited financial statements of PubCo as of and for the three months ended March 31, 2025.
Unless indicated otherwise, financial data presented in this proxy statement/prospectus has been taken from the audited and unaudited consolidated financial statements of Plum, PubCo and TRC, as applicable, included in this proxy statement/prospectus. Unless otherwise indicated, financial information of Plum, PubCo and TRC has been prepared in accordance with accounting principles generally accepted in the United States (“U.S. GAAP”).
As presented herein, TRC presents its financial statements in U.S. dollars. Plum publishes its consolidated financial statements in U.S. dollars. PubCo presents its financial statements in U.S. dollars. In this proxy statement/prospectus, unless otherwise specified, all monetary amounts are in U.S. dollars, all references to “$,” “US$,” “USD” and “dollars” mean U.S. dollars and all references to “C$” and “CAD” mean Canadian dollars.
EXCHANGE RATES
TRC’s reporting currency is the U.S. dollar. The determination of the functional and reporting currency of each group company is based on the primary currency in which the company operates. For TRC, the Canadian dollar is the functional currency.
2
CERTAIN DEFINED TERMS
Unless the context otherwise requires, references in this proxy statement/prospectus to:
“Adjournment Proposal” means a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the other Proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals.
“Advisory Organizational Documents Proposals” means non-binding advisory votes with regard to the Authorized Capital Proposal, the Quorum Proposal, the Name Change Proposal and the Other Matters Proposal.
“Aggregate Exercise Price” means the aggregate dollar amount payable to TRC upon (a) the conversion of the TRC Convertible Debenture in accordance with its terms and (b) the exercise of all vested In-the-Money TRC Options and vested In-the-Money TRC Warrants that are outstanding immediately prior to the TRC Amalgamation Effective Time.
“Alternative Transaction” means, other than any of the Transactions, any Permitted Financing and the acquisition or disposition of equipment or other tangible personal property in the ordinary course, (a) any acquisition or purchase, direct or indirect, of (i) more than 25% of the consolidated assets of such Person and its Subsidiaries (based on the fair market value thereof as determined in good faith by the board of directors (or equivalent governing body) of such Person) or (ii) more than 25% of the total voting power of the Equity Securities of (A) such Person or (B) one or more Subsidiaries of such Person holding assets constituting, individually or in the aggregate, more than 25% of the consolidated assets of such Person and its Subsidiaries, (b) any take-over bid, issuer bid, tender offer (including a self-tender offer) or exchange offer that, if consummated, would result in any Person beneficially owning more than 25% of the total voting power of the Equity Securities of (i) such Person or (ii) one or more Subsidiaries of such Person holding assets constituting, individually or in the aggregate, more than 25% of the consolidated assets of such Person and its Subsidiaries, or (c) a merger, amalgamation, consolidation, share exchange, business combination, arrangement or other similar transaction involving (i) such Person or (ii) one or more Subsidiaries of such Person holding assets constituting, individually or in the aggregate, more than 25% or more of the consolidated assets of such Person and its Subsidiaries, in each case, that would result in any Person or Group who does not beneficially own more than 25% of the total voting power of the Equity Securities of such Person or such Subsidiaries prior to the consummation of such transaction becoming the beneficial owner of more than 25% of the total voting power of the Equity Securities of such Person or such Subsidiaries following the consummation of such transaction.
“Amalco” means Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum.
“Amalco Articles” means the Articles of PubCo adopted on August 8, 2024, as amended, restated or amended and restated from time to time.
“Amalco Certificate” means the Certificate of Incorporation of Amalco filed with the Registrar on August 8, 2024, as amended, restated or amended and restated from time to time.
“Amalco Governing Documents” means, collectively, the Amalco Articles and the Amalco Certificate.
“Amalco Shares” means the issued and outstanding common shares of Amalco
“Amalco Sole Shareholder” means Plum.
“Amalco Sole Shareholder Approval” means approval by the affirmative vote of the Amalco Sole Shareholder by means of a special resolution in respect of the Arrangement pursuant to the terms and subject to the conditions of the Plan of Arrangement, applicable Law and the Amalco Governing Documents.
“Amalgamations” means the Plum Amalgamation and the TRC Amalgamation.
3
“Ancillary Agreements” means, collectively, (a) the Plan of Arrangement, (b) the TRC Securityholder Support Agreement, (c) the Sponsor Support Agreement, (d) the Sponsor Parties Lock-up Agreement, (e) the Registration Rights Agreement, (f) the PIPE Subscription Agreements and (g) all other agreements, certificates and instruments executed and delivered by any of Plum, Amalco, PubCo, or TRC in connection with the Transactions.
“Arrangement” means an arrangement under Section 288 of the BCBCA on the terms and subject to the conditions set forth in the Plan of Arrangement, subject to any amendments or variations to the Plan of Arrangement made in accordance with the terms of the Business Combination Agreement and the Plan of Arrangement or made at the direction of the Court in the Interim Order and the Final Order with the prior written consent of Plum and TRC, such consent not to be unreasonably withheld, conditioned or delayed.
“Arrangement Consideration” means the sum of (a) $500,000,000, plus (b) the Aggregate Exercise Price, plus (c) the gross proceeds received by TRC in connection with any Permitted Financing.
“Arrangement Consideration Shares” means the aggregate of all PubCo Common Shares issued to holders of TRC Common Shares.
“Authorized Capital Proposal” means the proposal to change the authorized share capital of Plum to PubCo from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal or par value of $0.0001 each, to an unlimited number of PubCo Common Shares.
“BCBCA” means the Business Corporations Act (British Columbia).
“Business Combination” means the transactions contemplated by the Business Combination Agreement, including the Domestication and the Amalgamations.
“Business Combination Agreement” means the Business Combination Agreement entered into on August 22, 2024, by and among Plum, Amalco, PubCo and TRC, as it may be amended, supplemented or otherwise modified from time to time.
“Business Combination Proposal” means the Proposal to vote on approval of the Business Combination.
“Closing” means the closing of the Business Combination.
“Closing Date” means the date upon which Closing occurs.
“Code” means the U.S. Internal Revenue Code of 1986.
“Companies Act” means the Cayman Islands Companies Act (As Revised).
“Converted TRC Option” means each TRC Option assumed by PubCo and converted into an option to purchase PubCo Common Shares.
“Converted TRC Option In-The-Money Amount” means, with respect to a given Converted TRC Option, the amount, if any, by which the total fair market value (determined as of immediately following the TRC Amalgamation Effective Time) of the PubCo Common Shares that the holder of such Converted TRC Option is entitled to acquire upon exercise of such Converted TRC Option exceeds the amount payable by such holder to acquire such PubCo Common Shares upon exercise of such Converted TRC Option.
“Converted TRC RSU” means each TRC RSU assumed by PubCo and converted into a restricted stock unit in respect of PubCo Common Shares.
“Court” means the Supreme Court of British Columbia.
“CSA” means the Canadian Securities Administrators.
“CSE” means the Canadian Securities Exchange.
“Deadline Date” means the date to consummate an initial business combination as described in the Plum Articles in Article 49.7.
“Dissent Rights” means the rights of dissent in respect of the Arrangement described in the Plan of Arrangement.
4
“Domestication” means the process whereby Plum shall transfer by way of continuation from the Cayman Islands to the Province of British Columbia in accordance with the Companies Act and continue as a corporation under the Laws of the Province of British Columbia in accordance with the applicable provisions of the BCBCA.
“Domestication Articles” means the articles adopted and filed with the Registrar by Plum in connection with the Domestication.
“Equity Securities” means, with respect to any Person, (a) any capital stock, partnership or membership interest, unit of participation or other similar interest (however designated) in such Person and (b) any option, warrant, purchase right, conversion right, exchange right or other contractual obligation which would entitle any other Person to acquire any such interest in such Person or otherwise entitle any other Person to share in the equity, profits, earnings, losses or gains of such Person (including any interest, the value of which is in any way based on, linked to or derived from any interest described in clause (a), including stock appreciation, phantom stock, profit participation or other similar rights).
“Exchange Act” means the U.S. Securities Exchange Act of 1934.
“Final Order” means the final order of the Court pursuant to Section 291 of the BCBCA, approving the Arrangement, as such order may be amended by the Court with the consent of Plum and TRC, such consent to not be unreasonably withheld, conditioned or delayed, at any time prior to the TRC Amalgamation Effective Time or, if appealed, then, unless such appeal is withdrawn or denied, as affirmed or as amended, on appeal; provided, that any such amendment is reasonably acceptable to each of Plum and TRC.
“Former Sponsor” means Alpha Partners Technology Merger Sponsor LLC, the former sponsor of Plum.
“Fully-Diluted TRC Shares” means, without duplication, the total number of issued and outstanding TRC Common Shares as of immediately prior to the TRC Amalgamation Effective Time, determined on a fully-diluted basis as the sum of (a) the number of TRC Common Shares outstanding immediately prior to the TRC Amalgamation Effective Time and (b) the number of TRC Common Shares issuable (i) in respect of all issued and outstanding TRC RSUs, (ii) upon exercise of all vested In-the-Money TRC Options, (iii) upon exercise of all vested In-the-Money TRC Warrants and (iv) upon conversion of the TRC Convertible Debenture (including the number of TRC Common Shares issuable in respect of all vested In-the-Money TRC Warrants issuable upon the conversion thereof), in each case, in accordance with the terms thereof; provided, that, for the avoidance of doubt, Fully-Diluted TRC Shares shall not include any TRC Common Shares issuable upon exercise of any unvested In-the-Money TRC Options, unvested In-the-Money TRC Warrants, Out-of-the-Money TRC Options or Out-of-the-Money TRC Warrants.
“GAAP” means generally accepted accounting principles in the U.S. as in effect from time to time.
“Governmental Authority” means any federal, state, provincial, municipal, local, international, supranational or foreign government, governmental, regulatory or administrative authority, agency (which, for the purposes of this Agreement, shall include the SEC and the CSA, as applicable), commission, department, board, bureau, agency or similar body or instrumentality thereof, or any court, tribunal or judicial or arbitral body thereof.
“Governmental Order” means any order, judgment, injunction, decree, writ, ruling, stipulation, determination, verdict or award, in each case, entered by or with any Governmental Authority.
“Group” means a “group” of Persons as defined in Section 13(d) of the Exchange Act.
“HSR Act” means the Hart-Scott-Rodino Antitrust Improvements Act of 1976.
“ICA” means the Investment Canada Act.
“IFRS” means International Financial Reporting Standards as issued by the International Accounting Standards Board, as incorporated in the CPA Canada Handbook at the relevant time.
“Interim Order” means the interim order of the Court made pursuant to Section 291 of the BCBCA, attached as Annex N — “Interim Order” providing for, among other things, the calling and holding of the Plum Shareholders’ Meeting and the TRC Shareholders Meeting, as the same may be amended by the Court with the consent of TRC and Plum, such consent not to be unreasonably withheld, conditioned or delayed.
5
“In-the-Money TRC Option” means a TRC Option with an exercise price per TRC Common Share less than $10.00.
“In-the-Money TRC Warrant” means a TRC Warrant with an exercise price per TRC Common Share less than $10.00.
“Key TRC Securityholders” means Ranjeet Sundher, Kuljit Basi, Alnesh Mohan, J. Garry Clark, Justus Parmar, Manavdeep Mukhija, SVK Metrix Inc., Matthew Chatterton, 1129925 BC Ltd., Number Eight Management Ltd. and Blue Bird Capital Enterprises LLC.
“Law” means any statute, law, ordinance, rule, regulation, directive or Governmental Order, in each case, of any Governmental Authority, including general principles of common and civil law.
“MI 61-101” means Multilateral Instrument 61-101 — Protection of Minority Shareholders in Special Transactions, as amended and replaced from time to time.
“Original Registration Rights Agreement” means the Registration Rights Agreement, dated as of July 27, 2021 among Plum and the Sponsor Parties.
“Other Matters Proposal” means the proposal to cause the PubCo Closing Articles not to include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters.
“Out-of-the-Money TRC Options” means TRC Options other than In-the-Money TRC Options.
“Out-of-the-Money TRC Warrants” means TRC Warrants other than In-the-Money TRC Warrants.
“PCAOB” means the U.S. Public Company Accounting Oversight Board and any division or subdivision thereof.
“Peak REE Project” means the project undertaken by TRC to explore and potentially develop rare earth elements from materials extracted from the Sierra Blanca Quarry operated by Sierra Blanca Quarry LLC in Hudspeth County, Texas.
“Permitted Financing” means a financing transaction prior to the TRC Amalgamation Effective Time pursuant to which Equity Securities of TRC are sold.
“Person” means any individual, firm, corporation, partnership, limited liability company, incorporated or unincorporated association, trust, estate, joint venture, joint stock company, union, association, Governmental Authority or other entity, enterprise, authority or business organization of any kind.
“Permitted Financing Securities” means any Equity Securities of TRC issued in any Permitted Financing.
“Plan of Arrangement” means the plan of arrangement attached to this proxy statement/prospectus as Annex B.
“PIPE Investment” means a PIPE Investor’s purchase of PubCo Common Shares concurrently with the Closing, on the terms and subject to the conditions set forth in a PIPE Subscription Agreement.
“PIPE Investment Amount” means the aggregate amount of cash payable to PubCo at the PIPE closing pursuant to the PIPE Subscription Agreements.
“PIPE Investors” means Persons that enter into PIPE Subscription Agreements to purchase PubCo Common Shares for cash.
“PIPE Subscription Agreement” means a contract executed by Plum, PubCo and a PIPE Investor in connection with the PIPE Investment.
“Plum” means Plum Acquisition Corp. III, a Cayman Islands exempt company.
6
“Plum Amalgamation” means, on the terms and subject to the conditions set forth in the Business Combination Agreement and the Plan of Arrangement and in accordance with applicable Law, the amalgamation of Plum and PubCo to form one corporate entity, with the legal existence of PubCo to not cease and PubCo to survive such amalgamation.
“Plum Amalgamation Application” means an amalgamation application as contemplated by the BCBCA.
“Plum Amalgamation Effective Time” means 12:01 a.m. (Pacific Time) on the Closing Date.
“Plum Articles” means (a) for all periods prior to the Domestication, the Amended and Restated Memorandum and Articles of Association of Plum adopted on July 27, 2021, as amended, restated or amended and restated from time to time, and (b) for all periods from and after the Domestication, the Domestication Articles.
“Plum Board” means the board of directors of Plum.
“Plum Certificates” means the Certificate of Incorporation of Plum issued by the Registrar of Companies of the Cayman Islands on February 5, 2021 and the Certificate of Incorporation on Change of Name issued by the Registrar of Companies of the Cayman Islands on 1 February 2024.
“Plum Class A Shares” means (a) for all periods prior to the Domestication, Class A ordinary shares of Plum, par value $0.0001 per share, authorized under the Plum Articles, and (b) for all periods from and after the Domestication, Class A common shares of Plum, par value $0.0001 per share, authorized under the Domestication Articles.
“Plum Class B Shares” means (a) for all periods prior to the Domestication, Class B ordinary shares of Plum, par value $0.0001 per share, authorized under the Plum Articles, and (b) for all periods from and after the Domestication, Class B common shares of Plum, par value $0.0001 per share, authorized under the Domestication Articles.
“Plum Class B Unit” mean a unit of Plum comprised of one Plum Class B Share and one-third of one Plum Class B Warrant.
“Plum Class B Warrant” means a warrant to purchase one Plum Class B Share at an exercise price of $11.50 per share.
“Plum Common Shares” means, collectively, the Plum Class A Shares and the Plum Class B Shares.
“Plum Deadline” means the deadline for Plum to consummate a Business Combination as set forth in the Plum Articles.
“Plum Governing Documents” means, collectively, the Plum Articles and the Plum Certificate.
“Plum Founder Shareholders” means the holders of the Plum Founder Shares.
“Plum Founder Shares” means the Plum Class B Shares or the Plum Class A Shares issued upon conversion of the Plum Class B Shares.
“Plum IPO” means the initial public offering of Plum consummated on July 30, 2021.
“Plum Material Adverse Effect” means any event that has had, or would reasonably be expected to have, individually or in the aggregate, a material adverse effect on (a) the business, assets and liabilities, results of operations or financial condition of Plum, Amalco or PubCo or (b) the ability of Plum, Amalco or PubCo to consummate the Transactions prior to July 30, 2025; provided, however, that in no event shall any of the following, alone or in combination, be deemed to constitute, or be taken into account in determining whether there has been or will be, a Plum Material Adverse Effect: (i) any change or proposed change in any applicable Laws, GAAP or IFRS, or any change in interpretation thereof following the date of the Business Combination Agreement, (ii) any change in interest or exchange rates or economic, political, business or financial market conditions generally, including changes in the credit, debt, securities or capital markets or changes in prices of any security or market index or commodity or any disruption of such markets, (iii) the taking of any action required to be taken, or refraining from taking any action required not to be taken, under the Business Combination Agreement or any Ancillary Agreement, (iv) any act of God, natural disaster (including hurricanes, storms, tornados, flooding, earthquakes, wildfires,
7
volcanic eruptions or similar occurrences), epidemic, pandemic, disease or other outbreak of illness or public health event, acts of nature or change in climate or any other force majeure event (including any escalation or worsening of any of the foregoing), (v) any acts of terrorism or war (whether or not declared), sabotage, civil unrest, curfews, public disorder, riots, hostilities, geopolitical or local, regional, state, national or international political conditions or social conditions (including any escalation or worsening of any of the foregoing), (vi) any matter existing as of the date of the Business Combination Agreement to the extent expressly set forth in Plum’s disclosure schedules to the Business Combination Agreement, (vii) any action taken at the written request of an authorized officer of, or with the written approval or consent of, TRC or (viii) any event attributable to the announcement of the Business Combination Agreement or the pendency of the Transactions; provided, that, in the case of clauses (i), (ii), (iv) and (v), to the extent any such event disproportionately affects Plum or Amalco relative to other participants in the industries or markets in which Plum and Amalco operate, such event shall not be excluded from the determination of whether there has been, or would reasonably be expected to be, a Plum Material Adverse Effect.
“Plum Miscellaneous Agreement” means any business combination marketing agreement, financial advisory agreement, placement agent agreement or any similar agreement in respect of the Transactions to which Plum, Sponsor or any of their respective affiliates is a party.
“Plum Ordinary Units” means, collectively, the Plum Public Units and the Plum Private Units.
“Plum Preference Shares” means (a) for all periods prior to the Domestication, preference shares of Plum, par value $0.0001 per share, authorized under the Plum Articles, and (b) for all periods from and after the Domestication, preference shares of Plum, par value $0.0001 per share, authorized under the Domestication Articles.
“Plum Private Units” means units of Plum sold in one or more private placements consummated concurrently with the Plum IPO, each unit comprised of one Plum Class A Share and one-third of one Plum Private Warrant.
“Plum Private Warrant” means a warrant to purchase one Plum Class A Share at an exercise price of $11.50 per share sold in a private placement consummated concurrently with the Plum IPO.
“Plum Public Shares” means the Plum Shares included in units of Plum sold in the Plum IPO.
“Plum Public Units” means units of Plum sold in the Plum IPO, each unit comprised of one Plum Class A Share and one-third of one Plum Public Warrant.
“Plum Public Warrant” means a warrant to purchase one Plum Class A Share at an exercise price of $11.50 per share included in a Plum Public Unit sold in the Plum IPO.
“Plum Securities” means, collectively, the Plum Units, the Plum Shares and the Plum Warrants.
“Plum Share Redemption” means the election (not validly withdrawn or cancelled prior to the Closing) of an eligible (as determined in accordance with the Plum Articles) holder of Plum Class A Shares to redeem all or a portion of the Plum Class A Shares held by such holder at a per share price, payable in cash, equal to a pro rata share of the aggregate amount on deposit in the Trust Account (including any interest earned on the funds held in the Trust Account, but net of Taxes payable and up to $100,000 to pay dissolution expenses) in accordance with the Plum Articles in connection with the consummation of the Transactions.
“Plum Shareholder” means any holder of Plum Shares.
“Plum Shareholder Proposals” means the proposals at the Plum Shareholders’ Meeting.
“Plum Shareholders’ Approval” means the approval of the Plum Shareholder Proposals, in each case, by an affirmative vote of the holders of at least a majority of Plum Shares entitled to vote, who attend and vote thereupon (as determined in accordance with the Plum Governing Documents and applicable Law) at a Plum Shareholders’ Meeting duly called by the Plum Board and held for such purpose.
“Plum Shareholders’ Meeting” means the extraordinary general meeting of shareholders of Plum at which the Proposals will be voted upon.
“Plum Shares” means, collectively, the Plum Common Shares and the Plum Preference Shares.
8
“Plum Transaction Expenses” means, without duplication, all fees and expenses incurred by or on behalf of Plum, PubCo or Amalco (whether or not billed or accrued for) as a result of or in connection with the preparation, negotiation, documentation and execution of the Business Combination Agreement and the Ancillary Agreements, the performance of the terms thereof and the consummation of the Transactions, including (a) all fees, costs, expenses, brokerage fees, commissions, finders’ fees and disbursements of financial advisors, investment banks, data room administrators, attorneys, accountants and other advisors and service providers, (b) any change in control bonus, transaction bonus or retention bonus to be paid to any current or former employee, independent contractor, director or officer of Plum, PubCo or Amalco at or after the Closing pursuant to any contract to which Plum, PubCo or Amalco is a party prior to the Closing which becomes payable (including if subject to continued employment) solely as a result of the execution of the Business Combination Agreement or the consummation of the Transactions and not because of any action of PubCo or its Subsidiaries following the Closing (including any payroll or employment taxes payable by Plum, PubCo or Amalco in connection with the making of any such payments or any employer contribution resulting from, or required to be made as a result of, any such payments), (c) all fees, costs and expenses in connection with the negotiation, preparation, execution, authorization or performance of the PIPE Subscription Agreements and the consummation of the PIPE Investment, (d) 50% of any and all filing fees payable to the SEC in connection with, and all fees, costs and expenses in connection with the preparation and mailing of, the proxy/registration statement, (e) any amounts due to the underwriters of the Plum IPO, (f) any costs or fees relating to the preparation, filing and mailing of any proxy statement(s) for the purpose of amending the Plum Governing Documents and the Trust Agreement, in each case, to extend the time period for Plum to consummate a Business Combination, or the seeking of any solicitation of proxies thereunder, the holding of any meeting of the Plum Shareholders to consider, vote on and approve any such extension of the time period for Plum to consummate a Business Combination (including the value of any additional securities or economic inducements offered to Plum Shareholders in connection therewith), in each case if necessary and applicable, (g) any costs or fees incurred by Plum, PubCo or Amalco in connection with entering into agreements with any Plum Shareholders to incentivize them to unwind or facilitate the unwinding of any election to effect any Plum Share Redemption (which such agreements shall be subject to the prior written consent of TRC), (h) 50% of any and all filing fees payable to any Governmental Authorities in connection with regulatory approvals or any other necessary approval, consent, registration, variance, waiver, license, permit, certification, registration or other authorization of any Governmental Authority, or the expiration or termination of any waiting period of any required filings or applications under any applicable Laws, in connection with the consummation of the Transactions, (i) all fees, costs and expenses associated with the preparation and furnishing by Plum, PubCo or Amalco of certain information pursuant to the terms of the Business Combination Agreement and (j) all other costs and expenses incurred or payable by Plum, PubCo or Amalco in connection with their respective operations through the Closing Date.
“Plum Units” means, collectively, the Plum Ordinary Units and the Plum Class B Units.
“Plum Warrant Agent” means Continental Stock Transfer & Trust Company.
“Plum Warrant Agreement” means that certain Warrant Agreement, dated as of July 27, 2021, by and between Plum and the Plum Warrant Agent.
“Plum Warrants” means, collectively, the Plum Public Warrants, the Plum Private Warrants and the Plum Class B Warrants.
“Price per TRC Share” means the quotient, expressed as a dollar amount, obtained by dividing (a) the Arrangement Consideration by (b) the Fully-Diluted TRC Shares.
“Proposal No. 1” means the Proposal to vote on approval of the Domestication.
“Proposal No. 2” means the Proposal to vote on approval of the Business Combination.
“Proposal No. 3A” means the Proposal to vote on approval of the Authorized Capital Proposal.
“Proposal No. 3B” means the Proposal to vote on approval of the Quorum Proposal.
“Proposal No. 3C” means the Proposal to vote on approval of the Name Change Proposal.
“Proposal No. 3D” means the Proposal to vote on approval of the Other Matters Proposal.
“Proposal No. 4” means the Proposal to vote on approval of the Incentive Plan.
“Proposal No. 5” means the Proposal to vote on approval of the Adjournment.
9
“Proposals” means the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposal, the Incentive Plan Proposal and the Adjournment Proposal.
“PubCo” means Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia.
“PubCo Articles” means (a) for all periods prior to the Plum Amalgamation, the Articles of PubCo adopted on August 8, 2024, as amended, restated or amended and restated from time to time, and (b) thereafter, the PubCo Closing Articles.
“PubCo Assumed Plum Warrant” means each Plum Warrant outstanding and unexercised immediately prior to the Closing that is converted into a warrant to purchase a number of PubCo Common Shares determined in accordance with the terms of such Plum Warrant.
“PubCo Assumed TRC Warrant” means each TRC Warrant outstanding and unexercised immediately prior to the Closing that is converted into a warrant to purchase a number of PubCo Common Shares determined in accordance with the terms of such TRC Warrant.
“PubCo Certificate” means the Certificate of Incorporation of PubCo filed with the Registrar on August 8, 2024, as amended, restated or amended and restated from time to time.
“PubCo Closing Articles” means the articles adopted and filed with the Registrar by PubCo in connection with the Plum Amalgamation.
“PubCo Common Shares” means the common shares of PubCo, par value $0.0001 per share.
“PubCo Governing Documents” means, collectively, the PubCo Articles and the PubCo Certificate.
“PubCo Sole Shareholder” means Kanishka Roy, as a nominee of Plum.
“PubCo Sole Shareholder Approval” means approval by the affirmative vote of the PubCo Sole Shareholder by means of a special resolution in respect of the Plum Amalgamation and the Arrangement pursuant to the terms and subject to the conditions of the Business Combination Agreement, the Plan of Arrangement, applicable Law and the PubCo Governing Documents.
“PubCo Warrants” means, collectively, the PubCo Assumed TRC Warrants and the PubCo Assumed Plum Warrants.
“Quorum Proposal” means the proposal to reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting.
“REE” means the group of 17 rare earth elements on the periodic table of elements including the 15 elements of the lanthanide series together with the transition metals scandium and yttrium.
“Registrar” means the Registrar of Companies appointed under Section 400 of the BCBCA.
“Registration Rights Agreement” the Registration Rights Agreement to be entered into at Closing among PubCo and the Sponsor Parties pursuant to which, among other things, (a) PubCo (as successor-in-interest to Plum) and the Sponsor Parties shall terminate the Original Registration Rights Agreement and (b) PubCo shall provide the Sponsor Parties with certain demand and piggyback registration rights with respect to the PubCo Common Shares (and any securities convertible into or exercisable for PubCo Common Shares) to be held by such Persons immediately following the Closing.
“SEC” means the U.S. Securities and Exchange Commission.
“Securities Act” means the U.S. Securities Act of 1933.
“Sponsor” means Mercury Capital, LLC, the sponsor of Plum.
“Sponsor Incentive Shares” means 2,030,860 Plum Class B Shares held by Sponsor as of the date of the Business Combination Agreement.
10
“Sponsor Parties” means Sponsor, Former Sponsor and Kanishka Roy.
“Sponsor Support Agreement” means the Sponsor Support Agreement, dated as of August 22, 2024, among PubCo, Plum, TRC and the Sponsor Parties pursuant to which, among other things, (a) each of the Sponsor Parties agreed to (i) refrain from transferring Plum Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (ii) vote Plum Shares and any additional Plum Shares acquired prior to the Plum Shareholders’ Meeting in favor of each of the Plum Shareholder Proposals at the Plum Shareholders’ Meeting, (iii) waive, and not exercise, any rights to elect to effect a Plum Share Redemption in connection with the Plum Shareholders’ Approval or the Transactions and (iv) waive, and not enforce, any anti-dilution rights under the Plum Governing Documents in connection with the Transactions, and (b) Sponsor has agreed to use, and subject to forfeiture, the Sponsor Incentive Units as set forth therein.
“Sponsor Parties Lock-up Agreement” means the Sponsor Parties Lock-Up Agreement, dated as of August 22, 2024, among PubCo, Plum and the Sponsor Parties pursuant to which, among other things, certain PubCo Common Shares to be held by the Sponsor Parties immediately following the Closing will be subject to certain limitations on disposition as set forth therein.
“Takeover Statute” means any moratorium, fair price, business combination, takeover, interested shareholder or similar Law.
“Tax Act” means the Income Tax Act (Canada).
“Transactions” means the transactions contemplated by the Business Combination Agreement and the Ancillary Agreements.
“Transfer Agent” means Continental Stock & Trust Company.
“TRC” means Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia.
“TRC Amalgamation” means immediately following the Plum Amalgamation, on the terms and subject to the conditions set forth in the Business Combination Agreement and the Plan of Arrangement and in accordance with applicable Law, the amalgamation of TRC and Amalco to form one corporate entity, with the legal existence of TRC to not cease and TRC to survive such amalgamation.
“TRC Amalgamation Effective Time” means the time at which the TRC Amalgamation occurs, which shall be immediately following the completion of the Plum Amalgamation at the Plum Amalgamation Effective Time.
“TRC Arrangement Resolution” means a special resolution of the holders of TRC Common Shares in respect of the Arrangement to be considered at the TRC Shareholders Meeting.
“TRC Articles” means (a) the Articles of TRC adopted on September 7, 2022, as amended, restated or amended and restated from time to time, and (b) for all periods from and after the TRC Amalgamation, the articles adopted and filed with the Registrar by TRC in connection with the TRC Amalgamation.
“TRC Awards” means TRC Options and TRC RSUs granted under the TRC Stock Plan or otherwise.
“TRC Certificate” means the Certificate of Incorporation of TRC filed with the Registrar of Companies of the Province of British Columbia on June 25, 2018, as amended, restated or amended and restated from time to time.
“TRC Common Shares” means the common shares without par value in the capital of TRC.
“TRC Convertible Debenture” means that certain 10.0% Unsecured Convertible Debenture issued by TRC, dated as of May 17, 2024.
“TRC Exchange Ratio” means the quotient obtained by dividing (a) the Price per TRC Share by (b) $10.00. The numbers shown in this proxy statement/prospectus assume a TRC Exchange Ratio of 0.87084460.
“TRC Governing Documents” means, collectively, the TRC Articles and the TRC Certificate.
“TRC Information Circular” means the notice of the TRC Shareholders Meeting to be sent to the TRC Shareholders, and the accompanying management information circular to be prepared in connection with the TRC Shareholders Meeting, together with any amendments thereto or supplements thereof in accordance with the terms of the Business Combination Agreement.
11
“TRC Option In-The-Money Amount” means, with respect to a given TRC Option, the amount, if any, by which the total fair market value (determined as of immediately prior to the TRC Amalgamation Effective Time) of the TRC Common Shares that the holder of such TRC Option is entitled to acquire upon exercise of such TRC Option exceeds the amount payable by such holder to acquire such TRC Common Shares upon exercise of such TRC Option.
“TRC Options” means the options to purchase TRC Common Shares granted under the TRC Stock Plan.
“TRC RSU Vesting Acceleration” means the vesting in full, effective as of immediately prior to the TRC Amalgamation Effective Time but subject to the substantially concurrent occurrence of the TRC Amalgamation, of all TRC RSUs outstanding as of such time in accordance with the TRC Stock Plan.
“TRC RSUs” means the restricted stock units of TRC granted under the TRC Stock Plan.
“TRC Securities” means, collectively, TRC Common Shares, TRC Options, TRC RSUs, TRC Warrants and the TRC Convertible Debenture.
“TRC Securityholder Support Agreement” means the Company Securityholder Support Agreement, dated as of August 22, 2024, by and among PubCo, Plum, TRC and the Key TRC Securityholders pursuant to which, among other things, each of the Key TRC Securityholders agreed to (a) refrain from transferring any of his, her or its TRC Common Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (b) vote his, her or its TRC Common Shares and any additional TRC Common Shares he, she or it acquires prior to the TRC Shareholders Meeting in favor of each of the TRC Shareholder Proposals, including the TRC Arrangement Resolution, at the TRC Shareholders Meeting and (c) waive, and not exercise, any Dissent Rights he, she or it may have with respect to the Transactions.
“TRC Shareholder” means any holder of TRC Common Shares.
“TRC Shareholder Proposals” means the proposals at the TRC Shareholders Meeting.
“TRC Shareholders Meeting” means the meeting of the TRC Shareholders, including any adjournment or postponement thereof in accordance with the terms of the Business Combination Agreement, that is to be convened as provided by the Interim Order to consider, and if deemed advisable approve, the TRC Shareholder Proposals, including the TRC Arrangement Resolution.
“TRC Shareholders’ Approval” means approval by the affirmative vote of the holders of (a) at least two-thirds of the votes cast at the TRC Shareholders Meeting by the TRC Shareholders, present in person or represented by proxy and entitled to vote at the TRC Shareholders Meeting, and (b) if required under MI 61-101, at least a simple majority of the votes cast at the TRC Shareholders Meeting by the TRC Shareholders, present in person or represented by proxy and entitled to vote at the TRC Shareholders Meeting, other than the votes attached to the TRC Common Shares held by the TRC Shareholders excluded for purpose of such vote under MI 61-101, each pursuant to the terms and subject to the conditions of the Plan of Arrangement, applicable Law and the TRC Governing Documents.
“TRC Stock Plan” means the Tactical Resources Corp. Omnibus Incentive Plan adopted by the TRC Board on August 28, 2023 and approved by the TRC Shareholders on December 7, 2023, as amended, restated or amended and restated from time to time.
“TRC Transaction Expenses” means, without duplication, all fees and expenses incurred by or on behalf of TRC (whether or not billed or accrued for) as a result of or in connection with the preparation, negotiation, documentation and execution of the Business Combination Agreement and the Ancillary Agreements, the performance of the terms thereof and the consummation of the Transactions, including (a) all fees, costs, expenses, brokerage fees, commissions, finders’ fees and disbursements of financial advisors, investment banks, data room administrators, attorneys, accountants and other advisors and service providers, (b) any change in control bonus, transaction bonus or retention bonus to be paid to any current or former employee, independent contractor, director or officer of TRC at or after the Closing pursuant to any contract to which TRC is a party prior to the Closing which becomes payable (including if subject to continued employment) solely as a result of the execution of the Business Combination Agreement or the consummation of the Transactions and not because of any action of PubCo or its Subsidiaries following the Closing, (c) 50% of any and all filing fees payable to any Governmental Authorities
12
in connection with regulatory approvals or any other necessary approval, consent, registration, variance, waiver, license, permit, certification, registration or other authorization of any Governmental Authority, or the expiration or termination of any waiting period of any required filings or applications under any applicable Laws, in connection with the consummation of the Transactions, (d) all fees, costs and expenses in connection with the negotiation, preparation, execution, authorization or performance of agreements relating to the issuance of any Permitted Financing Securities, (e) all fees, costs and expenses associated with the preparation and completion of the TRC Information Circular, (f) all fees, costs and expenses associated with the preparation and furnishing by TRC of certain information pursuant to the terms of the Business Combination Agreement and (g) 50% of any and all filing fees payable to the SEC in connection with the proxy/registration statement in accordance with the terms of the Business Combination Agreement.
“TRC Warrant Agent” means Odyssey Trust Company.
“TRC Warrant Agreement” means that certain Common Share Purchase Warrant Indenture, dated as of September 14, 2021, by and between TRC and the TRC Warrant Agent, as supplemented by that certain First Supplemental Warrant Indenture, dated as of March 12, 2024, by and between TRC and the TRC Warrant Agent.
“TRC Warrants” means the warrants to purchase TRC Common Shares that are outstanding immediately prior to the Closing.
“Trust Agreement” means the Investment Management Trust Agreement, dated as of July 27, 2021, between Plum and Continental Stock Transfer & Trust Company, as trustee.
“TSX-V” means the TSX Venture Exchange.
“U.S.” means the United States of America.
“Working Capital Loans” mean any and all loans to Plum from Sponsor or any of its affiliates.
Unless otherwise specified, the share counts and other data set forth in this proxy statement/prospectus assume the following:
• no Plum Public Shareholders elect to have their PubCo Common Shares redeemed;
• at Closing, 35,073,456 PubCo Common Shares are issued to the TRC Shareholders;
• none of the Sponsor or Former Sponsor or TRC Shareholders purchase any Plum Class A Shares in the open market;
• Sponsor has not made any working capital loans to Plum; and
• that there are no other issuances of equity interests of Plum or TRC prior to or in connection with the Closing.
Further, unless otherwise specified, the share counts, and other information set forth in this proxy statement/prospectus, do not take into account the (i) Plum Warrants currently outstanding or (ii) the PubCo Options and PubCo Warrants which will remain outstanding following the Business Combination and may be exercised at a later date.
Pursuant to the Plum Articles, Plum Public Shareholders may request that PubCo redeem all or a portion of their PubCo Common Shares for cash if the Business Combination is consummated. Any such redemptions related to the Business Combination will take place following the TRC Amalgamation; accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. Certain sections in this proxy statement/prospectus refer to a no redemptions scenario, illustrative redemptions scenario and maximum redemptions scenario. Unless otherwise specified, (i) the no redemptions scenario assumes for illustrative purposes that no PubCo Common Shares are redeemed, and (ii) the maximum redemptions scenario assumes for illustrative purposes that 151,833 PubCo Common Shares are redeemed, resulting in an aggregate payment of approximately $1,711,089 from the Trust Account. For more information, see the section entitled “Unaudited Pro Forma Condensed Consolidated Financial Information.”
13
This Summary Term Sheet, together with the sections entitled “Questions and Answers About the Plum Shareholders’ Meeting and the Business Combination” and “Summary of the Proxy Statement/Prospectus,” summarizes certain information contained in this proxy statement/prospectus but does not contain all of the information that is important to you. You should read carefully this entire proxy statement/prospectus, including the attached annexes, for a more complete understanding of the matters summarized below.
• Plum is a blank check company incorporated as a Cayman Islands exempted company incorporated on February 5, 2021 for the purpose of effecting a merger, amalgamation, share exchange, asset acquisition, share purchase, reorganization or similar business combination involving Plum and one or more target businesses. For more information about Plum, see the section entitled “Business of Plum and Certain Information About Plum.”
• There are currently 1,016,833 Plum Class A Shares and 7,062,500 Plum Class B Shares issued and outstanding. In addition, there are currently 12,059,166 Plum Warrants outstanding, consisting of 9,416,666 Plum Public Warrants and 2,642,500 Plum Private Placement Warrants. Each whole warrant entitles the holder to purchase one whole Plum Class A Share for $11.50 per share. The Plum Warrants will become exercisable 30 days after the Closing and will expire five years after the Closing or earlier upon redemption or liquidation. At the Plum Amalgamation Effective Time, each Plum Warrant will be exchanged for a PubCo Warrant. Once the PubCo Warrants become exercisable, PubCo may redeem PubCo Warrants in certain circumstances. See the section entitled “Description of PubCo Securities — PubCo Warrants.”
• TRC was incorporated under the BCBCA on June 25, 2018 as DJ1 Capital Corp. On March 25, 2021, the Company changed its name to Tactical Resources Corp. The principal business of TRC is exploration and development of Rare Earth Elements (“REE”).
Please see the section entitled “Business of TRC and Certain Information About TRC” for more information.
• Plum, TRC, PubCo and Amalco entered into the Business Combination Agreement on August 22, 2024. A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A.
• Pursuant to the Business Combination Agreement, and subject to the terms and conditions contained therein, the Business Combination will be effected as follows: (i) Plum will transfer by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Companies Act and domesticate as a British Columbia corporation in accordance with the BCBCA, (ii) following the Domestication, Plum will amalgamate with PubCo, with PubCo surviving the Plum Amalgamation as PubCo and (iii) immediately following the Plum Amalgamation, TRC will amalgamate with Amalco, with the amalgamated company becoming a wholly owned subsidiary of PubCo.
• In connection with the Business Combination Agreement, Plum entered into the following agreements:
• Sponsor Support Agreement: PubCo, Plum, TRC, Mercury Capital, LLC (“Sponsor”), Alpha Partners Technology Merger Sponsor LLC (“Former Sponsor”), and certain other Plum Shareholders set forth therein (together with Sponsor and Former Sponsor, the “Sponsor Parties”) entered into a voting and support agreement on August 22, 2024 (the “Sponsor Support Agreement”) pursuant to which, among other things, (a) each of the Sponsor Parties agreed to (i) refrain from transferring any of his, her or its Plum Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (ii) vote his, her or its Plum Shares and any additional Plum Shares he, she or it acquires prior to the Plum Shareholders’ Meeting in favor of each of the Plum Shareholder Proposals at the Plum Shareholders’ Meeting, (iii) waive, and not exercise, any rights he, she or it may have to elect to effect a Plum Share Redemption in connection with the Plum Shareholders’ Approval or the Transactions and (iv) waive, and not
14
enforce, any anti-dilution rights he, she or it may have under the Plum Governing Documents in connection with the Transactions, and (b) Sponsor has agreed to use, and subject to forfeiture, the Sponsor Incentive Units as set forth therein. For more information about the Sponsor Support Agreement, see the subsection entitled “The Business Combination — Related Agreements.”
• TRC Securityholder Support Agreement: PubCo, Plum, TRC and the Key TRC Securityholders have entered into a voting and support agreement on August 22, 2024 (the “TRC Securityholder Support Agreement”) pursuant to which, among other things, each of the Key TRC Securityholders agreed to (a) refrain from transferring any of his, her or its TRC Common Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (b) vote his, her or its TRC Common Shares and any additional TRC Common Shares he, she or it acquires prior to the TRC Shareholders Meeting in favor of each of the TRC Shareholder Proposals, including the TRC Arrangement Resolution, at the TRC Shareholders Meeting and (c) waive, and not exercise, any Dissent Rights he, she or it may have with respect to the Transactions. For more information about the TRC Securityholder Support Agreement, see the subsection entitled “The Business Combination — Related Agreements.”
• Sponsor Parties Lock-up Agreement: PubCo, Plum and the Sponsor Parties have entered into a lock-up agreement (the “Sponsor Parties Lock-Up Agreement”) pursuant to which, among other things, certain PubCo Common Shares to be held by the Sponsor Parties immediately following the Closing shall be subject to certain limitations on disposition as set forth therein. For more information about the Sponsor Parties Lock-Up Agreement, see the subsection entitled “The Business Combination — Related Agreements.”
• PubCo, Plum, and TRC agreed to enter into lock-up agreements with certain TRC Shareholders at the Closing of the Business Combination on terms similar to the Sponsor Parties Lock-up Agreement. Immediately following the Closing of the Business Combination, certain PubCo Common Shares held by certain TRC Shareholders shall be subject to limitations on dispositions as set forth therein.
• Plum and the Sponsor Parties are parties to a registration rights agreement, dated as of July 27, 2021 (the “Original Registration Rights Agreement”), and, at the Closing, PubCo and the Sponsor Parties shall enter into a registration rights agreement (the “Registration Rights Agreement”) pursuant to which, among other things, (a) PubCo (as successor-in-interest to Plum) and the Sponsor Parties shall terminate the Original Registration Rights Agreement and (b) PubCo shall provide the Sponsor Parties with certain demand and piggyback registration rights with respect to the PubCo Common Shares (and any securities convertible into or exercisable for PubCo Common Shares) to be held by such Persons immediately following the Closing. For more information about the Registration Rights Agreement, see the section entitled. “The Business Combination — Related Agreements.”
• Effective as of the Plum Amalgamation Effective Time, pursuant to the terms of the Business Combination Agreement and the Plan of Arrangement, the PubCo Closing Articles will become the articles of PubCo. For more information about the PubCo Closing Articles, see the subsection entitled “The Business Combination — Related Agreements.”
• The Closing is subject to the satisfaction (or waiver) of a number of conditions set forth in the Business Combination Agreement, including, among others, the approval by Plum Shareholders of the Domestication Proposal and the Business Combination Proposal. For a summary of the conditions that must be satisfied or waived prior to completion of the Business Combination, see the subsection entitled “The Business Combination — Conditions to Closing of the Business Combination.”
• The Business Combination Agreement may be terminated, and the Business Combination may be abandoned at any time prior to the TRC Amalgamation Effective Time in specified circumstances. For more information about the termination rights under the Business Combination Agreement, see the subsection entitled “The Business Combination — Termination.”
• The Business Combination involves numerous risks. For more information about these risks, please see the section entitled “Risk Factors.”
15
• Under the Plum Articles, holders of Plum Class A Shares may elect to have their shares redeemed for cash at the applicable redemption price per share calculated in accordance with the Plum Articles. As of [•], 2025, this would have amounted to approximately $[•] per share. If a Plum Public Shareholder exercises his, her or its redemption rights, PubCo will redeem the related PubCo Common Shares for cash, and such Plum Public Shareholder will no longer own PubCo Common Shares and will not participate in PubCo’s future growth, if any. Any such redemptions related to the Business Combination will take place following the TRC Amalgamation; accordingly, it is PubCo Common Shares that will be redeemed as promptly as practicable after consummation of the Business Combination. Such a holder will be entitled to receive cash for its PubCo Common Shares only if he, she or it properly demands redemption and delivers his, her or its shares (either physically or electronically) to the Transfer Agent in accordance with the procedures described herein. For more information regarding these procedures, see the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights.”
The issuance of PubCo Common Shares in the Business Combination will dilute the equity interests of Plum Public Shareholders who do not exercise their redemption rights and may adversely affect prevailing market prices for PubCo Common Shares. Plum Public Shareholders who do not exercise their redemption rights may experience dilution to varying degrees in connection with and after the Business Combination, including:
• the issuance of PubCo Common Shares as part of the consideration in connection with the consummation of the Business Combination; and
• the exercise of TRC Warrants.
The issuance of PubCo Common Shares in connection with the Business Combination, including through any of the foregoing, could have the following effects for Plum Public Shareholders who elect not to redeem their Public Shares:
• their proportionate ownership interest in TRC will decrease;
• the amount of cash available per share, including for payment of dividends in the future, may decrease;
• the relative voting strength of each previously outstanding Plum Shares will be diminished; or
• the market price of PubCo Common Shares or TRC Warrants, as applicable, may decline.
The following table illustrates varying beneficial ownership levels in TRC, as well as possible sources and extents of dilution for non-redeeming Plum Public Shareholders, assuming no additional redemptions by Plum Public Shareholders and the Maximum Redemption by Plum Public Shareholders. The calculations are based upon an assumed TRC Exchange Ratio of 0.87084460.
Assumptions are as follows:
• Assuming no additional redemption scenario: This presentation assumes that no Public Shareholders exercise redemption rights with respect to their Public Shares in connection with the vote on the Business Combination.
• Assuming Maximum Redemption scenario: This presentation assumes that the Public Shareholders holding approximately 14.9% of the Public Shares exercise redemption rights with respect to their Public Shares. This scenario assumes that 151,833 Public Shares are redeemed for an aggregate redemption payment of approximately $1,711,089 plus a pro rata portion of interest accrued on the Trust Account (net of taxes payable).
16
|
No |
% |
Maximum |
% |
|||||||||
|
Plum Public Shareholders(1) |
|
1,016,833 |
1.3 |
% |
|
865,000 |
1.2 |
% |
||||
|
Sponsor and Former Sponsor(2)(3) |
|
6,731,320 |
8.3 |
% |
|
6,731,320 |
8.3 |
% |
||||
|
Parties to Non-redemption Agreements(3) |
|
331,180 |
0.4 |
% |
|
331,180 |
0.4 |
% |
||||
|
Plum Public Warrants(4) |
|
9,416,666 |
11.6 |
% |
|
9,416,666 |
11.6 |
% |
||||
|
Plum Founder Warrants and Private Placement Warrants(5) |
|
2,642,500 |
3.3 |
% |
|
2,642,500 |
3.3 |
% |
||||
|
Sponsor Warrants for Working Capital Note(6) |
|
969,911 |
1.2 |
% |
|
969,911 |
1.2 |
% |
||||
|
TRC public shareholders(7) |
|
35,073,456 |
43.2 |
% |
|
35,073,456 |
43.3 |
% |
||||
|
TRC option holders(8) |
|
2,085,673 |
2.6 |
% |
|
2,085,673 |
2.6 |
% |
||||
|
TRC RSUs(9) |
|
3,104,561 |
3.8 |
% |
|
3,104,561 |
3.8 |
% |
||||
|
TRC Warrantholders(10)(11) |
|
6,406,368 |
7.9 |
% |
|
6,406,368 |
7.9 |
% |
||||
|
TRC Convertible Debt(11) |
|
3,918,801 |
4.8 |
% |
|
3,918,801 |
4.8 |
% |
||||
|
Bank Shares(12) |
|
1,188,950 |
1.5 |
% |
|
1,188,950 |
1.5 |
% |
||||
|
TRC Incentive Plan(13) |
|
8,229,736 |
10.1 |
% |
|
8,214,553 |
10.1 |
% |
||||
|
Total |
|
81,115,955 |
|
|
80,948,939 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted(14) |
$ |
7.43 |
|
$ |
7.39 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted (excluding shares issued to redeemable shareholders)(15) |
$ |
7.44 |
|
$ |
7.40 |
|
||||||
____________
(1) Outstanding share numbers take into account the redemptions of 28,098,167 Plum Class A Shares that occurred in connection with extensions of Plum’s business combination deadline.
(2) On December 27, 2023, Plum, the Former Sponsor, and Sponsor entered into a purchase agreement (the “Purchase Agreement”), pursuant to which Sponsor (i) purchased 3,902,648 founder units of Plum from the Former Sponsor, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B ordinary share, which founder units are subject to forfeiture in certain circumstances, and (ii) became entitled to 70% of the 2,030,860 founder units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such founder units are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of Plum’s initial business combination. Pursuant to the Amended Purchase Agreement, the Former Sponsor shall retain 665,000 Class A private placement units and 1,128,992 Class B founder units. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(3) At Closing, 331,180 Ordinary Shares that would have otherwise been issued to the Sponsor in exchange for such number of shares Plum Class A Shares will instead to be issued to the parties to whom the Sponsor has agreed to transfer such shares. The agreement to transfer such shares was made in consideration of each of the transferees agreeing not to redeem their Plum Class A Shares on connection with the extension of Plum’s business combination deadline.
(4) The Plum Public Warrants are exercisable at $11.50 per share.
(5) The 2,354,166 Plum Founder Warrants and 288,334 Plum Private Warrants are exercisable at $11.50 per share. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(6) Assumes $1,454,867 is outstanding on the convertible note held by the Sponsor, convertible into PubCo Warrants at closing at $1.50 per Warrant.
(7) 35,674,480 TRC Common Shares are currently outstanding.
(8) 2,395,000 options to purchase TRC Common Shares are currently outstanding, exercisable at C$0.10 per share.
(9) 3,565,000 RSUs to acquire TRC Common Shares are currently outstanding, and will vest upon the closing of the Business Combination.
(10) 2,856,500 Warrants to purchase TRC Common Shares are currently outstanding, exercisable at C$2.50 per share.
(11) C$200,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,000,000 TRC Common Shares plus 2,000,000 warrants to purchase 2,000,000 TRC Common Shares at C$0.15 per share. C$500,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,500,000 TRC Common Shares plus 2,500,000 warrants to purchase 2,500,000 TRC Common Shares at C$0.20 per share. Any accrued and unpaid interest may, in TRC’s sole discretion, be paid in cash or in units (consisting of one TRC Common Share and one warrant to purchase a TRC Common Share) at a conversion price equal to the last closing market price of TRC’s common shares on the TSX-V immediately prior to such conversion date, subject to the policies of the TSX-V.
(12) TRC will be obligated to issue 1,188,950 shares to its investment bankers in connection with the Transactions.
(13) TRC’s board of directors has approved the Incentive Plan providing for the issuance of ten percent of the outstanding PubCo Common Shares, on a fully diluted basis, immediately following the closing, plus 1,000,000 shares.
17
(14) Calculation of implied per share value assumes an enterprise value of $602.5 million of PubCo upon consummation of the Business Combination and a fully diluted share count with no redemptions of 81,115,955.
(15) Calculation of implied per share value assumes an enterprise value of $599.2 million of PubCo upon consummation of the Business Combination and a fully diluted share count with max redemptions of 80,948,939.
Assuming no further redemptions of the Plum Shares, the combined company would have a pro forma valuation of approximately $811,159,550 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Assuming maximum redemptions of the Plum Shares issued in our IPO, the combined company would have a pro forma valuation of approximately $809,489,390 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Please see the subsections entitled “Summary of the Proxy Statement/Prospectus — Ownership of PubCo After the Closing,” and “The Business Combination — Total PubCo Shares to Be Issued in the Business Combination” and the section entitled “Unaudited Pro Forma Condensed Consolidated Financial Information” for more information.
• The Plum Board considered various factors in determining whether to approve the Business Combination Agreement and the Business Combination. For more information about the Plum Board’s decision-making process, see the subsection entitled “The Business Combination — Plum Board’s Reasons for Approving the Business Combination.” When you consider the unanimous recommendation of the Plum Board, you should keep in mind that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, your interests as a shareholder. Please see the subsection entitled “The Business Combination — Interests of Certain Persons in the Business Combination.”
• In addition to voting on the proposal to adopt and approve the Business Combination Agreement and approve the transactions contemplated thereby, including the Business Combination, at the Plum Shareholders’ Meeting, the Plum Shareholders will also be asked to consider and vote on the approval of:
• a proposal to approve, by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and the Companies Act and the Domestication of Plum as a British Columbia corporation in accordance with the applicable provisions of the BCBCA, including the adoption of the Domestication Articles;
• a proposal to approve on a non-binding advisory basis, by Ordinary Resolution, the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately as the Authorized Capital Proposal, the Quorum Proposal and the Other Matters Proposal in accordance with SEC guidance. The full text of the PubCo Closing Articles are attached to this proxy statement/prospectus as Annex E;
• If put to Plum Shareholders for a vote, a proposal to approve by Ordinary Resolution the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the foregoing Proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals. If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
For more information, see the sections entitled “Proposal No. 1 — The Domestication Proposal,” “Proposal No. 2 — The Business Combination Proposal,” “Proposal No. 3 — The Advisory Organizational Documents Proposals,” “Proposal No. 4 — The Incentive Plan Proposal,” and “Proposal No. 5 — The Adjournment Proposal.”
18
Restrictions on Sale of Securities Held by the Sponsor and its Affiliates
Pursuant to the Letter Agreement, dated July 27, 2021, by and among Plum, the Former Sponsor, the Sponsor, and the holders of Founder Units; the Lock-Up Agreement, dated August 22, 2024, by and among the Sponsor, the Former Sponsor, Plum and PubCo; and the Purchase Agreement by and between the Sponsor and the Former Sponsor, each of the directors and officers has agreed to restrictions on its ability to transfer, assign, or sell the Founder Units and Private Placement Units, as summarized in the table below.
|
Subject Securities |
Expiration Date |
Natural Persons and |
Exceptions to Transfer Restrictions |
|||
|
Founder Units |
1. Under the Letter Agreement, transfer of any of their founder shares shall not occur until the earliest of (A) one year after the completion of the Plum’s initial Business Combination and (B) subsequent to the Business Combination, (x) if the closing price of the Class A Ordinary Shares equals or exceeds $12.00 per share (as adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like) for any 20 trading days within any 30-trading day period commencing at least 150 days after the Plum’s initial Business Combination or (y) the date on which the Plum completes a liquidation, merger, amalgamation, capital stock exchange, reorganization or other similar transaction that results in all of the Company’s Public Shareholders having the right to exchange their shares of Class A Ordinary Shares for cash, securities or other property. 2. Under the Lock-Up Agreement, no transfer of any Class B Ordinary Shares (or any of the Company’s Class A Ordinary Shares issuable upon conversion thereof, or any securities into which Class B Ordinary Shares or Class A Ordinary Shares are converted or exchangeable pursuant to the Business Combination) until the date that is the day immediately following the six-month anniversary of the completion of the Business Combination. 3. Under the Purchase Agreement, no sale or otherwise dispose of any of the Founder Units. |
Sponsor Kanishka Roy Steven Handwerker David Sable Alan Black Hume Kyle Former Sponsor |
1. Under both the Lock-Up Agreement and Letter Agreement, transfers of the Founder Units, Private Placement Units and the Class A Ordinary Shares underlying the private placement warrants that are held by the Sponsors, affiliates of the Sponsors, any Insider or any of their permitted transferees, are permitted (i) to the Company’s officers or directors, any affiliate or family member of any of the Company’s officers or directors, any affiliate of the Sponsors or to any members of the Sponsors or any of their affiliates; (ii) in the case of an individual, by gift to a member of such individual’s immediate family or to a trust, the beneficiary of which is a member of such individual’s immediate family, an affiliate of such individual or to a charitable organization; (iii) in the case of an individual, by virtue of laws of descent and distribution upon death of such individual; (iv) in the case of an individual, pursuant to a qualified domestic relations order; (v) by private sales or transfers made in connection with any forward purchase agreement or similar arrangement or in connection with the consummation of the Business Combination at prices no greater than the price at which the securities were originally purchased; (vi) in the event of the Company’s liquidation prior to the completion of the Business Combination; (vii) by virtue of the laws of the Cayman Islands or the Sponsors’ respective limited liability company agreement upon dissolution of such Sponsor; or (viii) in the event of the Company’s liquidation, merger, capital stock exchange or other similar transaction which results in all of the Company’s shareholders having the right to exchange their Class A Ordinary Shares for cash, securities or other property subsequent to the Company’s completion of the Business Combination; provided, however, that in the case of clauses (i) through (v) or (vii), these permitted transferees must enter into a written agreement with the Company agreeing to be bound by the transfer restrictions herein and the other restrictions contained in this Agreement (including provisions relating to voting, the Trust Account and liquidating distributions). 2. Under the Lock-Up Agreement, following the consummation of the Business Combination, (i) if a Stock Price Level equal to or greater than $15.00 (as adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like) is achieved, the Lock-Up Restriction shall expire with respect to one-third of the shares held by each such person, (ii) if a Stock Price Level equal to or greater |
19
|
Subject Securities |
Expiration Date |
Natural Persons and |
Exceptions to Transfer Restrictions |
|||
|
than $20.00 (as adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like) is achieved, the Lock-Up Restriction shall expire with respect to an additional one-third of the shares held by each such person, and (iii) if a Stock Price Level equal to or greater than $25.00 (as adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like) is achieved, the transfer restriction shall expire with respect to the last one-third of the shares held by each such person; and provided, further, that, subsequent to the Business Combination, the transfer restriction shall expire with respect to all shares held by each such person on the date on which the Company (or the ultimate parent company of which the Company becomes a direct or indirect wholly owned subsidiary pursuant to the Business Combination) completes a liquidation, merger, amalgamation, capital stock exchange, reorganization or other similar transaction that results in all of the Plum’s Public Shareholders (or the public shareholders of the ultimate parent company of which the Plum becomes a direct or indirect wholly owned subsidiary pursuant to the Business Combination) having the right to exchange their Class A Ordinary Shares (or any securities into which Class A Ordinary Shares are converted or exchangeable pursuant to the Business Combination) for cash, securities or other property, other than any such transaction which does not result in a person or group (as defined in Section 13(d) of the Securities Exchange Act of 1934, as amended) of persons (other than the Company (or the ultimate parent company of which the Company becomes a direct or indirect wholly owned subsidiary pursuant to the Business Combination) or any of its subsidiaries) becoming the beneficial owner (as defined in Rule 13d-3 under the Exchange Act) or otherwise acquiring control, directly or indirectly, of more than 50% of (A) the consolidated assets of the Company (or the ultimate parent company of which the Company becomes a direct or indirect wholly owned subsidiary pursuant to the Business Combination) and its subsidiaries or (B) the total voting power of the |
||||||
|
equity securities of the Company (or the ultimate parent company of which the Company becomes a direct or indirect wholly owned subsidiary pursuant to the Business Combination). For purposes hereof: (x) “Stock Price Level” means the daily volume weighted average closing sale price per share of the Class A Ordinary Shares (or any securities into which Class A Ordinary Shares are converted or exchangeable pursuant to the Business Combination) as quoted on Nasdaq (or such other principal securities exchange or securities market on which such shares are then traded) for any 20 Trading Days within any 30 consecutive Trading Day period; and (y) “Trading Day” means any day on which the Class A Ordinary Shares (or any securities into which Class A Ordinary Shares are converted or exchangeable pursuant to the Business Combination) are actually traded on the |
20
|
Subject Securities |
Expiration Date |
Natural Persons and |
Exceptions to Transfer Restrictions |
|||
|
principal securities exchange or securities market on which the Class A Ordinary Shares (or any securities into which Class A Ordinary Shares are converted or exchangeable pursuant to the Business Combination) are then traded. |
||||||
|
3. Under the Purchase Agreement, transfer is permitted in compliance with the registration requirements or exemption provisions of the Securities Act and any applicable U.S. state securities laws and in accordance with any limitations set forth in any agreements described in the Prospectus dated July 29, 2021 relating to the initial public offering of Plum. |
||||||
|
Private Placement Units |
30-days after the closing of the Business Combination |
Sponsor Former Sponsor |
Under both the Lock-Up Agreement and Letter Agreement, transfers of the Founder Units, Private Placement Units and the Class A Ordinary Shares underlying the private placement warrants that are held by the Sponsors, affiliates of the Sponsors, any Insider or any of their permitted transferees (that have complied with this paragraph 2(c)), are permitted (i) to the Company’s officers or directors, any affiliate or family member of any of the Company’s officers or directors, any affiliate of the Sponsors or to any members of the Sponsors or any of their affiliates; (ii) in the case of an individual, by gift to a member of such individual’s immediate family or to a trust, the beneficiary of which is a member of such individual’s immediate family, an affiliate of such individual or to a charitable organization; (iii) in the case of an individual, by virtue of laws of descent and distribution upon death of such individual; (iv) in the case of an individual, pursuant to a qualified domestic relations order; (v) by private sales or transfers made in connection with any forward purchase agreement or similar arrangement or in connection with the consummation of the Business Combination at prices no greater than the price at which the securities were originally purchased; (vi) in the event of the Company’s liquidation prior to the completion of the Business Combination; (vii) by virtue of the laws of the Cayman Islands or the Sponsors’ respective limited liability company agreement upon dissolution of such Sponsor; or (viii) in the event of the Company’s liquidation, merger, capital stock exchange or other similar transaction which results in all of the Company’s shareholders having the right to exchange their Class A Ordinary Shares for cash, securities or other property subsequent to the Company’s completion of the Business Combination; provided, however, that in the case of clauses (i) through (v) or (vii), these permitted transferees must enter into a written agreement with the Company agreeing to be bound by the transfer restrictions herein and the other restrictions contained in this Agreement (including provisions relating to voting, the Trust Account and liquidating distributions). |
21
QUESTIONS AND ANSWERS ABOUT THE Plum SHAREHOLDERS’ MEETING AND
THE BUSINESS COMBINATION
The following questions and answers briefly address some commonly asked questions about the Proposals to be presented at the Plum Shareholders’ Meeting, as well as the proposed Business Combination. The following questions and answers do not include all of the information that is important to Plum Shareholders. Plum urges Plum Shareholders to carefully read this entire proxy statement/prospectus, including the annexes and other documents referred to herein.
Q: Why am I receiving this proxy statement/prospectus?
A: Plum Shareholders are being asked to consider and vote upon the Proposals, including to approve the transactions contemplated by the Business Combination Agreement, including the Plum Amalgamation and the TRC Amalgamation.
A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A. This proxy statement/prospectus and its annexes contain important information about the proposed Business Combination and the other matters to be acted upon at the Plum Shareholders’ Meeting. You should read this proxy statement/prospectus and its annexes carefully and in their entirety.
Your vote is important. You are encouraged to submit your proxy as soon as possible after carefully reviewing this proxy statement/prospectus and its annexes.
Q: What is being voted on at the Plum Shareholders’ Meeting?
A: Plum Shareholders will vote on the following Proposals at the Plum Shareholders’ Meeting:
• The Domestication Proposal — To approve, by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and Cayman Islands Companies Act (As Revised) (the “Companies Act”) and the domestication of Plum (the “Domestication”) as a British Columbia corporation in accordance with the applicable provisions of the Business Corporations Act (British Columbia) (the “BCBCA”), including the adoption of the Domestication Articles (the “Domestication Proposal” or “Proposal No. 1”);
• Business Combination Proposal — To approve, by Ordinary Resolution, the Business Combination Agreement, dated as of August 22, 2024 (as may be amended, supplemented or otherwise modified from time to time, the “Business Combination Agreement” and the transactions contemplated thereby, collectively, the “Business Combination”) by Plum, Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum (“Amalco”), Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia (“PubCo”), and Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia (“TRC”), including the Arrangement Resolution pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement attached hereto as Annex B, (i) Plum shall effect the Domestication, (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation (the “Business Combination Proposal” or “Proposal No. 2”). A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A.
22
• The Advisory Organizational Documents Proposals — proposals to approve on a non-binding advisory basis, by Ordinary Resolution, the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately in accordance with U.S. Securities and Exchange Commission guidance (the “Advisory Organizational Documents Proposals” or “Proposal No. 3”). The full text of the PubCo Closing Articles are attached to the accompanying proxy statement/prospectus as Annex E. Proposal No. 3 is separated into sub-proposals submitted to Plum Shareholders to approve on a non-binding advisory basis, by Ordinary Resolution, those governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights as described in the following paragraphs (a) — (d):
(a) the proposed PubCo Closing Articles would change the authorized share capital from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal or par value of $0.0001 each, to an unlimited number of PubCo Common Shares (the “Authorized Capital Proposal” or “Proposal No. 3A”);
(b) the proposed PubCo Closing Articles would reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting (the “Quorum Proposal” or “Proposal No. 3B”);
(c) the proposed PubCo Closing Articles would change the name of the company from “Plum III Merger Corp.” to “Tactical Resources Corporation” (the “Name Change Proposal” or “Proposal No. 3C”); and
(d) the proposed PubCo Closing Articles would not include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters (the “Other Matters Proposal” or “Proposal No. 3D” and, together with the Authorized Capital Proposal, the Quorum Proposal and the Name Change Proposal, the “Sub-Proposals”);
• Incentive Plan Proposal — To approve, by Ordinary Resolution, for the purposes of complying with the rules of the Nasdaq Stock Market, the issuance of PubCo Common Shares pursuant to the PubCo Omnibus Equity Incentive Plan (the “Incentive Plan Proposal” or “Proposal No. 4”). A copy of the Incentive Plan is attached to this proxy statement/prospectus as Annex K;
• Adjournment Proposal — if put to Plum Shareholders for a vote, a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the foregoing proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals (the “Adjournment Proposal” or “Proposal No. 5” and, together with the Domestication Proposal, the Business Combination Proposal, the Incentive Plan Proposal and the Advisory Organizational Documents Proposals, the “Proposals”). If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Q: Are the Proposals conditioned on one another?
A: Plum may not consummate the Business Combination unless the Domestication Proposal and the Business Combination Proposal are approved at the Plum Shareholders’ Meeting. The Advisory Organizational Documents Proposals are non-binding and are not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. The Incentive Plan Proposal is not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. The Adjournment Proposal is not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. If put forth at the Plum
23
Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Q: What will happen in the Business Combination?
A: Pursuant to the Business Combination Agreement, and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement, the Business Combination will be effected as follows: (i) Plum will transfer by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and the Companies Act and domesticate as a British Columbia corporation in accordance with the BCBCA, (ii) Plum will amalgamate with PubCo, with PubCo surviving as PubCo in accordance with the terms of the Plan of Arrangement and (iii) TRC will amalgamate with Amalco, with the amalgamated company becoming a wholly owned subsidiary of PubCo in accordance with the terms of the Plan of Arrangement.
The Domestication will occur at most one business day prior to, and independent of, the Plum Amalgamation and the TRC Amalgamation, which will occur on the Closing Date.
Following the Business Combination, PubCo will be a public company and is expected to be listed on the NASDAQ. PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of the NASDAQ in accordance with its original listing requirements. There is no assurance that the NASDAQ will approve PubCo’s listing applications. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of the NASDAQ. For more information about the Business Combination Agreement and the Business Combination, please see the section entitled “The Business Combination.” Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX-V, and TRC will apply to have TRC cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
Q: How was the transaction structure for the Business Combination determined?
The Business Combination was the result of an extensive search for a potential transaction utilizing the network and investing and operating experience of Plum’s management team as well as the Plum Board. The transaction structure for the Business Combination and domestication to British Columbia, Canada was determined through the advice of legal counsel and tax advisors, the fact that TRC is a British Columbia corporation and the discretion of the parties to the Business Combination. The Plum Board believes that there are significant advantages to us that will arise as a result of the transaction structure and a change of our domicile to British Columbia, including but not limited to tax efficiency. Further, the Plum Board believes the transaction structure and domestication to British Columbia are in the best interests of Plum and its shareholders.
Q: Why is Plum proposing the Business Combination?
A: Plum was formed for the purpose of effecting a merger, amalgamation, share exchange, asset acquisition, share purchase, reorganization, or similar business combination involving Plum and one or more businesses or entities. The Plum Board considered a wide variety of factors in connection with its evaluation of the Business Combination, as well as the Plum Board’s review of the results of the due diligence conducted by Plum management and Plum’s advisors. As a result, the Plum Board concluded that a transaction with TRC would present the most attractive opportunity to maximize value for Plum Shareholders. Please see the subsection entitled “The Business Combination — The Plum Board’s Reasons for the Approval of the Business Combination.” Shareholder approval of the Business Combination is required by the Business Combination Agreement, Plum’s Articles and Nasdaq Listing Rules 5635(d).
Q: Why is TRC proposing the Business Combination?
A: The TRC Board considered a wide variety of factors in connection with its evaluation of the Business Combination. The TRC Board concluded that a transaction with Plum would result in a fund-raising transaction in which the Company’s shares would be listed on the Nasdaq, and should result in an increase in value for TRC. Please see the subsection entitled “The Business Combination — The TRC Board’s Reasons for the Approval of the Business Combination.” Shareholder approval of the Business Combination is required by the Business Combination Agreement and TRC’s Articles.
24
Q: What conditions must be satisfied to complete the Business Combination?
A: There are several closing conditions in the Business Combination Agreement, including the approval by Plum Shareholders of the Business Combination Proposal. For a summary of the conditions that must be satisfied or waived prior to completion of the Business Combination, please see the subsection entitled “The Business Combination — Conditions to Closing of the Business Combination.”
Q: How will PubCo be managed and governed following the Business Combination?
Upon consummation of the Business Combination, PubCo will be governed by the PubCo Closing Articles, which will be substantially in the form set forth in Annex E to this proxy statement/prospectus. The PubCo Board will be responsible for guiding PubCo’s business and affairs and overseeing management. PubCo’s management team will be derived from TRC’s existing employees and members of management, who will be responsible for the execution of the combined business’s strategy. Please see the section entitled “Management of PubCo After the Business Combination” for more information.
Q: What equity stake will current TRC shareholders and current Plum shareholders hold in PubCo immediately after the completion of the Business Combination, and what effect will potential sources of dilution have on such equity stake after the Closing?
A: The issuance of PubCo Common Shares in the Business Combination will dilute the equity interests of Plum Public Shareholders who do not exercise their redemption rights and may adversely affect prevailing market prices for PubCo Common Shares. Plum Public Shareholders who do not exercise their redemption rights may experience dilution to varying degrees in connection with and after the Business Combination, including:
• the issuance of PubCo Common Shares as part of the consideration in connection with the consummation of the Business Combination; and
• the exercise of TRC Warrants.
The issuance of PubCo Common Shares in connection with the Business Combination, including through any of the foregoing, could have the following effects for Plum Public Shareholders who elect not to redeem their Public Shares:
• their proportionate ownership interest in TRC will decrease;
• the amount of cash available per share, including for payment of dividends in the future, may decrease;
• the relative voting strength of each previously outstanding Plum Shares will be diminished; or
• the market price of PubCo Common Shares or TRC Warrants, as applicable, may decline.
The following table illustrates varying beneficial ownership levels in TRC, as well as possible sources and extents of dilution for non-redeeming Plum Public Shareholders, assuming no additional redemptions by Plum Public Shareholders and the Maximum Redemption by Plum Public Shareholders. The calculations are based upon an assumed TRC Exchange Ratio of 0.87084460.
Assumptions are as follows:
• Assuming no additional redemption scenario: This presentation assumes that no Public Shareholders exercise redemption rights with respect to their Public Shares in connection with the vote on the Business Combination.
• Assuming Maximum Redemption scenario: This presentation assumes that the Public Shareholders holding approximately 14.9% of the Public Shares exercise redemption rights with respect to their Public Shares. This scenario assumes that 151,833 Public Shares are redeemed for an aggregate redemption payment of approximately $1,711,089 plus a pro rata portion of interest accrued on the Trust Account (net of taxes payable).
25
|
No |
% |
Maximum |
% |
|||||||||
|
Plum Public Shareholders(1) |
|
1,016,833 |
1.3 |
% |
|
865,000 |
1.2 |
% |
||||
|
Sponsor and Former Sponsor(2)(3) |
|
6,731,320 |
8.3 |
% |
|
6,731,320 |
8.3 |
% |
||||
|
Parties to Non-redemption Agreements(3) |
|
331,180 |
0.4 |
% |
|
331,180 |
0.4 |
% |
||||
|
Plum Public Warrants(4) |
|
9,416,666 |
11.6 |
% |
|
9,416,666 |
11.6 |
% |
||||
|
Plum Founder Warrants and Private Placement Warrants(5) |
|
2,642,500 |
3.3 |
% |
|
2,642,500 |
3.3 |
% |
||||
|
Sponsor Warrants for Working Capital Note(6) |
|
969,911 |
1.2 |
% |
|
969,911 |
1.2 |
% |
||||
|
TRC public shareholders(7) |
|
35,073,456 |
43.2 |
% |
|
35,073,456 |
43.3 |
% |
||||
|
TRC option holders(8) |
|
2,085,673 |
2.6 |
% |
|
2,085,673 |
2.6 |
% |
||||
|
TRC RSUs(9) |
|
3,104,561 |
3.8 |
% |
|
3,104,561 |
3.8 |
% |
||||
|
TRC Warrantholders(10)(11) |
|
6,406,368 |
7.9 |
% |
|
6,406,368 |
7.9 |
% |
||||
|
TRC Convertible Debt(11) |
|
3,918,801 |
4.8 |
% |
|
3,918,801 |
4.8 |
% |
||||
|
Bank Shares(12) |
|
1,188,950 |
1.5 |
% |
|
1,188,950 |
1.5 |
% |
||||
|
TRC Incentive Plan(13) |
|
8,229,736 |
10.1 |
% |
|
8,214,553 |
10.1 |
% |
||||
|
Total |
|
81,115,955 |
|
|
80,948,939 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted(14) |
$ |
7.43 |
|
$ |
7.39 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted (excluding shares issued to redeemable shareholders)(15) |
$ |
7.44 |
|
$ |
7.40 |
|
||||||
____________
(1) Outstanding share numbers take into account the redemptions of 28,098,167 Plum Class A Shares that occurred in connection with extensions of Plum’s business combination deadline.
(2) On December 27, 2023, Plum, the Former Sponsor, and Sponsor entered into a purchase agreement (the “Purchase Agreement”), pursuant to which Sponsor (i) purchased 3,902,648 founder units of Plum from the Former Sponsor, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B ordinary share, which founder units are subject to forfeiture in certain circumstances, and (ii) became entitled to 70% of the 2,030,860 founder units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such founder units are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of Plum’s initial business combination. Pursuant to the Amended Purchase Agreement, the Former Sponsor shall retain 665,000 Class A private placement units and 1,128,992 Class B founder units. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(3) At Closing, 331,180 Ordinary Shares that would have otherwise been issued to the Sponsor in exchange for such number of shares Plum Class A Shares will instead to be issued to the parties to whom the Sponsor has agreed to transfer such shares. The agreement to transfer such shares was made in consideration of each of the transferees agreeing not to redeem their Plum Class A Shares on connection with the extension of Plum’s business combination deadline.
(4) The Plum Public Warrants are exercisable at $11.50 per share.
(5) The 2,354,166 Plum Founder Warrants and 288,334 Plum Private Warrants are exercisable at $11.50 per share. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(6) Assumes $1,454,867 is outstanding on the convertible note held by the Sponsor, convertible into PubCo Warrants at closing at $1.50 per Warrant.
(7) 35,674,480 TRC Common Shares are currently outstanding.
(8) 2,395,000 options to purchase TRC Common Shares are currently outstanding, exercisable at C$0.10 per share.
(9) 3,565,000 RSUs to acquire TRC Common Shares are currently outstanding, and will vest upon the closing of the Business Combination.
(10) 2,856,500 Warrants to purchase TRC Common Shares are currently outstanding, exercisable at C$2.50 per share.
(11) C$200,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,000,000 TRC Common Shares plus 2,000,000 warrants to purchase 2,000,000 TRC Common Shares at C$0.15 per share. C$500,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,500,000 TRC Common Shares plus 2,500,000 warrants to purchase 2,500,000 TRC Common Shares at C$0.20 per share. Any accrued and unpaid interest may, in TRC’s sole discretion, be paid in cash or in units (consisting of one TRC Common Share and one warrant to purchase a TRC Common Share) at a conversion price equal to the last closing market price of TRC’s common shares on the TSX-V immediately prior to such conversion date, subject to the policies of the TSX-V.
(12) TRC will be obligated to issue 1,188,950 shares to its investment bankers in connection with the Transactions.
(13) TRC’s board of directors has approved the Incentive Plan providing for the issuance of ten percent of the outstanding PubCo Common Shares, on a fully diluted basis, immediately following the closing, plus 1,000,000 shares.
26
(14) Calculation of implied per share value assumes an enterprise value of $602.5 million of PubCo upon consummation of the Business Combination and a fully diluted share count with no redemptions of 81,115,955.
(15) Calculation of implied per share value assumes an enterprise value of $599.2 million of PubCo upon consummation of the Business Combination and a fully diluted share count with max redemptions of 80,948,939.
Assuming no further redemptions of the Plum Shares, the combined company would have a pro forma valuation of approximately $811,159,550 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Assuming maximum redemptions of the Plum Shares issued in our IPO, the combined company would have a pro forma valuation of approximately $809,489,390 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Q: Will the Sponsor receive compensation in connection with the Business Combination?
A: No. The Sponsor will not receive any direct compensation for services rendered or to be rendered in the consummation of the Business Combination. The Sponsor holds Founder Units that were purchased from the Former Sponsor that will convert into common stock and warrants of PubCo at Closing. The Sponsor will be reimbursed for working capital expenses from Plum loaned pursuant to the Working Capital Loan with an outstanding balance of approximately $1,554,867. Such outstanding balance may convert, at Plum’s election, into warrants at a price of $1.50 per warrant.
Q: Who are the Sponsor and Sponsor Affiliates?
A: Mercury Capital LLC, a Delaware limited liability company, which we refer to in this proxy statement/prospectus as the “Sponsor,” was formed prior to Sponsor purchasing Founder Units and taking control of Plum from the Former Sponsor. Other than its investment in Plum and its work on behalf of Plum, the Sponsor is not engaged in any business. The Sponsor is controlled by Mr. Kanishka Roy, its sole manager and member. Other than Mr. Roy, Mr. Steven Handwerker and the Former Sponsor, Alpha Partners Technology Merger Sponsor, LLC, who we refer to in this proxy statement/prospectus as the “Sponsor Affiliates,” no other person has a direct or indirect material interest in the Sponsor. The Sponsor and Sponsor Affiliates also provide working capital and advance funds used for transaction expenses to Plum from time to time. The Sponsor provides administrative, financial and support services to Plum, for which it receives no compensation for such services. Mr. Roy serves as Chief Executive Officer and Chairman of the Board and his material roles and responsibilities, as provided by the Third Amended and Restated Memorandum and Articles of Association, include, calling, adjourning, and chairing an extraordinary meeting, proposing amendments to the organization documents of Plum, and together with other directors, managing the business of Plum and delegating such management power to authorized officers. Mr. Handwerker serves as Chief Financial Officer. His material roles and responsibilities are overseeing Plum’s finances, securities filings, and business operations. Mr. Roy and Mr. Handwerker’s responsibilities also include sourcing potential targets, negotiating definitive agreements, raising capital, and overall strategic guidance.
Mr. Roy and Mr. Handwerker each have prior experience with SPACs and may continue sponsoring, investing or otherwise becoming involved with other SPACs and de-SPAC transactions prior to Plum completing the Business Combination. Mr. Roy and Mr. Handwerker both serve as officers and directors of Plum Acquisition Corp. IV, which consummated its initial public offering on January 16, 2025.
Q: Why is Plum proposing the Advisory Organizational Documents Proposals?
A: As required by applicable SEC guidance, Plum is requesting that the Plum Shareholders consider and vote upon, on a non-binding advisory basis, proposals to approve the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights. These non-binding advisory votes are not otherwise required by either Cayman Islands or British Columbia law and are separate and apart from the Business Combination Proposal, but consistent with SEC guidance, Plum is submitting these proposals to its shareholders separately as the Sub-Proposals for approval. Please see the section entitled “Comparison of Corporate Governance and Shareholder Rights” elsewhere in this proxy statement/prospectus for additional information. However, the Plum Shareholder votes regarding these Proposals are advisory votes and are not binding on the Plum Board. Furthermore, the Business Combination is not conditioned on the separate approval of the Advisory Organizational Documents Proposals.
27
The full text of the PubCo Closing Articles are attached to this proxy statement/prospectus as Annex E. Please see the section entitled “Proposal No. 3 — the Advisory Organizational Documents Proposals” for additional information.
Q: Did the Plum Board obtain a third-party valuation or fairness opinion in determining whether or not to proceed with the Business Combination?
A: No. The Plum Board did not obtain a third-party valuation or fairness opinion in connection with its determination to approve the Business Combination and recommend that Plum Shareholders vote to approve the Business Combination. Rather, because the officers and directors of Plum have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries, the Plum Board concluded that their collective experience, together with the experience and sector expertise of Plum’s financial advisors, enabled them to make the necessary analyses to determine that the Business Combination was fair from a financial perspective to the Plum Shareholders. In analyzing the Business Combination, Plum’s management conducted significant due diligence on TRC and the industry in which it operates. For a complete discussion of the due diligence conducted by Plum, and the factors utilized by the Plum Board in approving the Business Combination, see the sections entitled, “The Business Combination — Background of the Business Combination” and “The Business Combination — The Plum Board’s Reasons for the Approval of the Business Combination.” The Plum Board also determined, without seeking a third party valuation, that TRC’s fair market value was at least 80% of Plum’s net assets, excluding any taxes payable on interest earned. Plum is not required to, and has not, obtained a third-party valuation that the consideration it is paying for TRC in the Business Combination is fair to Plum Shareholders from a financial point of view. Accordingly, the Plum Shareholders will be relying solely on the judgment of the Plum Board as described above in determining the value of TRC, and assuming the risk that the Plum Board may not have properly valued such business.
Q: What are some of the positive and negative factors that the Plum Board considered when determining to enter into the Business Combination Agreement and their rationale for approving the Business Combination?
A: The Plum Board considered a number of factors pertaining to the Business Combination as generally supporting their respective decisions to enter into the Business Combination Agreement and the transactions contemplated thereby, including but not limited to, the following material factors:
• Benefits from Public Market Entry and Plum Expertise. The Plum Board considered the fact that, given the expected capital raise from private and public investments as part of the Business Combination, among other things, the cash that post-combination TRC is expected to have will allow it to be well-positioned to scale and fund its business plan.
• Shareholder Liquidity. The Plum Board considered the fact that, pursuant to the Business Combination Agreement, the Plum Shares issued as merger consideration will be listed on the Nasdaq, a major U.S. stock exchange, which the Plum Board believes has the potential to offer shareholders enhanced liquidity.
• Other Alternatives. The Plum Board has determined that, after a thorough review of other business combination opportunities reasonably available to Plum, the proposed Business Combination represents the best potential business combination for Plum and the most attractive opportunity for Plum based upon the process utilized to evaluate and assess other potential acquisition targets. The Plum Board has also determined that such process has not presented a better alternative.
• Negotiated Transaction. The Plum Board has determined that the financial and other terms of the Business Combination Agreement are reasonable and were the product of arm’s-length negotiations between Plum and TRC.
The Plum Board also considered various uncertainties and risks and other potentially negative factors concerning the Business Combination, including, but not limited to, the following:
• Exclusivity. The fact that the Business Combination Agreement includes an exclusivity provision that prohibits Plum from soliciting other business combination proposals, which restricts Plum’s ability, so long as the Business Combination Agreement is in effect, to consider other potential business combinations.
28
• Macroeconomic Risks. Macroeconomic uncertainty, including the impacts of rising interest rates and inflation, regulatory policy, supply chain issues and the continuing impact of the COVID-19 pandemic and the effects any of the foregoing could have on TRC’s revenues and the trading price of New Plum Common Stock.
• Business Plan May Not Be Achieved. The risk that TRC may not be able to execute on its business plan.
• Risks Associated with TRC’s Business. Risks relating to TRC’s business, including the demand, emerging use cases, market prices, and uncertainties in TRC’s estimates of rare earth elements, TRC’s ability to extract rare earth elements, and the other risk factors related to TRC set forth in this proxy statement/prospectus under the headings “Risk Factors — Risks Related to Our Business, Industry and Technology.”
• Redemption Risk. The risk that a significant number of Plum’s Public Shareholders may redeem their Public Shares for cash prior to the consummation of the Business Combination, thereby reducing the amount of cash available to TRC following the consummation of the Business Combination and making the Business Combination more difficult to complete.
• Evolving Regulatory Regime Governing Special Purpose Acquisition Companies. The risk that regulation of special purpose acquisition companies continues to evolve and the SEC, Nasdaq and other regulators may revisit and update their laws, regulations and policies.
• Shareholder Vote. The risk that Plum’s shareholders may object to the Business Combination and take action that may prevent or delay the consummation of the Business Combination, including failing to provide the requisite votes necessary to effect the Business Combination.
• Closing Conditions. The fact that the completion of the Business Combination is conditioned on the satisfaction of certain closing conditions that are not within Plum’s control.
• Litigation. The possibility of litigation challenging the Business Combination or an adverse judgment granting permanent injunctive relief that could indefinitely delay or enjoin consummation of the Business Combination.
• Benefits May Not Be Achieved. The risks that the potential benefits of the Business Combination may not be fully achieved or may not be achieved within the expected timeframe.
• Liquidation of Plum. The risks and costs to Plum if the Business Combination is not completed, including the risk of diverting Plum management’s focus and resources from other business combination opportunities, which could result in Plum being unable to effect a business combination and force Plum to liquidate.
• Growth Initiatives May Not be Achieved. The risk that TRC’s growth initiatives may not be fully achieved or may not be achieved within the expected timeframe.
• Plum Shareholders Receiving a Minority Position. The fact that Plum shareholders will own a minority of the voting and economic rights of New Plum following the consummation of the Business Combination.
• No Third Party Valuation. The risk that Plum did not obtain any third party report, opinion or appraisal in determining the valuation of TRC, or obtain a fairness opinion in determining whether or not to proceed with the Business Combination, because it relied on the financial skills and background of its officers and directors, and the possibility that the Plum Board may have been incorrect in its assessment of the Business Combination, including because it did not obtain any third party report, opinion or appraisal in establishing a valuation for TRC.
• Fees and Expenses. The fees and expenses associated with completing the Business Combination.
• Other Risk Factors. Various other risk factors associated with the business of TRC and the Business Combination as described in the section entitled “Risk Factors” appearing elsewhere in this proxy statement/prospectus.
29
The Plum Board concluded that the potential benefits that they expected Plum and Plum Shareholders to achieve as a result of the Business Combination outweighed the potential negative factors associated with the Business Combination. Accordingly, the Plum Board unanimously determined that the Business Combination Agreement and the Business Combination were advisable, fair to, and in the best interests of, Plum and Plum Shareholders.
For more information about the Plum Board’s decision-making process, see the subsection entitled “The Business Combination — Plum Boards Reasons for Approving the Business Combination.”
Q: What happens if I sell my Plum Class A Shares before the Plum Shareholders’ Meeting?
A: The record date for the Plum Shareholders’ Meeting is earlier than the date of the Plum Shareholders’ Meeting and the date that the Business Combination is expected to be completed. If you transfer your Plum Class A Shares after the record date, but before the Plum Shareholders’ Meeting, unless the transferee obtains from you a proxy to vote those shares, you will retain your right to vote at the Plum Shareholders’ Meeting. However, you will not be able to seek redemption of your PubCo Common Shares that you receive in exchange for your Plum Class A Shares because you will no longer be able to deliver them for cancellation upon consummation of the Business Combination in accordance with the provisions described in this proxy statement/prospectus. If you transfer your Plum Class A Shares prior to the record date, you will have no right to vote those shares at the Plum Shareholders’ Meeting or seek redemption of your PubCo Common Shares that you receive in exchange for your Plum Class A Shares.
Q: How has the announcement of the Business Combination affected the trading price of Plum Units, Plum Class A Shares and Plum Public Warrants?
A: On August 22, 2024, the last trading date before the public announcement of the Business Combination, Plum Units, Plum Class A Shares and Plum Public Warrants closed at $11.40, $10.84 and $0.077, respectively. On [•], 2025, the trading date that is three business days prior to the date of this proxy statement/prospectus, Plum Units, Plum Class A Shares and Plum Public Warrants closed at $[•], $[•] and $[•], respectively.
Q: Following the Business Combination, will Plum’s securities continue to trade on a stock exchange?
A: No. Plum, TRC and PubCo anticipate that, following consummation of the Business Combination, the Plum Class A Shares (or, following the Domestication, the Plum Common Shares), Plum Units and Plum Public Warrants will be no longer qualified on the OTC Pink, and Plum will be deregistered under the Exchange Act. Each Plum Class A Share (or, following the Domestication, each Plum Common Share) will be exchanged for one PubCo Common Share and each Plum Warrant will automatically be exchanged for one PubCo Warrant.
PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its respective original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing, the PubCo Common Shares and PubCo Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively. Please see the subsection entitled “The Business Combination — Listing of PubCo Common Shares and PubCo Warrants on the NASDAQ” for additional information. Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX-V, and TRC will apply to have TRC cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
Q: What vote is required to approve the Proposals presented at the Plum Shareholders’ Meeting?
A: Approval of the Domestication Proposal requires the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of not less than two thirds (662⁄3%) of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. Each of the Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal require the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of a majority of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class.
30
Q: May Sponsor, directors, officers, advisors or any of their respective affiliates purchase Plum Public Shares in connection with the Business Combination?
A: In connection with the vote of Plum Shareholders to approve the proposed Business Combination, Sponsor, Plum management or Plum’s advisors and any of their respective affiliates may privately negotiate to purchase Plum Public Shares from Plum Public Shareholders who would have otherwise elected to have their shares redeemed in conjunction with a proxy solicitation pursuant to the proxy rules for a per share pro rata portion of the Trust Account. Sponsor, Plum management or Plum’s advisors and any of their respective affiliates will not make any such purchases when they are in possession of any material non-public information not disclosed to the seller of such Plum Public Shares or during a restricted period under Regulation M under the Exchange Act or other federal securities laws. Such a purchase could include a contractual acknowledgement that such Plum Shareholder, although still the record holder of such Plum Public Shares, is no longer the beneficial owner thereof and therefore agrees not to exercise its redemption rights. Any Plum Public Shares purchased by Sponsor, Plum management or Plum’s advisors or any of their respective affiliates would not be voted in favor of approving the Business Combination. In the event that Sponsor, Plum management or Plum’s advisors or any of their respective affiliates purchase Plum Public Shares in privately negotiated transactions from Plum Public Shareholders who have already elected to exercise their redemption rights, such selling shareholders would be required to revoke their prior elections to redeem their shares. In addition, Sponsor, Plum management and Plum’s advisors or any of their respective affiliates would waive any redemption rights with respect to any Plum Public Shares that they purchase in any such privately negotiated transactions. The Sponsor and Plum management did not receive any compensation for agreeing to waive any redemption rights. Any such privately negotiated purchases may be effected at purchase prices that are no higher than the per share pro rata portion of the Trust Account.
Q: How many votes do I have at the Plum Shareholders’ Meeting?
A: For all Proposals, Plum Shareholders are entitled to one vote at the Plum Shareholders’ Meeting for each Plum Class A Share or Plum Class B Share held of record as of [•], 2025, the record date for the Plum Shareholders’ Meeting. As of the close of business on the record date, there were 1,016,833 outstanding Plum Class A Shares, which are held by Plum Public Shareholders, and 7,062,500 outstanding Plum Class B Shares, which are held by the Sponsor Parties.
Q: How do I attend the Plum Shareholders’ Meeting?
A: The Plum Shareholders’ Meeting will be held at [•], 2025, at 10:00 a.m., Eastern Time, virtually via live webcast at https://www [•], pursuant to the procedures described in this proxy statement/prospectus, to consider and vote upon the Proposals. All Plum Shareholders as of the record date, or their duly appointed proxies, may attend the Plum Shareholders’ Meeting, which will be held both in person and virtually. Plum Shareholders may attend the Plum Shareholders’ Meeting online, including to vote and submit questions, at https://www [•]. To attend online and participate in the Plum Shareholders’ Meeting, Plum Shareholders of record will need to visit https://www [•] and enter the 12 digit control number provided on your proxy card, regardless of whether you pre-registered.
Q: What constitutes a quorum at the Plum Shareholders’ Meeting?
A: Holders of at least a majority of the paid up voting share capital of Plum, present in person or represented by proxy (including by way of online meeting option) at the Plum Shareholders’ Meeting, constitute a quorum. In the absence of a quorum, the chairman of the meeting has the power to adjourn the Plum Shareholders’ Meeting. As of the record date for the Plum Shareholders’ Meeting, 5,105,850 Plum Class A Shares and Plum Class B Shares, in the aggregate, will be required to achieve a quorum. Abstentions will count as present for the purposes of establishing a quorum.
Q: How will Sponsor and Plum management vote?
A: Sponsor and Plum management have agreed to vote any Plum Class A Shares (except for any Plum Class A Shares purchased as described above under “May Sponsor, directors, officers, advisors or any of their respective affiliates purchase Plum Public Shares in connection with the Business Combination?” and below under “The Business Combination — Potential Purchases of Public Shares”) held by them in favor of the
31
Business Combination. Sponsor Parties have agreed to vote any Plum Class B Shares held by them in favor of the Business Combination. The consummation of the Business Combination is not subject to the approval of a majority of unaffiliated Plum Public Shareholders. Since the Sponsor Parties own approximately 87.4% of the Plum Shares entitled to vote at the Plum Shareholders’ Meeting, the Sponsor Parties have sufficient votes to approve all of the Proposals without the vote of any of the Plum Public Shareholders.
Q: What interests do the current officers and directors have in the Business Combination?
A: In considering the unanimous recommendation of the Plum Board to vote in favor of the Business Combination, Plum Public Shareholders should be aware that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, those of other Plum Public Shareholders generally. The existence of financial and personal interests of one or more of Plum’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of Plum and Plum Shareholders and what he, she or they may believe is best for himself or themselves in determining to recommend that shareholders vote for the proposals. Plum’s directors were aware of and considered these interests, among other matters, in evaluating the Business Combination, and in recommending to Plum Shareholders that they approve the Business Combination. Plum Shareholders should take these interests into account in deciding whether to approve the Business Combination. These interests include, among other things:
• Pursuant to the Plum Articles, the Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares and have agreed to waive redemption rights with respect to any Plum Public Shares held by them in connection with the consummation of the Initial Business Combination. Additionally, Plum Founder Shareholders are not entitled to liquidation rights with respect to any Plum Founder Shares held by them if Plum fails to consummate the Initial Business Combination by July 30, 2025, or such later date as approved by Plum’s shareholders. If Plum does not complete the Initial Business Combination within such applicable time period, the proceeds of the sale of the Plum Private Placement Warrants held in the Trust Account will be used to fund the liquidation of the Plum Public Shares, and the Plum Private Placement Warrants will expire without the receipt of any value by the holders of such warrants. Since Sponsor and Plum management directly or indirectly own Plum Common Shares and Plum Private Placement Warrants, Plum management may have a conflict of interest in determining whether a particular target business is an appropriate business with which to effectuate the Initial Business Combination.
• The fact that Sponsor purchased from Former Sponsor 3,902,648 Plum Founder Units and 70% of 2,030,860 Plum Founder Units that Former Sponsor placed in escrow at the time of closing the purchase agreement for the Plum Founder Units to the extent such Plum Founder Units are not allocated to investors who hold and do not redeem their Plum Class A Shares of the Company at the time of an initial business combination for an aggregate of $1, and that such securities, after separating the founder Units into shares and warrants, will have a significantly higher value at the time of the Business Combination, which if the Founder Shares are unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•];
• The fact that given the differential in the purchase price that Sponsor paid for the Plum Founder Shares as compared to the price of the Plum Units sold in the Plum IPO and the 3,902,648 PubCo Common Shares that Sponsor will receive upon conversion of the Plum Founder Shares in connection with the Business Combination, Sponsor and its affiliates may earn a positive rate of return on their investment even if the PubCo Common Shares trade below the price initially paid for the Plum Units in the Plum IPO and the Plum Public Shareholders experience a negative rate of return following the completion of the Business Combination;
• The fact that Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting;
32
• The fact that certain members of Plum management collectively own, directly or indirectly, a material interest in Sponsor;
• Sponsor and Plum management may have a conflict of interest with respect to evaluating a business combination and financing arrangements as Plum may obtain loans from Sponsor or an affiliate of Sponsor or any of Plum management to finance transaction costs in connection with the initial business combination;
• The Plum Articles provide that Plum renounces any interest or expectancy in, or in being offered an opportunity to participate in, any potential transaction or matter which may be a corporate opportunity for any member of Plum management on the one hand, and Plum, on the other hand, or the participation of which would breach any existing legal obligation, under applicable law or otherwise, of a member of Plum management to any other entity. Plum is not aware of any such corporate opportunities not being offered to Plum and does not believe that waiver of the corporate opportunities doctrine has materially affected Plum’s search for an acquisition target or will materially affect Plum’s ability to complete an initial business combination;
• If the Trust Account is liquidated, including in the event Plum is unable to complete an Initial Business Combination within the required time period, Sponsor has agreed to indemnify Plum to ensure that the proceeds in the Trust Account are not reduced below $10.00 per Plum Public Share, or such lesser amount per Plum Public Share as is in the Trust Account on the liquidation date, by the claims of (a) any third party (other than Plum’s independent public accountants) for services rendered or products sold to Plum or (b) a prospective target business with which Plum has entered into a letter of intent, confidentiality or other similar agreement or business combination agreement, but only if such a third party or target business has not executed a waiver of all rights to seek access to the Trust Account;
• The fact that the Company has borrowed certain amounts from the Sponsor pursuant to a promissory note which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants at a price of $1.50 per warrant, to be issued at Closing;
• The fact that Sponsor will benefit from the completion of an Initial Business Combination and may be incentivized to complete an acquisition of a less favorable target company or on terms less favorable to Plum Shareholders rather than liquidate;
• The fact that Plum has a right to propose a director nominee for the post-closing PubCo board of directors, which TRC may accept or reject in its sole discretion. If TRC accepts Plum’s director nominee, TRC may propose two additional director nominees, one of which Plum must accept;
• The fact that PubCo will indemnify Sponsor and its affiliates and their respective present and former directors and officers for a period of six years from the Closing, in connection with any claim, action, suit, proceeding or investigation and Sponsor’s ownership of Plum Securities or its control or ability to influence Plum; and
• The terms and provisions of the Related Agreements as set forth in detail under the subsection entitled “The Business Combination — Related Agreements.”
33
The table set forth below summarizes the existing interests in Plum private placement securities and the anticipated interests of Former Sponsor, Sponsor, Plum management, and the lender under a subscription agreement in PubCo as of Closing along with the value of such interests based on (i) in the case of Sponsor’s and Plum management’s interests, the closing price of the Plum Public Warrants and Plum Class A Shares as of [•], 2025, which would be lost if an Initial Business Combination is not completed by Plum by the Deadline Date, and (ii) the transaction value:
|
Name of Holder |
Type of |
Total |
Number of |
Number of |
Value of |
Number of |
Number of |
Value of |
|||||||||
|
Mercury Capital, |
Sponsor |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Alpha Partners Technology Merger Sponsor, LLC(2) |
Former Sponsor |
$ |
6,675,000 |
665,000 |
221,667 |
1,128,992 |
376,331 |
||||||||||
|
Palmeira Investment |
Lender to Sponsor |
$ |
750,000 |
0 |
0 |
637,500 |
0 |
||||||||||
|
Kanishka Roy(4) |
CEO & |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Steven Handwerker |
CFO |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Hume Kyle |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Alan Black |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
David Sable |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
____________
(1) On December 27, 2023, Plum, Alpha Partners Technology Merger Sponsor, LLC, and Mercury Capital, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which Mercury Capital, LLC the Sponsor (i) purchased 3,902,648 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B share, and (ii) became entitled to 70% of the 2,030,860 Founder Units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such Founder Units are not allocated to investors who hold and do not redeem their Class A Shares of Plum at the time of Plum’s initial business combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(2) Alpha Partners Technology Merger Sponsor, LLC paid an aggregate of $25,000 for 7,187,500 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B share, 125,000 of which were forfeited due to only a partial exercise of the over-allotment option. Additionally, Alpha Partners Technology Merger Sponsor, LLC purchased 665,000 private placement units at an aggregate price of $6,650,000. On December 27, 2023, Alpha Partners Technology Merger Sponsor, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which they sold 3,902,648 Founder Units to Mercury Capital, LLC, and put 2,030,860 Founder Units into escrow, of which they are entitled to 30% of the Founder Units in Escrow if they are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of the Company’s initial Business Combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(3) Palmeira Investment Limited and Mercury Capital, LLC are party to a subscription agreement, dated January 3, 2024, pursuant to which Mercury Capital, LLC may raise funds to pay for extension payments and working capital on behalf of Plum Acquisition Corp. III. Pursuant to the terms of the subscription agreement, Mercury Capital, LLC will forfeit 0.85 Class B Shares for every $1.00 loaned under the agreement and cause Plum Acquisition Corp. III to issue such number of shares forfeited to Palmeira Investment Limited upon closing of the business combination. As of Mercury Capital LLC’s last drawdown under the subscription agreement, Palmeira Investment Limited had loaned $750,000 to Mercury Capital, LLC under the subscription agreement.
(4) Kanishka Roy serves as manager for Mercury Capital, LLC and may be deemed to beneficially own shares held by Mercury Capital, LLC by virtue of his control over Mercury Capital, LLC. Mr. Roy disclaims beneficial ownership of such shares other than to the extent of his pecuniary interest in such shares.
Q: Are there material differences between my rights as a PubCo Shareholder and my rights as a Plum Shareholder?
A: Yes. There are certain material differences between your rights as a PubCo Shareholder and your rights as a Plum Shareholder. You are urged to read the sections entitled “Descriptions of PubCo Securities” and “Comparison of Corporate Governance and Shareholder Rights.”
34
Q: What happens if I vote against the Business Combination Proposal?
A: Under the Plum Articles, if the Business Combination Proposal is not approved and Plum does not otherwise consummate an alternative business combination by the Deadline Date, Plum will be required to dissolve and liquidate the Trust Account by returning the then-remaining funds in such account to Plum Public Shareholders.
Q: Do I have redemption rights?
A: Pursuant to the Plum Articles, a Plum Public Shareholder may request that PubCo redeem all or a portion of its Plum Public Shares for cash if the Business Combination is consummated. As a Plum Public Shareholder, you will be entitled to exercise your redemption rights if you:
• hold Plum Public Shares or, if you hold Plum Public Shares through Plum Units, you elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising your redemption rights;
• submit a written request to Continental Stock Transfer & Trust Company, the Transfer Agent, in which you (i) request the exercise of your redemption rights with respect to all or a portion of your Plum Public Shares for cash and (ii) identify yourself as the beneficial holder of the Plum Public Shares and provide your legal name, phone number and address; and
• deliver your Plum Public Shares to the Transfer Agent, physically or electronically through DTC.
Holders must complete the procedures for electing to redeem their Plum Public Shares in the manner described above prior to 10:30 a.m., Eastern Time, on [•], 2025 (two business days before the Plum Shareholders’ Meeting) in order for their shares to be redeemed.
Holders of Plum Units must elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising their redemption rights with respect to the Plum Public Shares. If Plum Public Shareholders hold their Plum Units in an account at a brokerage firm or bank, such Plum Public Shareholders must notify their broker or bank that they elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants, or if a holder holds Plum Units registered in its own name, the holder must contact the Transfer Agent directly and instruct it to do so. The redemption rights include the requirement that a holder must identify itself to Plum in order to validly exercise its redemption rights. Plum Public Shareholders may elect to exercise their redemption rights with respect to their Plum Public Shares even if they vote “FOR” the Business Combination Proposal. If the Business Combination is not consummated, the Plum Public Shares will be returned to the respective holder, broker or bank. If the Business Combination is consummated, and if a Plum Public Shareholder properly exercises its redemption rights with respect to all or a portion of the Plum Public Shares that it holds and timely delivers its shares to the Transfer Agent, PubCo will redeem the related PubCo Common Shares for a per share price, payable in cash, equal to the pro rata portion of the Trust Account, including interest earned on the fund held in the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination. For illustrative purposes, as of [•], 2025, this would have amounted to approximately $[•] per issued and outstanding Plum Public Share. If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. Please see the subsection entitled “Plum Shareholders’ Meeting — Redemption Rights” for the procedures to be followed if you wish to exercise your redemption rights with respect to your Plum Public Shares.
Q: Will how I vote affect my ability to exercise redemption rights?
A: No. You may exercise your redemption rights whether you vote your Plum Class A Shares for or against or abstain from voting on the Business Combination Proposal or any other Proposal described in this proxy statement/prospectus. As a result, the Business Combination can be approved by Plum Public Shareholders who will redeem their shares and no longer remain shareholders.
35
Q: How do I exercise my redemption rights?
A: In order to exercise your redemption rights, you must (a) if you hold Plum Units, elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising your redemption rights with respect to the Plum Public Shares; and (b) prior to 10:30 a.m., Eastern Time, on [•], 2025 (two business days before the Plum Shareholders’ Meeting), tender your shares physically or electronically and submit a request in writing that PubCo redeem your PubCo Common Shares that you receive in exchange for your Plum Public Shares for cash to Continental Stock Transfer & Trust Company, the Transfer Agent, at the following address:
Continental Stock Transfer & Trust Company
1 State Street, 30th Floor
New York, New York 10004-1561
Attention: Mark Zimkind
Email: mzimkind@continentalstock.com
A Plum Public Shareholder, together with any of his, her or its affiliates or any other person with whom it is acting in concert or as a “group” (as defined in Section 13(d)(3) of the Exchange Act), will be restricted from seeking redemption rights with respect to his, her or its shares or, if part of such a group, the group’s shares, in excess of the 15% threshold. Accordingly, all Plum Public Shares in excess of the 15% threshold beneficially owned by a Plum Public Shareholder or group will not be redeemed for cash. Plum Shareholders who hold their shares in street name will have to coordinate with their bank, broker or other nominee to have the shares delivered electronically. If you do not submit a written request and deliver your Plum Public Shares as described above, your shares will not be redeemed.
Plum Shareholders seeking to exercise their redemption rights, whether they are record holders or hold their Plum Common Shares in “street name” are required to either tender their certificates to the Transfer Agent prior to the date set forth in this proxy statement/prospectus, or up to two business days prior to the vote on the Business Combination Proposal at the Plum Shareholders’ Meeting, or to deliver their shares to the Transfer Agent electronically using DTC’s DWAC system, at such shareholder’s option. The requirement for physical or electronic delivery prior to the Plum Shareholders’ Meeting ensures that a redeeming shareholder’s election to redeem is irrevocable without Plum’s consent once the Business Combination is consummated.
Plum Unitholders must elect to separate their Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising redemption rights with respect to the Plum Public Shares. If you hold Plum Units registered in your own name, you must deliver the certificate for such Plum Units to the Transfer Agent, with written instructions to separate such Plum Units into Plum Public Shares and Plum Public Warrants. This must be completed far enough in advance to permit the mailing of the Plum Public Share certificates back to you so that you may then exercise your redemption rights upon the separation of the Plum Public Shares from the Plum Units.
If a broker, dealer, commercial bank, trust company or other nominee holds your Plum Units, you must instruct such nominee to separate your Plum Units. Your nominee must send written instructions by facsimile to the Transfer Agent. Such written instructions must include the number of Plum Units to be split and the nominee holding such Plum Units. Your nominee must also initiate electronically, using DTC’s DWAC system, a withdrawal of the relevant units and a deposit of a corresponding number of Plum Public Shares and Plum Public Warrants. This must be completed far enough in advance to permit your nominee to exercise your redemption rights upon the separation of the Plum Public Shares from the Plum Units. While this is typically done electronically on the same business day, you should allow at least one full business day to accomplish the separation. If you fail to cause your Plum Units to be separated in a timely manner, you will likely not be able to exercise your redemption rights.
Any demand for redemption, once made, may be withdrawn at any time until the deadline for exercising redemption requests and thereafter, with Plum’s consent, until the Closing. If you delivered your shares for redemption to the Transfer Agent and decide within the required timeframe not to exercise your redemption rights, you may request that the Transfer Agent return the shares (physically or electronically). You may make such request by contacting the Transfer Agent at the email address or address listed under the question “Who can help answer my questions?” below.
36
Plum Public Shareholders may elect to exercise their redemption rights with respect to their Plum Public Shares even if they vote “FOR” the Business Combination Proposal. If the Business Combination is not consummated, the Plum Public Shares will be returned to the respective holder, broker or bank. If the Business Combination is consummated, and if a Plum Public Shareholder properly exercises its redemption rights with respect to all or a portion of the Plum Public Shares it holds and timely delivers its shares to the Transfer Agent, PubCo will redeem the related PubCo Common Shares for a per share price, payable in cash, equal to the pro rata portion of the Trust Account, including interest earned on the funds held in the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination. Please see the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” for the procedures to be followed if you wish to exercise your redemption rights with respect to your Plum Public Shares.
Prior to exercising redemption rights, Plum Shareholders should verify the market price of the Plum Class A Shares, as Plum Shareholders may receive higher proceeds from the sale of their Plum Class A Shares in the public market than from exercising their redemption rights if the market price per share is higher than the redemption price. You may not be able to sell your Plum Class A Shares in the open market, even if the market price per share is higher than the redemption price stated above, as there may not be sufficient liquidity in the Plum Class A Shares when you wish to sell your shares.
If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation Effective Time and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. You will no longer own those shares and you will have no right to participate in, or have any interest in, the future growth of PubCo, if any. You will be entitled to receive cash for your PubCo Common Shares only if you properly and timely demand redemption.
Each redemption of PubCo Common Shares by Plum Public Shareholders will reduce the amount in the Trust Account. Pursuant to Article 49.7 of the Plum Articles, if Plum does not consummate an Initial Business Combination by the Deadline Date, Plum will be required to dissolve and liquidate the Trust Account by returning the then remaining funds in such account to the Plum Public Shareholders and all Plum Warrants will expire worthless.
Q: What are the material U.S. federal income tax consequences to the Plum Shareholders that are U.S. Holders as a result of the Domestication and Plum Amalgamation?
A: As discussed more fully below in the subsection entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders — Tax Consequences of the Domestication and the Plum Amalgamation,” it is intended that the Domestication and the Plum Amalgamation each qualify as a “reorganization” within the meaning of Section 368(a)(1)(F) of the Code (an “F Reorganization”) or another form of reorganization within the meaning of Section 368(a) of the Code. If the Domestication and the Plum Amalgamation so qualify, the Plum Shareholders that are U.S. Holders (as defined below in the subsection entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders”) should not recognize gain or loss for U.S. federal income tax purposes in connection with the Domestication or the Plum Amalgamation, subject to the discussion contained herein regarding the “passive foreign investment company” (or “PFIC”) rules.
The rules governing the U.S. federal income tax treatment of the Domestication and the Plum Amalgamation are complex and will depend on a U.S. Holder’s particular circumstances. Furthermore, although the Domestication and the Plum Amalgamation are each intended to qualify as an F Reorganization or another form of reorganization within the meaning of Section 368(a) of the Code, and Plum and PubCo intend to report the Domestication and the Plum Amalgamation consistent with such qualification, such treatment is not a condition to Plum’s or PubCo’s or TRC’s obligation to complete the Business Combination. All Plum Shareholders and holders of Plum Public Warrants are urged to consult with, and rely solely upon, their own tax advisors regarding the potential tax consequences to them of the Domestication and the Plum Amalgamation, including the applicability and effect of the PFIC rules and other U.S. federal, state and local and non-U.S. tax laws. For a more complete discussion of the U.S. federal income tax considerations of the Domestication and the Plum Amalgamation for U.S. Holders, please see the subsection entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders — Tax Consequences of the Domestication and the Plum Amalgamation — PFIC Considerations.”
37
Q: What are the U.S. federal income tax consequences of exercising my redemption rights if I am a U.S. Holder?
A: The receipt of cash by a U.S. Holder in redemption of such shares will be a taxable event for U.S. federal income tax purposes. It is expected that a redeeming U.S. Holder will be treated as selling its PubCo Common Shares and will recognize capital gain or loss. There may be certain circumstances, however, in which the redemption will not be treated as a sale of PubCo Common Shares for U.S. federal income tax purposes, and the redemption will instead be treated as a distribution of cash from PubCo. Notwithstanding the foregoing, if Plum (or, after the Plum Amalgamation, PubCo) is treated as a PFIC at any time during a U.S. Holder’s holding period of Plum Class A Shares or PubCo Common Shares, unless a redeeming U.S. Holder has made certain elections, the gain recognized or proceeds received in the redemption may be subject to tax at ordinary income rates and an interest charge under a complex set of computational rules. For a more complete discussion of the U.S. federal income tax considerations of the exercise of redemption rights for U.S. Holders, please see the subsection entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders — Tax Consequences of the Domestication and the Plum Amalgamation — Tax Consequences to U.S. Holders that Elect to Exercise Redemption Rights.”
Because the Domestication and the Plum Amalgamation will occur prior to the redemption of stock from U.S. Holders that exercise their redemption rights, such U.S. Holders will be subject to the potential tax consequences of the Domestication and the Plum Amalgamation. The tax considerations for U.S. Holders with respect to the Domestication and the Plum Amalgamation are discussed more fully in the subsection entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders — Tax of the Domestication and the Plum Amalgamation.”
All holders considering the exercise of their redemption rights should consult with, and rely solely upon, their own tax advisors with respect to the tax consequences to them under U.S. federal, state and local and non-U.S. tax laws of exercising such redemption rights.
Q: What are the material federal tax consequences of the Business Combination to TRC Shareholders?
A: As discussed more fully below in the subsection entitled “Material U.S. Federal Income Tax Considerations for TRC U.S. Holders — Tax Consequences of the TRC Amalgamation,” it is intended that the TRC Amalgamation qualifies as a “reorganization” within the meaning of Section 368(a) of the. If the TRC Amalgamation so qualifies, the TRC Shareholders that are U.S. Holders (as defined below in the subsection entitled “Material U.S. Federal Income Tax Considerations for TRC U.S. Holders”) should not recognize gain or loss for U.S. federal income tax purposes in connection with the TRC Amalgamation, subject to the discussion contained herein regarding the “passive foreign investment company” (or “PFIC”) rules.
The rules governing the U.S. federal income tax treatment of the TRC Amalgamation are complex and will depend on a U.S. Holder’s particular circumstances. Furthermore, although the TRC Amalgamation is intended to qualify as a reorganization within the meaning of Section 368(a) of the Code, and TRC and PubCo intend to report the TRC Amalgamation consistent with such qualification, such treatment is not a condition to Plum’s or TRC’s obligation to complete the Business Combination. All TRC Shareholders are urged to consult with, and rely solely upon, their own tax advisors regarding the potential tax consequences to them of the TRC Amalgamation, including the applicability and effect of the PFIC rules and other U.S. federal, state and local and non-U.S. tax laws. For a more complete discussion of the U.S. federal income tax considerations of the TRC Amalgamation for U.S. Holders, please see the subsection entitled “Material U.S. Federal Income Tax Considerations for TRC U.S. Holders.”
Q: If I am a Plum Warrant Holder, can I exercise redemption rights with respect to my Plum Warrants?
A: No. Plum Warrant Holders have no redemption rights with respect to Plum Warrants.
Q: How do the Plum Public Warrants differ from the Plum Private Placement Warrants, and what are the related risks for any Plum Public Warrant Holders post-Business Combination?
A: The Plum Private Placement Warrants (including the Plum Class A Shares issuable upon exercise of the Plum Private Placement Warrants) will not be transferable, assignable or salable until 30 days after the completion of the Initial Business Combination (except, among other limited exceptions, to Plum management and other persons or entities affiliated with Sponsor), and they will not be redeemable by Plum so long as they are held
38
by the initial purchasers of the Plum Private Placement Warrants or their permitted transferees. The initial purchasers, or their permitted transferees, have the option to exercise the Plum Private Placement Warrants for cash or on a “cashless basis.” Otherwise, the Plum Private Placement Warrants have terms and provisions that are identical to those of the Plum Public Warrants, including as to exercise price, exercisability and exercise period. If the Plum Private Placement Warrants are held by holders other than the initial purchasers or their permitted transferees, the Plum Private Placement Warrants will be redeemable by Plum in all redemption scenarios and exercisable by such holders on the same basis as the Plum Public Warrants
In connection with the consummation of the Business Combination, PubCo will assume the Plum Warrant Agreement and enter into such amendments thereto as are necessary to give effect to the provisions of the Business Combination Agreement, and each Plum Warrant will automatically, without any action on the part of its holder, be exchanged for a PubCo Warrant. Each such PubCo Warrant will be subject to the same terms and conditions (including exercisability terms) as were applicable to the corresponding Plum Warrant immediately prior to the Plum Amalgamation Effective Time, except to the extent such terms or conditions are rendered inoperative by the Business Combination.
Following the Business Combination, PubCo may redeem PubCo Public Warrants prior to their exercise at a time that is disadvantageous to the PubCo Public Warrant Holders, thereby making such PubCo Public Warrants worthless. More specifically:
• PubCo will have the ability to redeem outstanding PubCo Public Warrants at any time after they become exercisable and prior to their expiration, at a price of $0.01 per warrant, provided that the reported last sale price of the PubCo Common Shares has been at least $18.00 per share (as adjusted for share subdivisions, share dividends, reorganizations, recapitalizations and the like) for any 20 trading days within the 30 trading-day period ending on the third business day prior to the date on which PubCo gives notice of such redemption and provided certain other conditions are met.
• PubCo will have the ability to redeem outstanding PubCo Public Warrants at any time after they become exercisable and prior to their expiration, at a price of $0.10 per warrant if, among other things, the last reported sale price of the PubCo Common Shares equals or exceeds $10.00 per share (as adjusted for share subdivisions, share dividends, reorganizations, recapitalizations and the like) on the trading day prior to the date on which notice of the redemption is given. Historical trading prices for the Plum Class A Shares have exceeded the $10.00 per share threshold at which the Plum Public Warrants (or, following the Business Combination, the PubCo Public Warrants) would become redeemable. In such a case, the PubCo Public Warrant Holders will be able to exercise their PubCo Public Warrants prior to redemption for a number of PubCo Common Shares determined by reference to a make-whole table. Please see the subsection entitled “Description of Securities — Warrants — Redemption of Plum Warrants for Cash When the Price Per Plum Class A Share Equals or Exceeds $10.00.” The value received upon exercise of the PubCo Public Warrants (1) may be less than the value the PubCo Public Warrant Holders would have received if they had exercised their PubCo Public Warrants at a later time where the underlying share price is higher and (2) may not compensate the PubCo Public Warrant Holders for the value of the PubCo Public Warrants, including because the number of shares received is capped at 0.361 PubCo Common Shares per whole warrant (subject to adjustment) irrespective of the remaining life of the PubCo Public Warrants.
In each case, PubCo may only call the PubCo Public Warrants for redemption upon a minimum of 30 days’ prior written notice of redemption to each PubCo Public Warrant Holder.
Redemption of the outstanding PubCo Public Warrants could force PubCo Public Warrant Holders (i) to exercise PubCo Public Warrants and pay the exercise price therefor at a time when it may be disadvantageous for such PubCo Public Warrant Holders to do so, (ii) to sell PubCo Public Warrants at the then-current market price when they might otherwise wish to hold their PubCo Public Warrants or (iii) to accept the nominal redemption price which, at the time the outstanding PubCo Public Warrants are called for redemption, is likely to be substantially less than the market value of the PubCo Public Warrants.
39
Q: Do I have appraisal or dissent rights if I object to the proposed Business Combination?
A: There is no mandatory statutory right of dissent and appraisal in respect of plans of arrangement under the BCBCA unless the terms of the arrangement permit dissent. The Business Combination Agreement does not contemplate any dissent rights or appraisal rights to be available to holders of Plum Class A Shares and Plum Class B Shares in connection with the Business Combination. However, Plum Shareholders are still entitled to exercise the rights of redemption as set out in the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” and the Plum Board has determined that the redemption proceeds payable to Plum Shareholders who exercise such redemption rights represents the fair value of those Plum Common Shares. Please see the subsection entitled “The Business Combination — Appraisal or Dissent Rights” for more information.
Q: What happens to the funds deposited in the Trust Account after consummation of the Business Combination?
A: If the Domestication Proposal and the Business Combination Proposal are approved, Plum intends to use a portion of the funds held in the Trust Account to pay (a) a portion of Plum’s aggregate costs, fees and expenses in connection with the consummation of the Business Combination, (b) tax obligations and deferred underwriting discounts and commissions from the Plum IPO and (c) for any redemptions of Plum Public Shares. The remaining balance in the Trust Account will be used for general corporate purposes of PubCo. See the sections entitled “The Business Combination” and “Proposal No. 2 — The Business Combination Proposal” for additional information.
Q: What happens if the Business Combination is not consummated or is terminated?
A: There are certain circumstances under which the Business Combination Agreement may be terminated. See the subsection entitled “Business Combination Agreement — Termination” for additional information regarding the parties’ specific termination rights. In accordance with the Plum Articles, if an Initial Business Combination is not consummated by the Deadline Date, Plum will (a) cease all operations except for the purpose of winding up, (b) as promptly as reasonably possible but not more than ten business days thereafter, redeem the Plum Public Shares, at a per-share price, payable in cash, equal to the aggregate amount then on deposit in the Trust Account including interest earned on the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay taxes, if any, divided by the number of then-outstanding Plum Public Shares, which redemption will completely extinguish Plum Public Shareholders’ rights as Plum Public Shareholders (including the right to receive further liquidation distributions, if any), subject to applicable law, and (c) as promptly as reasonably possible following such redemption, subject to the approval of Plum’s remaining Plum Shareholders and the Plum Board, liquidate and dissolve, subject in the case of clause (b) and this clause (c), to Plum’s obligations under Cayman Islands law to provide for claims of creditors and in all cases subject to the other requirements of applicable law.
Plum expects that the amount of any distribution Plum Public Shareholders will be entitled to receive upon Plum’s dissolution will be approximately the same as the amount they would have received if they had redeemed their Plum Public Shares in connection with the Business Combination, subject in each case to Plum’s obligations under Cayman Islands law to provide for claims of creditors and other requirements of applicable law. Sponsor or Former Sponsor are not entitled to liquidation distributions with respect to those shares.
In the event of liquidation, there will be no distribution with respect to Plum Warrants then-outstanding. Accordingly, in such an event, the Plum Warrants will expire worthless.
Q: When is the Business Combination expected to be consummated?
A: It is currently anticipated that the Business Combination will be consummated promptly following the Plum Shareholders’ Meeting to be held on [•], 2025 provided that all the requisite shareholder approvals are obtained and other conditions to the consummation of the Business Combination have been satisfied or waived. For a description of the conditions to the completion of the Business Combination, see the subsection entitled “The Business Combination Agreement — Conditions to Closing of the Business Combination.”
40
Q: What is TRC?
A: TRC is a mineral exploration company engaged in the acquisition, exploration, and development of rare earth mineral properties. TRC was incorporated under the BCBCA on June 25, 2018. The principal business of TRC is the exploration and development of rare earth elements (“REE”) through the Peak REE Project. TRC is a reporting issuer in British Columbia, Alberta and Ontario. Please see the section entitled “Business of TRC and Certain Information About TRC” for more information
Q: What will Plum Shareholders receive in the Business Combination?
A: Pursuant to the Plum Amalgamation, each Plum Common Share (which include both Plum Class A Shares and Plum Class B Shares) then issued and outstanding will be exchanged, on a one-for-one basis, for a PubCo Common Share, pursuant to the PubCo Articles and in accordance with the Plan of Arrangement.
Q: What will Plum Warrant Holders receive in the Business Combination?
A: At the Plum Amalgamation Effective Time, PubCo will assume the TRC Warrant Agreement and enter into such amendments thereto as are necessary to give effect to the provisions of the Business Combination Agreement, and each Plum Warrant then outstanding and unexercised will automatically, without any action on the part of its holder, be exchanged for a PubCo Warrant. Each PubCo Warrant will be subject to the same terms and conditions (including exercisability terms) as were applicable to the corresponding Plum Warrant immediately prior to the Plum Amalgamation, except to the extent such terms or conditions are rendered inoperative by the Business Combination. Accordingly, effective following the Plum Amalgamation: (A) each PubCo Warrant will be exercisable solely for PubCo Common Shares; (B) the number of PubCo Common Shares subject to each PubCo Warrant will be equal to the number of Plum Class A Shares subject to the applicable Plum Warrant; and (C) the per share exercise price for the PubCo Common Shares issuable upon exercise of such PubCo Warrant will be equal to the per share exercise price for the Plum Class A Shares subject to the applicable Plum Warrant, as in effect immediately prior to the Plum Amalgamation.
Q: What will Plum Unitholders receive in the Business Combination?
A: At the Plum Amalgamation Effective Time, each Plum Unit then issued and outstanding will be exchanged for a PubCo Unit. At the TRC Amalgamation Effective Time, each PubCo Unit will automatically be detached and broken out into their component securities. PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing, the PubCo Common Shares and PubCo Warrants will be listed on NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively. Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX-V, and TRC will apply to have TRC cease to be a reporting issuer in the jurisdiction in which it is currently a reporting issuer.
Q: What do I need to do now?
A: You are urged to read carefully and consider the information contained in this proxy statement/prospectus, including the section entitled “Risk Factors” and the annexes attached to this proxy statement/prospectus, and to consider how the Business Combination will affect you as a shareholder. You should then vote as soon as possible in accordance with the instructions provided in this proxy statement/prospectus and on the enclosed proxy card or, if you hold your shares through a brokerage firm, bank or other nominee, on the voting instruction form provided by the broker, bank or nominee.
Q: How do I vote?
A: If you are a shareholder of record, there are two ways to vote your Plum Class A Shares or Plum Class B Shares at the Plum Shareholders’ Meeting: (i) you can attend the Plum Shareholders’ Meeting (by way of online meeting option) and vote or (ii) you can vote by signing and returning the enclosed proxy card, or you can submit your proxy by telephone or over the internet by following the instructions on your proxy card. If you vote by proxy card, your “proxy,” whose name is listed on the proxy card, will vote your Plum Common
41
Shares as you instruct on the proxy card. If you sign and return the proxy card but do not give instructions on how to vote your Plum Common Shares, your Plum Common Shares will be voted as recommended by the Plum Board “FOR” each of the Proposals. If your Plum Common Shares are held in “street name” or are in a margin or similar account, you should contact your broker, bank or other nominee to ensure that votes related to the Plum Common Shares beneficially owned by you are properly counted. Beneficial Plum Shareholders who wish to vote by attending the Plum Shareholders’ Meeting virtually must obtain a legal proxy by contacting the bank, broker or other nominee that holds their Plum Common Shares.
Q: What will happen if I abstain from voting or fail to vote at the Plum Shareholders’ Meeting?
A: At the Plum Shareholders’ Meeting, a properly executed proxy marked “ABSTAIN” with respect to a particular Proposal will count as present for purposes of determining whether a quorum is present. For purposes of approval, failure to vote or an abstention will have no effect on the Proposals (assuming a quorum is present).
Q: What will happen if I sign and submit my proxy card without indicating how I wish to vote?
A: Signed and dated proxies received by Plum without an indication of how the Plum Shareholder intends to vote on a Proposal will be voted “FOR” each Proposal being submitted to a vote of the Plum Shareholders at the Plum Shareholders’ Meeting.
Q: If I am not going to attend the Plum Shareholders’ Meeting, should I submit my proxy card instead?
A: Yes. Whether you plan to attend the Plum Shareholders’ Meeting or not, please read this proxy statement/prospectus carefully, and vote your Plum Common Shares by completing, signing, dating, and returning the enclosed proxy card in the postage-paid envelope provided.
Q: If my Plum Common Shares are held in “street name,” will my broker, bank or nominee automatically vote my shares for me?
A: No. Under the rules of various national and regional securities exchanges, your broker, bank, or nominee cannot vote your Plum Common Shares with respect to non-discretionary matters unless you provide instructions on how to vote in accordance with the information and procedures provided to you by your broker, bank, or nominee. Plum believes the Proposals presented to Plum Shareholders will be considered non-discretionary and therefore your broker, bank, or nominee cannot vote your Plum Common Shares without your instruction. Your bank, broker, or other nominee can vote your Plum Common Shares only if you provide instructions on how to vote. You should instruct your broker to vote your Plum Common Shares in accordance with directions you provide.
Q: May I change my vote after I have submitted my executed proxy card?
A: Yes. You may change your vote by sending a later-dated, signed proxy card to Plum at the address listed below so that it is received by Plum prior to the Plum Shareholders’ Meeting or by attending the Plum Shareholders’ Meeting online and voting there. You also may revoke your proxy by sending a notice of revocation to Plum, which must be received prior to the Plum Shareholders’ Meeting.
Q: What should I do if I receive more than one set of voting materials?
A: You may receive more than one set of voting materials, including multiple copies of this proxy statement/prospectus and multiple proxy cards or voting instruction forms. For example, if you hold your Plum Common Shares in more than one brokerage account, you will receive a separate voting instruction form for each brokerage account in which you hold Plum Common Shares. If you are a holder of record and your Plum Common Shares are registered in more than one name, you will receive more than one proxy card. Please complete, sign, date, and return each proxy card and voting instruction form that you receive in order to cast your vote with respect to all of your Plum Common Shares.
42
Q: Who can help answer my questions?
A: If you have questions about the Proposals or if you need additional copies of the proxy statement/prospectus or the enclosed proxy card you should contact:
Steven Handwerker, Chief Financial Officer
c/o Plum Acquisition Corp. III
2021 Fillmore St., #2089
San Francisco, California 94115
Email: steven@plumpartners.com
Tel: (929) 529-7125
You may also contact Plum’s proxy solicitor at:
[We expect to engage a proxy solicitation agent and incur customary fees in connection therewith.]
To obtain timely delivery, Plum Shareholders must request the materials no later than five business days prior to the Plum Shareholders’ Meeting.
You may also obtain additional information about Plum from documents filed with the SEC by following the instructions in the section entitled “Where You Can Find Additional Information.”
If you intend to seek redemption of your Plum Public Shares, you will need to send a letter demanding redemption and deliver your Plum Public Shares (either physically or electronically) to the Transfer Agent at least two business days prior to the Plum Shareholders’ Meeting in accordance with the procedures detailed under the question “How do I exercise my redemption rights?” If you have questions regarding the certification of your position or delivery of your Plum Public Shares, please contact:
Continental Stock Transfer & Trust Company
1 State Street, 30th Floor
New York, New York 10004-1561
Attention: Mark Zimkind
Email: mzimkind@continentalstock.com
Q: Who will solicit and pay the cost of soliciting proxies?
A: Plum is soliciting proxies on behalf of the Plum Board. This solicitation is being made by mail but also may be made by telephone, in person or by electronic means. Plum will bear the cost of the solicitation. Plum has engaged [•] to assist in the solicitation of proxies and will pay [•] a fee of $[•], plus disbursements. Plum will reimburse [•] for reasonable and documented out-of-pocket expenses and will indemnify [•] and its affiliates against certain claims, liabilities, losses, damages and expenses. Plum will ask banks, brokers and other institutions, nominees and fiduciaries to forward the proxy materials to their principals and to obtain their authority to execute proxies and voting instructions, and will reimburse such parties for their expenses in forwarding soliciting materials to beneficial owners of Plum Class A Shares and in obtaining voting instructions from those owners. Plum management and Plum’s employees may also solicit proxies by telephone, by facsimile, in person or by electronic means. They will not be paid any additional amounts for soliciting proxies.
43
SUMMARY OF PROXY STATEMENT/PROSPECTUS
This summary highlights selected information contained in this proxy statement/prospectus and does not contain all of the information that is important to you. You should read carefully this entire proxy statement/prospectus, including the annexes and accompanying financial statements of Plum and TRC, to fully understand the proposed Business Combination and the Proposals to be considered at the Plum Shareholders’ Meeting (each as described below). Please see the section entitled “Where You Can Find More Information” elsewhere in this proxy statement/prospectus.
Parties to the Business Combination
Plum
Plum is a blank check company incorporated as a Cayman Islands exempted company on February 5, 2021, for the purpose of effecting a merger, amalgamation, share exchange, asset acquisition, share purchase, reorganization or similar business combination involving Plum and one or more target businesses.
Plum’s securities are traded on the OTC Pink under the ticker symbols “PLMJF,” “PLMUF” and “PLMWF.” In connection with the Closing, the Plum securities will be no longer qualified on the OTC Pink.
The mailing address of Plum’s principal executive office is 2021 Fillmore St., #2089, San Francisco, California 94115, and its telephone number is (929) 529-7125.
TRC
TRC was incorporated under the BCBCA on June 25, 2018. The principal business of TRC is exploration and development of Rare Earth Elements (“REE”).
On July 14, 2021, TRC entered into an assignment and assumption agreement (the “SBQ Assignment Agreement”) with Peak 6891 LLC (“Peak”). Peak is party to an agreement dated June 1, 2021 with Sierra Blanca Quarry, LLC (“SBQ LLC”), Dennis Walker and Becky Dean Walker (the “Original Offtake Agreement”), pursuant to which Peak was granted the rights to acquire certain crushed tailings materials extracted by SBQ LLC from the Sierra Blanca Quarry, located in Hudspeth County in the State of Texas. Pursuant to the SBQ Assignment Agreement, on August 11, 2021, (the “SBQ Closing Date”), Peak assigned all of its rights and obligations under the Original Offtake Agreement to TRC. TRC and SBQ executed a purchase and sale agreement dated July 30, 2021, as amended May 13, 2022 (the “SBQ Offtake Agreement”), with respect to mine tailings from the Sierra Blanca Quarry and agreed to terminate the Original Offtake Agreement. The Peak REE Project found within the Sierra Blanca Complex is located 68 miles southeast of El Paso, Texas. The project is located within the Sierra Blanca Quarry which is currently operational in the production of ballast material for the Union Pacific railway
TRC’s head office, principal address, registered address and records office is Suite 1500-1055 West Georgia Street, Vancouver, BC V6E 4N7. As of August 31, 2023, TRC’s common shares commenced trading on the TSX Venture Exchange (the “TSX-V”). TRC’s common shares are quoted in the United States on the OTC Markets under the symbol “USREF”.
PubCo
PubCo is a British Columbia corporation incorporated on August 8, 2024. PubCo will survive the Plum Amalgamation as PubCo and become the parent company of the amalgamated company resulting from the TRC Amalgamation upon the Closing. PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing, the PubCo Common Shares and PubCo Public Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively.
44
The mailing address of PubCo’s principal place of business is at 2021 Fillmore St., #2089, San Francisco, California 94115, and its telephone number is (929) 529-7125. The mailing address of PubCo’s registered office is 2600 – 1066 West Hastings Street, Vancouver, British Columbia V6E 3X1.
Amalco
Amalco is a British Columbia corporation incorporated on August 8, 2024. It is a wholly owned subsidiary of Plum.
The mailing address of Amalco’s registered office is 2600 – 1066 West Hastings Street, Vancouver, British Columbia V6E 3X1. The mailing address of Amalco is 2021 Fillmore St., #2089, San Francisco, California 94115, and its telephone number is (929) 529-7125.
The Business Combination
On August 22, 2024, Plum, TRC, PubCo, and Amalco, entered into the Business Combination Agreement, pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement, (i) Plum will transfer by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and the Companies Act and domesticate as a British Columbia corporation in accordance with the BCBCA, (ii) Plum will amalgamate with PubCo, with PubCo surviving as PubCo in accordance with the terms of the Plan of Arrangement and (iii) TRC will amalgamate with Amalco, with the amalgamated company becoming a wholly owned subsidiary of PubCo in accordance with the terms of the Plan of Arrangement. For more information, see the section entitled “The Business Combination.”
TRC received the Interim Order on [•], 2025, which provided for the calling and holding of the Plum Shareholders’ Meeting, and the TRC Shareholders’ Meeting and certain other procedural matters. The full text of the Interim Order will be set out in Annex N — “Interim Order” herein. Subject to the terms of the Business Combination Agreement, and provided that the Plum Shareholders’ Approval is obtained at the Plum Shareholders’ Meeting and the TRC Shareholders’ Approval is obtained at the TRC Shareholders’ Meeting in the manner required by the Interim Order, TRC will reattend before the Court for the issuance of the Final Order.
The following diagram illustrates the organizational structure of Plum and TRC immediately prior to the Business Combination:
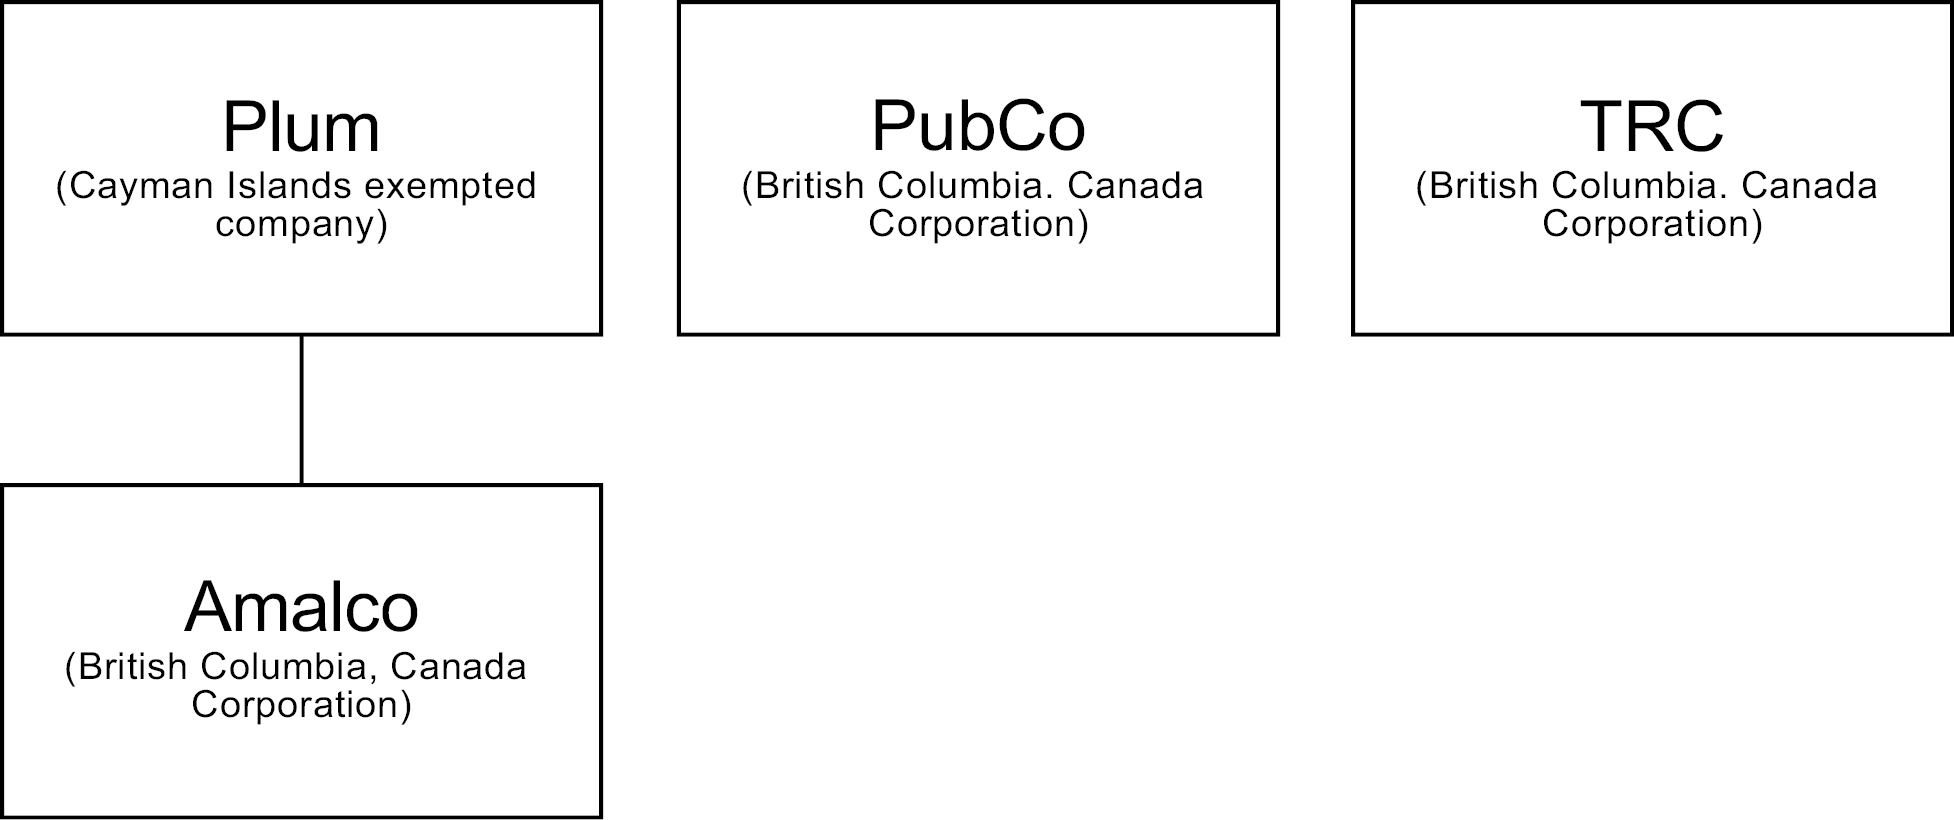
The following diagram illustrates the structure of PubCo immediately following the Business Combination. The percentages shown reflect the voting power and economic interests in PubCo on a combined basis, in each case assuming no redemptions, assuming illustrative redemptions or assuming maximum redemptions. Interests shown exclude (i) 9,416,666 PubCo Common Shares underlying the PubCo Public Warrants, (ii) 2,642,500 PubCo Common Shares underlying the PubCo Private Placement Warrants and Founder Warrants, (iii) the issuance of
45
any shares upon the exercise of TRC Options to purchase up to a total of 2,085,673 PubCo Common Shares, (iv) the issuance of any shares upon the exercise of TRC Warrants to purchase up to a total of 6,406,368 PubCo Common Shares, (v) the issuance of up to a total of 3,104,561 PubCo Common Shares pursuant to TRC RSUs, (vi) the issuance of any shares upon the conversion of TRC Convertible Debt acquire up to a total of 3,918,801 PubCo Common Shares, or (vii) the issuance of 1,188,950 PubCo Common Shares to bankers, in each case that will remain outstanding following the Business Combination. Please see the subsection entitled “The Business Combination — Ownership of PubCo Common Shares After Closing” for additional assumptions used in calculating such percentages.
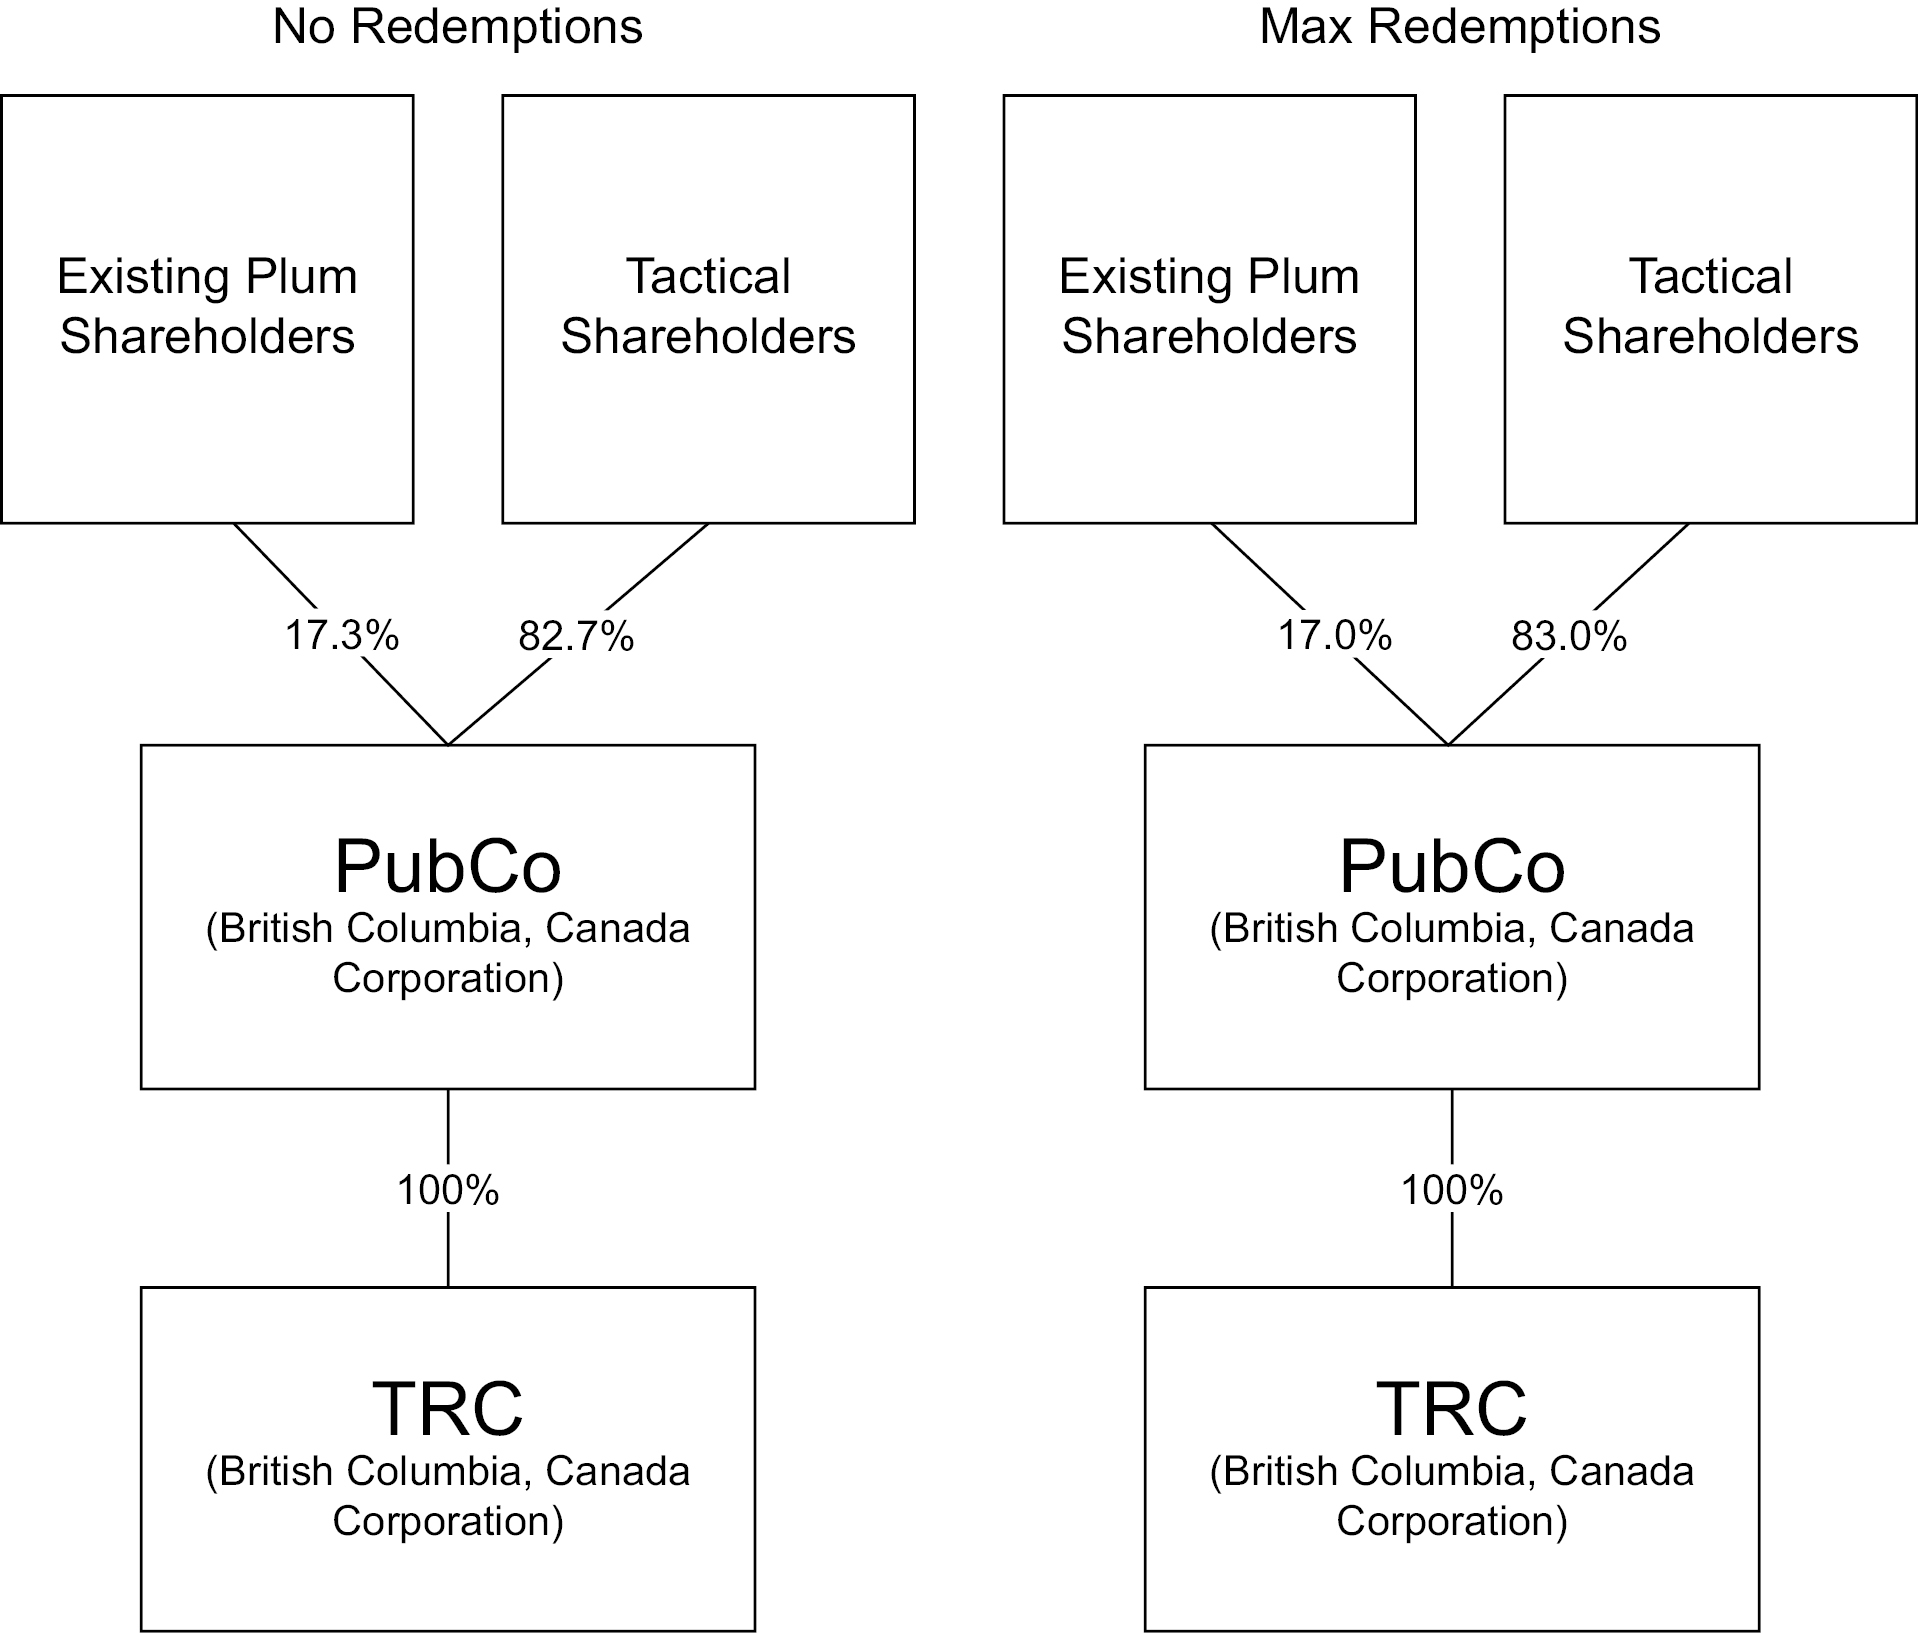
Pursuant to the Plum Amalgamation, which will take place after the Domestication and on the date on which the closing of the Business Combination will occur (the “Closing” and such date the “Closing Date”):
(a) each Plum Unit shall be automatically divided, and the holder thereof shall be deemed to hold one Plum Class A Share, par value $0.0001 per share (a “Plum Class A Share”) and one-third of one Plum Warrant in accordance with the terms of the applicable Plum Unit;
(b) each Plum Class A Share and Plum Class B ordinary share, par value $0.0001 per share (a “Plum Class B Share” and together with the Plum Class A Shares, the “Plum Common Shares”), will be exchanged on a one-for-one basis, for a common share in the authorized share capital of PubCo (a “PubCo Common Share”); and
(c) each Plum Warrant shall automatically be converted into a warrant (each, a “PubCo Assumed Plum Warrant”) to purchase a number of PubCo Common Shares determined in accordance with the terms of such Plum Warrant.
46
On the Closing Date, pursuant to the TRC Amalgamation, among other things:
(a) each TRC Common Share (other than any Cancelled TRC Shares or Dissenting Shares) shall automatically be exchanged for the right to receive a number of PubCo Common Shares equal to the TRC Exchange Ratio (the aggregate of all such PubCo Common Shares, the “Arrangement Consideration Shares”). Any Arrangement Consideration Shares exchanged for TRC Common Shares which were subject to any vesting or forfeiture terms shall continue to be governed by such terms from and after the TRC Amalgamation Effective Time;
(b) each of the Dissenting Shares shall be cancelled and shall thereafter represent only the right to receive the applicable payments set forth in the Plan of Arrangement;
(c) each TRC Option shall be assumed by PubCo and converted into an option to purchase PubCo Common Shares (each, a “Converted TRC Option”), subject to the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such Converted TRC Option shall be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
(d) each TRC RSU shall be assumed by PubCo and converted into a restricted stock unit in respect of PubCo Common Shares (each, a “Converted TRC RSU”), subject to the same terms and conditions as were previously applicable thereto, except that such Converted TRC RSU shall be in respect of a number of PubCo Common Shares equal to the product of (A) the number of shares previously subject to such TRC RSU and (B) the TRC Exchange Ratio;
(e) each TRC Warrant shall automatically be converted into a warrant to purchase PubCo Common Shares (each, a “PubCo Assumed TRC Warrant”), and such PubCo Assumed TRC Warrant shall continue to be governed by the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such PubCo Assumed TRC Warrant shall be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
(f) the TRC Convertible Debenture shall survive the TRC Amalgamation in accordance with the terms thereof (subject to the conversion rights of the holder set forth therein); and
(g) each Amalco Share shall automatically be exchanged for one validly-issued, fully paid and nonassessable common share of TRC.
Dissent Rights.
To the extent available under the BCBCA, any TRC Common Shares that are outstanding immediately prior to TRC Amalgamation Effective Time and that are held by TRC Shareholders who have not voted in favor of the Arrangement nor consented thereto in writing and who have given a notice of election to dissent pursuant to Section 242 of the BCBCA and otherwise complied with all of the provisions of the BCBCA relevant to the exercise and perfection of dissenters’ rights with respect to such TRC Common Shares (the “Dissenting Shares”) shall not be exchanged for, and any such TRC Shareholder shall have no right to receive, any Arrangement Consideration pursuant to the Arrangement, and any holder of Dissenting Shares shall cease to have any of the rights as a shareholder of TRC save for the right to be paid fair value for such holder’s Dissenting Shares in accordance with the Plan of Arrangement. Any TRC Shareholder who prior to TRC Amalgamation Effective Time fails to perfect or validly withdraws a notice of election to dissent or otherwise loses his, her or its rights to payment for their TRC Common Shares pursuant to Section 245 of the BCBCA shall be treated in the same manner as a TRC Shareholder who did not give a notice of election to dissent pursuant to Section 242 of the BCBCA.
47
Conditions to Obligations of Each Party.
The obligations of each of the Parties to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following conditions, any one or more of which may be waived in writing by PubCo, Plum and TRC:
• The Plum Shareholders’ Approval shall have been obtained.
• TRC Shareholders’ Approval shall have been obtained.
• Each of the Interim Order and the Final Order shall have been granted.
• All Regulatory Approvals shall have been obtained and any applicable waiting periods therefor shall have expired or been terminated.
• The proxy/registration statement shall have become effective under the Securities Act, and no stop order suspending the effectiveness of the proxy/registration statement shall be in effect.
• No Governmental Authority shall have enacted any Law or Governmental Order making the Transactions illegal.
• The PubCo Common Shares and the PubCo Warrants shall have been accepted for listing on Nasdaq.
• The distribution of the PubCo Common Shares pursuant to the Arrangement shall be exempt from the prospectus and registration requirements of applicable securities Laws in Canada.
• PubCo shall have paid the outstanding TRC and Plum transaction expenses as required by the Business Combination Agreement and the aggregate outstanding amount due under all working capital loans to Plum from Sponsor.
Conditions to Obligations of PubCo, Plum and Amalco.
The obligations of PubCo, Plum and Amalco to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following additional conditions, any one or more of which may be waived in writing by PubCo, Plum and Amalco:
• Subject to certain limitations and qualifications, each of the representations and warranties of TRC contained in the Business Combination Agreement shall be true and correct as of the Closing Date as if made on that date.
• Each of the covenants of TRC to be performed prior to the Closing Date shall have been performed in all material respects.
• TRC shall have delivered to Plum each of the deliverables required by the Business Combination Agreement.
• No TRC Material Adverse Effect shall have occurred that is continuing.
Conditions to Obligations of TRC.
The obligations of TRC to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following additional conditions, any one or more of which may be waived in writing by TRC:
• Subject to certain limitations and qualifications, each of the representations and warranties of PubCo, Plum and Amalco contained in the Business Combination Agreement shall be true and correct as of the Closing Date as if made on that date.
• Each of the covenants of PubCo, Plum and Amalco to be performed prior to the Closing Date shall have been performed in all material respects.
• No Plum Material Adverse Effect shall have occurred.
48
• PubCo shall have delivered each of the deliverables required by the Business Combination Agreement.
• PubCo shall have deposited with the Depositary the Exchange Fund and the Irrevocable Direction.
• Effective as of the Closing, the directors and officers of PubCo and Amalco shall have resigned.
Termination
The Business Combination Agreement may be terminated and the Transactions abandoned at any time prior to the Closing as follows:
• by mutual written consent of TRC and Plum;
• by written notice from TRC or Plum if the Closing shall not have occurred by July 30, 2025 (the “Agreement End Date”);
• by written notice from TRC or Plum if any Governmental Authority shall have enacted any Governmental Order that has the effect of making consummation of the Transactions illegal;
• by written notice from TRC to Plum if, prior to obtaining the Plum Shareholders’ Approval, there has been a Plum Modification in Recommendation;
• by written notice from Plum to TRC if, prior to obtaining TRC Shareholders’ Approval, there has been a TRC Modification in Recommendation;
• by written notice from TRC or Plum if the Plum Shareholders’ Approval is not obtained at the Plum Shareholders Meeting;
• by written notice from TRC to Plum at any time prior to receipt of TRC Shareholders’ Approval in connection with a TRC Superior Proposal or a TRC Intervening Event;
• by written notice from TRC or Plum if the TRC Shareholders’ Approval shall not have been obtained at TRC Shareholders Meeting;
• by written notice from Plum to TRC if (i) there is any breach of any representation, warranty or covenant of TRC such that any condition to closing would not be satisfied at the Closing, subject to a 30-day period to cure, and (ii) Plum is not in material breach of its representations, warranties or covenants under the Business Combination Agreement; or
• by written notice from TRC to Plum if (i) there is any breach of any representation, warranty or covenant of Plum set forth in the Business Combination Agreement such that any condition to closing would not be satisfied at the Closing, subject to a 30-day period to cure and (ii) TRC is not in material breach of its representations, warranties or covenants under the Business Combination Agreement.
In the event of the valid termination of the Business Combination Agreement, the Business Combination Agreement shall forthwith become void and have no effect, without any liability on the part of either Party or its respective Affiliates, officers, directors, employees, shareholders or other Representatives, other than liability of any Party for any willful and material breach of the Business Combination Agreement occurring prior to such termination, and other than liability for payment of the expenses set forth below.
Expenses.
Each Party shall be responsible for and pay its own expenses incurred in connection with the Business Combination Agreement, including all fees and expenses of its legal counsel, financial advisors, investment bankers, accountants and other advisors; provided, that, if the Closing shall occur, PubCo shall pay the outstanding TRC Transaction Expenses and the outstanding Plum Transaction Expenses. Notwithstanding the foregoing:
• If the Business Combination Agreement is validly terminated by Plum following a TRC Modification in Recommendation or by TRC following a TRC Superior Proposal, then TRC shall pay to Plum within two Business Days after any such termination, a fee equal to the sum of (i) $2,000,000 and (ii) the lesser of $2,500,000 and the reasonable and documented third-party, out-of-pocket fees and expenses incurred
49
and payable by or on behalf of Plum, PubCo or Amalco in connection with the Business Combination Agreement. This termination fee shall constitute liquidated damages under the Business Combination Agreement and, if paid, shall be the sole and exclusive remedy of Plum, PubCo and Amalco against TRC arising out of such termination of the Business Combination Agreement.
• If the Business Combination Agreement is validly terminated by TRC following a Plum Modification in Recommendation, then Plum shall pay to TRC within two Business Days after such termination the sum of (i) $2,000,000 and (ii) the lesser of $2,500,000 and the reasonable and documented third-party, out-of-pocket fees and expenses incurred and payable by or on behalf of TRC in connection with the Business Combination Agreement. This termination fee shall constitute liquidated damages under the Business Combination Agreement shall be the sole and exclusive remedy of TRC against Plum, PubCo and Amalco arising out of such termination of the Business Combination Agreement.
Related Agreements
Sponsor Support Agreement
PubCo, Plum, TRC, Mercury Capital, LLC (“Sponsor”), Alpha Partners Technology Merger Sponsor LLC (“Former Sponsor”), and certain other Plum Shareholders set forth therein (together with Sponsor and Former Sponsor, the “Sponsor Parties”) entered into a voting and support agreement on August 22, 2024 (the “Sponsor Support Agreement”) pursuant to which, among other things, each of the Sponsor Parties agreed to (i) refrain from transferring any of his, her or its Plum Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (ii) vote his, her or its Plum Shares and any additional Plum Shares he, she or it acquires prior to the Plum Shareholders’ Meeting in favor of each of the Plum Shareholder Proposals at the Plum Shareholders’ Meeting, (iii) waive, and not exercise, any rights he, she or it may have to elect to effect a Plum Share Redemption in connection with the Plum Shareholders’ Approval or the Transactions and (iv) waive, and not enforce, any anti-dilution rights he, she or it may have under the Plum Governing Documents in connection with the Transactions. The Sponsor Parties did not receive any consideration for agreeing to waive, and not exercise, any rights he, she or it may have to elect to effect a Plum Share Redemption.
A number of affiliated and unaffiliated investors (the “Former Sponsor Anchors”) are entitled to receive from Sponsor up to 2,030,860 Plum Class B Units (each consisting of one Plum Class B Shares and one-third of a warrant to acquire one Plum Class B Share (collectively, the “Sponsor Incentive Units”)) if they hold a certain number (their “Required Number”) of Plum Class A Shares on the closing date of the Business Combination. If Sponsor transfers any of the Sponsor Incentive Units to parties other than the Former Sponsor Anchors and any of the Former Sponsor Anchors are or become entitled to Plum Class B Units because they hold or held their Required Number at the closing of a business combination, Sponsor shall transfer such number of Plum Class B Units to such Former Sponsor Anchor from its own account. Prior to the Closing, Sponsor shall use its commercially reasonable efforts to consummate the PIPE Investment, including entering into agreements pursuant to which Sponsor shall agree to transfer Sponsor Incentive Units to the counterparties in connection with the concurrent execution by such Persons of PIPE Subscription Agreements. Prior to the Closing, Sponsor may to transfer Sponsor Incentive Units to Plum Public Shareholders in connection with (i) the concurrent execution by such Plum Public Shareholders of agreements not to elect to effect a Plum Share Redemption, or (ii) in the event such Plum Public Shareholders have already elected to effect a Plum Share Redemption, to incentivize such Plum Public Shareholders to unwind or facilitate the unwinding of their respective elections to effect a Plum Share Redemption. At the Closing, Sponsor shall irrevocably forfeit to PubCo for cancellation for no consideration any Sponsor Incentive Units which have not been transferred to the Former Sponsor Anchors, PIPE Investors or Plum Public Shareholders in the circumstanced described above.
TRC Securityholder Support Agreements
PubCo, Plum, TRC and the Key TRC Securityholders have entered into a voting and support agreement on August 22, 2024 (the “TRC Securityholder Support Agreement”) pursuant to which, among other things, each of the Key TRC Securityholders agreed to (a) refrain from transferring any of his, her or its TRC Common Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (b) vote his, her or its TRC Common Shares and any additional TRC Common Shares he, she or it acquires prior to the TRC Shareholders Meeting in favor of each of the TRC Shareholder Proposals, including the TRC Arrangement Resolution, at the TRC Shareholders Meeting and (c) waive, and not exercise, any Dissent Rights he, she or it may have with respect to the Transactions.
50
Registration Rights Agreement
Plum and the Sponsor Parties are parties to a registration rights agreement, dated as of July 27, 2021 (the “Original Registration Rights Agreement”), and, at the Closing, PubCo and the Sponsor Parties shall enter into a registration rights agreement (the “Registration Rights Agreement”) pursuant to which, among other things, (a) PubCo (as successor-in-interest to Plum) and the Sponsor Parties shall terminate the Original Registration Rights Agreement and (b) PubCo shall provide the Sponsor Parties with certain demand and piggyback registration rights with respect to the PubCo Common Shares (and any securities convertible into or exercisable for PubCo Common Shares) to be held by such Persons immediately following the Closing.
Sponsor Parties Lock-up Agreement
PubCo, Plum and the Sponsor Parties have entered into a lock-up agreement (the “Sponsor Parties Lock-Up Agreement”) pursuant to which, among other things, each Sponsor Party agreed that he, she or it shall not transfer any of his, her or its Plum Class B Shares (or any Plum Class A Shares issuable upon conversion thereof, or any securities into which Plum Class B Shares or Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) (“Lock-Up Shares”) until the date that is the day immediately following the six-month anniversary of the completion of the Business Combination (the “Lock-Up Restriction”); provided, however, that following the consummation of the Business Combination, (i) if a Stock Price Level equal to or greater than $15.00 is achieved, the Lock-Up Restriction shall expire with respect to one-third of the Lock-Up Shares held by each such person, (ii) if a Stock Price Level equal to or greater than $20.00 is achieved, the Lock-Up Restriction shall expire with respect to an additional one-third of the Lock-Up Shares held by each such person, and (iii) if a Stock Price Level equal to or greater than $25.00 is achieved, the Lock-Up Restriction shall expire with respect to the last one-third of the Lock-Up Shares held by each such person. For purposes hereof: (x) “Stock Price Level” means the daily volume weighted average closing sale price per share of the Plum Class A Shares as quoted on NASDAQ for any 20 Trading Days within any 30 consecutive Trading Day period and (y) “Trading Day” means any day on which the Plum Class A Shares (or any securities into which Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) are actually traded on the principal securities exchange or securities market on which the Plum Class A Shares (or any securities into which Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) are then traded.
Each Sponsor Party also agreed that he, she or it will not transfer any of his, her or its Private Placement Units, private placement shares, private placement warrants, Founder Units, founder warrants or Plum Class A Shares issued upon conversion or exercise thereof (or any securities into which any of the foregoing are converted or exchangeable pursuant to the Business Combination) until 30 days after the completion of the Business Combination.
PubCo Closing Articles
Pursuant to the terms of the Business Combination Agreement, the PubCo Closing Articles will become the articles of PubCo effective as of the Plum Amalgamation Effective Time. For more information about the PubCo Closing Articles, see the subsection entitled “The Business Combination — Related Agreements.”
Ownership of PubCo Common Shares after Closing
Upon consummation of the Business Combination, the TRC Shareholders and the Plum Shareholders will become PubCo Shareholders.
The issuance of PubCo Common Shares in the Business Combination will dilute the equity interests of Plum Public Shareholders who do not exercise their redemption rights and may adversely affect prevailing market prices for PubCo Common Shares. Plum Public Shareholders who do not exercise their redemption rights may experience dilution to varying degrees in connection with and after the Business Combination, including:
• the issuance of PubCo Common Shares as part of the consideration in connection with the consummation of the Business Combination; and
• the exercise of TRC Warrants.
51
The issuance of PubCo Common Shares in connection with the Business Combination, including through any of the foregoing, could have the following effects for Plum Public Shareholders who elect not to redeem their Public Shares:
• their proportionate ownership interest in TRC will decrease;
• the amount of cash available per share, including for payment of dividends in the future, may decrease;
• the relative voting strength of each previously outstanding Plum Shares will be diminished; or
• the market price of PubCo Common Shares or TRC Warrants, as applicable, may decline.
The following table illustrates varying beneficial ownership levels in TRC, as well as possible sources and extents of dilution for non-redeeming Plum Public Shareholders, assuming no additional redemptions by Plum Public Shareholders and the Maximum Redemption by Plum Public Shareholders. The calculations are based upon an assumed TRC Exchange Ratio of 0.87084460.
Assumptions are as follows:
• Assuming no additional redemption scenario: This presentation assumes that no Public Shareholders exercise redemption rights with respect to their Public Shares in connection with the vote on the Business Combination.
• Assuming Maximum Redemption scenario: This presentation assumes that the Public Shareholders holding approximately 14.9% of the Public Shares exercise redemption rights with respect to their Public Shares. This scenario assumes that 151,833 Public Shares are redeemed for an aggregate redemption payment of approximately $1,711,089 plus a pro rata portion of interest accrued on the Trust Account (net of taxes payable).
|
No |
% |
Maximum |
% |
|||||||||
|
Plum Public Shareholders(1) |
|
1,016,833 |
1.3 |
% |
|
865,000 |
1.2 |
% |
||||
|
Sponsor and Former Sponsor(2)(3) |
|
6,731,320 |
8.3 |
% |
|
6,731,320 |
8.3 |
% |
||||
|
Parties to Non-redemption Agreements(3) |
|
331,180 |
0.4 |
% |
|
331,180 |
0.4 |
% |
||||
|
Plum Public Warrants(4) |
|
9,416,666 |
11.6 |
% |
|
9,416,666 |
11.6 |
% |
||||
|
Plum Founder Warrants and Private Placement Warrants(5) |
|
2,642,500 |
3.3 |
% |
|
2,642,500 |
3.3 |
% |
||||
|
Sponsor Warrants for Working Capital Note(6) |
|
969,911 |
1.2 |
% |
|
969,911 |
1.2 |
% |
||||
|
TRC public shareholders(7) |
|
35,073,456 |
43.2 |
% |
|
35,073,456 |
43.3 |
% |
||||
|
TRC option holders(8) |
|
2,085,673 |
2.6 |
% |
|
2,085,673 |
2.6 |
% |
||||
|
TRC RSUs(9) |
|
3,104,561 |
3.8 |
% |
|
3,104,561 |
3.8 |
% |
||||
|
TRC Warrantholders(10)(11) |
|
6,406,368 |
7.9 |
% |
|
6,406,368 |
7.9 |
% |
||||
|
TRC Convertible Debt(11) |
|
3,918,801 |
4.8 |
% |
|
3,918,801 |
4.8 |
% |
||||
|
Bank Shares(12) |
|
1,188,950 |
1.5 |
% |
|
1,188,950 |
1.5 |
% |
||||
|
TRC Incentive Plan(13) |
|
8,229,736 |
10.1 |
% |
|
8,214,553 |
10.1 |
% |
||||
|
Total |
|
81,115,955 |
|
|
80,948,939 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted(14) |
$ |
7.43 |
|
$ |
7.39 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted (excluding shares issued to redeemable shareholders)(15) |
$ |
7.44 |
|
$ |
7.40 |
|
||||||
____________
(1) Outstanding share numbers take into account the redemptions of 28,098,167 Plum Class A Shares that occurred in connection with extensions of Plum’s business combination deadline.
(2) On December 27, 2023, Plum, the Former Sponsor, and Sponsor entered into a purchase agreement (the “Purchase Agreement”), pursuant to which Sponsor (i) purchased 3,902,648 founder units of Plum from the Former Sponsor, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B ordinary share, which founder units are subject to forfeiture in certain circumstances, and (ii) became entitled to 70% of the 2,030,860 founder units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the
52
extent such founder units are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of Plum’s initial business combination. Pursuant to the Amended Purchase Agreement, the Former Sponsor shall retain 665,000 Class A private placement units and 1,128,992 Class B founder units. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(3) At Closing, 331,180 Ordinary Shares that would have otherwise been issued to the Sponsor in exchange for such number of shares Plum Class A Shares will instead to be issued to the parties to whom the Sponsor has agreed to transfer such shares. The agreement to transfer such shares was made in consideration of each of the transferees agreeing not to redeem their Plum Class A Shares on connection with the extension of Plum’s business combination deadline.
(4) The Plum Public Warrants are exercisable at $11.50 per share.
(5) The 2,354,166 Plum Founder Warrants and 288,334 Plum Private Warrants are exercisable at $11.50 per share. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(6) Assumes $1,454,867 is outstanding on the convertible note held by the Sponsor, convertible into PubCo Warrants at closing at $1.50 per Warrant.
(7) 35,674,480 TRC Common Shares are currently outstanding.
(8) 2,395,000 options to purchase TRC Common Shares are currently outstanding, exercisable at C$0.10 per share.
(9) 3,565,000 RSUs to acquire TRC Common Shares are currently outstanding, and will vest upon the closing of the Business Combination.
(10) 2,856,500 Warrants to purchase TRC Common Shares are currently outstanding, exercisable at C$2.50 per share.
(11) C$200,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,000,000 TRC Common Shares plus 2,000,000 warrants to purchase 2,000,000 TRC Common Shares at C$0.15 per share. C$500,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,500,000 TRC Common Shares plus 2,500,000 warrants to purchase 2,500,000 TRC Common Shares at C$0.20 per share. Any accrued and unpaid interest may, in TRC’s sole discretion, be paid in cash or in units (consisting of one TRC Common Share and one warrant to purchase a TRC Common Share) at a conversion price equal to the last closing market price of TRC’s common shares on the TSX-V immediately prior to such conversion date, subject to the policies of the TSX-V.
(12) TRC will be obligated to issue 1,188,950 shares to its investment bankers in connection with the Transactions.
(13) TRC’s board of directors has approved the Incentive Plan providing for the issuance of ten percent of the outstanding PubCo Common Shares, on a fully diluted basis, immediately following the closing, plus 1,000,000 shares.
(14) Calculation of implied per share value assumes an enterprise value of $602.5 million of PubCo upon consummation of the Business Combination and a fully diluted share count with no redemptions of 81,115,955.
(15) Calculation of implied per share value assumes an enterprise value of $599.2 million of PubCo upon consummation of the Business Combination and a fully diluted share count with max redemptions of 80,948,939.
Assuming no further redemptions of the Plum Shares, the combined company would have a pro forma valuation of approximately $811,159,550 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Assuming maximum redemptions of the Plum Shares issued in our IPO, the combined company would have a pro forma valuation of approximately $809,489,390 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
The Sponsor will not receive any direct compensation for services rendered in connection with the Business Combination. Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting. Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•]. Since all Founder Units have been issued, this compensation will not result in a material dilution to the equity interests of non-redeeming shareholders upon consummation of the Business Combination.
Plum has borrowed certain amounts from the Sponsor pursuant to (i) a promissory note, as amended (the “Working Capital Note”), which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants (the “Sponsor Warrants for Working Capital Note”) at a price of $1.50 per warrant, to be issued at Closing, and (ii) a promissory note, as amended,
53
which provides for up to $100,000 in working capital loans, which shall be repaid in cash on the earlier of (i) consummation of the Plum’s initial merger, share exchange, asset acquisition, share purchase, recapitalization, reorganization or similar business combination with one or more businesses or entities, (ii) the date of the liquidation of Plum or (iii) 270 calendar days. The warrants that may be issuable pursuant to the promissory note to the Sponsor at Closing as reimbursement, if exercised, would result in the issuance of up to 1,466,667 additional Plum Class A Ordinary Shares upon Closing. See “Notes to Unaudited Pro Forma Condensed Consolidated Financial Information” for further information on the dilution. Assuming that all Plum Public Warrants and Plum Private Placement Warrants are exercised, this compensation will not result in a material dilution of the equity interests of non-redeeming Plum Public Shareholders. Please see the subsection entitled “The Business Combination — Total PubCo Common Shares to Be Issued in the Business Combination” and the section entitled “Unaudited Pro Forma Condensed Consolidated Financial Information” for more information.
The figures in the above table are presented only as illustrative examples and are based on assumptions described above, which may be different from the actual amount of redemptions in connection with the Business Combination.
The following table presents the net tangible book value per share at various redemption levels assuming various sources of material probable dilution (but excluding the effects of the Business Combination transaction itself).
|
Assuming |
Assuming |
|||||||||||
|
Total |
Tangible |
Total |
Tangible |
|||||||||
|
Plum net tangible book value per share as of December 31, 2024 (unadjusted) |
151,833 |
|
(8.91 |
) |
151,833 |
|
(8.91 |
) |
||||
|
Accretion (Dilution) of Plum Shareholders assuming the Redemption of Public Shares |
151,833 |
|
(8.91 |
) |
nil |
|
nil |
|
||||
|
Accretion (Dilution) of Plum Shareholders assuming the Exercise of Public Warrants(2) |
9,568,499 |
|
11.32 |
|
9,416,666 |
|
11.17 |
|
||||
|
Accretion (Dilution) of Plum Shareholders assuming the Issuance and Exercise of Warrants pursuant to the Working Capital Note(3) |
10,538,410 |
|
11.21 |
|
10,386,577 |
|
11.20 |
|
||||
|
Accretion (Dilution) of Plum Shareholders assuming the Exercise of Private Placement Warrants and Founder Warrants(4) |
22,699,860 |
|
11.36 |
|
22,548,027 |
|
11.36 |
|
||||
|
Initial offering price of Plum |
$ |
10.00 |
|
$ |
10.00 |
|
||||||
|
Pro forma net tangible book value per share from dilutive securities and other related events, excluding the Business Combination(5) |
$ |
11.36 |
|
$ |
11.36 |
|
||||||
|
Dilution to non-redeeming shareholders |
$ |
1.36 |
|
$ |
1.36 |
|
||||||
____________
(1) Assumes that the Public Shareholders holding approximately 14.9% of the Public Shares exercise redemption rights with respect to their Public Shares.
(2) Assumes 9,416,666 Public Warrants are exercised at an exercise price of $11.50 per share.
(3) Assumes 969,911 Plum Warrants are issued and exercised pursuant to the Working Capital Note with a balance of $1,454,867 at a price of $1.50 per warrant and exercise price of $11.50 per share.
(4) Assumes 2,354,166 Plum Founder Warrants and 288,334 Plum Private Warrants are exercised at an exercise price of $11.50 per share.
(5) Assuming no redemptions and accounting for all accretion (dilution), Plum’s valuation at or which the potential dilution results in the amount of the non-redeeming shareholders’ interests per share being at least $10.00 per share would be $[•]. Assuming max redemptions and accounting for all accretion (dilution), Plum’s valuation at or which the potential dilution results in the amount of the non-redeeming shareholders’ interests per share being at least $10.00 per share would be $[•].
Description of PubCo Securities
If the Business Combination is successfully completed, TRC Shareholders and Plum Shareholders will become PubCo Shareholders, and their rights as PubCo Shareholders will be governed by PubCo’s organizational documents adopted at the Closing and the laws of the Province of British Columbia, Canada. Please see the section entitled “Description of PubCo Securities” elsewhere in this proxy statement/prospectus for additional information.
54
The TRC Board’s Reasons for Approval of the Business Combination
After careful consideration, the TRC Board unanimously recommends that TRC Shareholders vote “FOR” the approval of the Business Combination Proposal. Set forth below is a summary of TRC Board’s reasons for approval of the Business Combination.
The TRC Board believes that the domestic REE opportunity presented by the Peak Project will resonate well with investors in the larger United States Market. Subject to Nasdaq listing approval, the Business Combination would represent an uplisting from the TSX-V to Nasdaq for TRC. TRC’s ability to raise capital is currently restricted by its lack of coverage and limited float, as well as by its limited access to institutional investors. The Business Combination represents an opportunity for TRC to raise capital, receive additional coverage and gain higher visibility among retail investors and large institutional investors. TRC management will retain full operational and managerial control of PubCo, and existing TRC shareholders will retain majority voting control of PubCo. A potential listing on the Nasdaq will provide TRC’s long term equity holders with increased liquidity and additional opportunities.
TRC evaluated numerous different opportunities to raise growth capital and continue to fund and expand its business operations. The TRC Board determined, based on the terms of the Business Combination, its review of letters of intent from numerous other potential business combination partners, the advice of its professional advisors, and a thorough canvassing of other financing opportunities reasonably available to TRC, that the proposed Business Combination represents the best potential option fund the short and long term growth of the company. Please see the subsection entitled “The Business Combination — The TRC Board’s Reasons for the Approval of the Business Combination.”
The Plum Board’s Reasons for Approval of the Business Combination
After careful consideration, the Plum Board unanimously recommends that Plum Shareholders vote “FOR” the approval of the Business Combination Proposal. The Plum Board did not retain an unaffiliated representative to act solely on behalf of the Plum Public Shareholders for negotiating the terms of the Business Combination Agreement on their behalf and/or preparing a report concerning the approval of the Business Combination. For a more complete description of the Plum Board’s reasons for the approval of the Business Combination and the unanimous recommendation of the Plum Board, see the subsection entitled “The Business Combination — Plum Board’s Reasons for Approving the Business Combination.”
Satisfaction of 80% Test
It is a requirement under the Plum Articles and NASDAQ listing requirements that the business or assets acquired in an Initial Business Combination have a fair market value equal to at least 80% of the balance of the funds in the Trust Account (excluding the deferred underwriting discounts and commissions and taxes payable on the income earned on the Trust Account) at the time of the execution of a definitive agreement for an Initial Business Combination. In connection with its evaluation and approval of the Business Combination, the Plum Board determined that the fair market value of TRC represents at least 80% of the net assets of Plum held in the Trust Account.
Extraordinary and General Meeting of Plum Shareholders
Date, Time and Place
The Plum Shareholders’ Meeting will be held both in person on [•], 2025 at 10:00 a.m., Eastern Time, virtually via live webcast at https://www [•], pursuant to the procedures described in this proxy statement/prospectus to consider and vote upon the Proposals.
Proposals
At the Plum Shareholders’ Meeting, Plum Shareholders will be asked to consider and vote upon the following Proposals:
• The Domestication Proposal — To approve, by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and Cayman Islands Companies Act (As Revised) (the “Companies Act”) and the
55
domestication of Plum (the “Domestication”) as a British Columbia corporation in accordance with the applicable provisions of the Business Corporations Act (British Columbia) (the “BCBCA”), including the adoption of the Domestication Articles (the “Domestication Proposal” or “Proposal No. 1”);
• Business Combination Proposal — To approve, by Ordinary Resolution, the Business Combination Agreement, dated as of August 22, 2024 (as may be amended, supplemented or otherwise modified from time to time, the “Business Combination Agreement” and the transactions contemplated thereby, collectively, the “Business Combination”) by Plum, Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum (“Amalco”), Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia (“PubCo”), and Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia (“TRC”), including the Arrangement Resolution pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement attached hereto as Annex B, (i) Plum shall effect the Domestication, (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation (the “Business Combination Proposal” or “Proposal No. 2”). A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A.
• Advisory Organization Documents Proposals — To approve on a non-binding advisory basis, by Ordinary Resolution, the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately in accordance with U.S. Securities and Exchange Commission guidance (the “Advisory Organizational Documents Proposals” or “Proposal No. 3”). The full text of the PubCo Closing Articles are attached to the accompanying proxy statement/prospectus as Annex E. Proposal No. 3 is separated into sub-proposals submitted to Plum Shareholders to approve on a non-binding advisory basis, by Ordinary Resolution, those governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights as described in the following paragraphs (a)-(d):
(a) the proposed PubCo Closing Articles would change the authorized share capital from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal or par value of $0.0001 each, to an unlimited number of PubCo Common Shares (the “Authorized Capital Proposal” or “Proposal No. 3A”);
(b) the proposed PubCo Closing Articles would reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting (the “Quorum Proposal” or “Proposal No. 3B”);
(c) the proposed PubCo Closing Articles would change the name of the company from “Plum III Merger Corp.” to “Tactical Resources Corporation” (the “Name Change Proposal” or “Proposal No. 3C”); and
(d) the proposed PubCo Closing Articles would not include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters (the “Other Matters Proposal” or “Proposal No. 3D” and, together with the Authorized Capital Proposal, the Quorum Proposal and the Name Change Proposal, the “Sub-Proposals”);
• Incentive Plan Proposal — To approve, by Ordinary Resolution, for the purposes of complying with the rules of the Nasdaq Stock Market, the issuance of PubCo Common Shares pursuant to the PubCo Omnibus Equity Incentive Plan (the “Incentive Plan Proposal” or “Proposal No. 4”). A copy of the Incentive Plan is attached to this proxy statement/prospectus as Annex K;
• Adjournment Proposal — If put to Plum Shareholders for a vote, a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient
56
votes for, or otherwise in connection with, the approval of the foregoing proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals (the “Adjournment Proposal” or “Proposal No. 5” and, together with the Domestication Proposal, the Business Combination Proposal, the Incentive Plan Proposal and the Advisory Organizational Documents Proposals, the “Proposals”). If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Voting Power; Record Date
Only Plum Shareholders of record at the close of business on [•], 2025, the record date for the Plum Shareholders’ Meeting, will be entitled to vote at the Plum Shareholders’ Meeting. In respect of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal, each Plum Shareholder is entitled to one vote for each Plum Common Shares registered in its name as of the close of business on the record date. If a Plum Shareholder’s Plum Common Shares are held in “street name” or are in a margin or similar account, such shareholder should contact its broker, bank or other nominee to ensure that votes related to the shares beneficially owned by such shareholder are properly counted. On the record date, there were 8,079,333 Plum Common Shares outstanding, of which 1,016,833 are Plum Public Shares and 7,062,500 are Plum Class B Shares held by Sponsor and Plum’s independent directors.
Proxy Solicitation
Proxies may be solicited by mail but also may be made by telephone, in person or by electronic means. Plum has engaged [•] to assist in the solicitation of proxies. If a Plum Shareholder grants a proxy, it may still vote its shares online if it revokes its proxy before the Plum Shareholders’ Meeting. A shareholder may also change its vote by submitting a later-dated proxy as described in the section entitled “Extraordinary General Meeting of Plum Shareholders — Revoking Your Proxy.”
Quorum and Required Vote for Proposals for the Plum Shareholders’ Meeting
A quorum of Plum Shareholders is necessary to hold a valid meeting. A quorum will be present at the Plum Shareholders’ Meeting if one or more shareholders holding at least a majority of the paid up voting share capital of Plum attend virtually or in person or are represented by proxy at the Plum Shareholders’ Meeting. Abstentions will count as present for the purposes of establishing a quorum.
Approval of the Domestication Proposal requires the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of not less than two thirds (662⁄3%) of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. The Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal require the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of a majority of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. Accordingly, a Plum Shareholder’s failure to vote by proxy or to vote online at the Plum Shareholders’ Meeting will not, if a valid quorum is established, have any effect on the outcome of any vote on any of the Proposals. Abstentions and broker non-votes, while considered present for the purposes of establishing a quorum, will not count as votes cast at the Plum Shareholders’ Meeting (assuming a quorum is present).
The Closing is conditioned on the approval of the Domestication Proposal and the Business Combination Proposal at the Plum Shareholders’ Meeting. The Advisory Organizational Documents Proposals are non-binding and are not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. The Adjournment Proposal is not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
57
Recommendation to Plum Shareholders
The Plum Board believes that each of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposal, the Incentive Plan Proposal and the Adjournment Proposal (if put) is in the best interests of Plum and recommends that Plum Shareholders vote “FOR” each Proposal being submitted to a vote of the Plum Shareholders at the Plum Shareholders’ Meeting.
When you consider the unanimous recommendation of the Plum Board in favor of approval of these Proposals, you should keep in mind that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, your interests as a shareholder. Please see the subsection entitled “The Business Combination — Interests of Certain Persons in the Business Combination.”
Vote of the Sponsor Parties
Pursuant to the Sponsor Support Agreement entered into in connection with the Business Combination, each of the Sponsor Parties agreed to vote any Plum Common Shares owned by them in favor of an Initial Business Combination. Pursuant to the Sponsor Support Agreement, the Sponsor Parties agreed, effective concurrently with the execution and delivery of the Business Combination Agreement, that Sponsor will be prohibited from voting any Plum Class A Shares purchased by Sponsor following Plum’s public announcement of Plum’s intention to engage in the Transactions for or against the Transactions. The Sponsor Support Agreement applies to Sponsor Parties as it relates to the Plum Founder Shares and the requirement to vote all of the Plum Founder Shares in favor of the Business Combination Proposal. As of the record date, the Sponsor Parties own 7,062,500 Plum Founder Shares, representing approximately 87.4% of the Plum Common Shares then outstanding and entitled to vote at the Plum Shareholders’ Meeting. The Sponsor Parties have agreed to waive any redemption rights with respect to Plum Class A Shares purchased in the Plum IPO or in the aftermarket, in connection with the Business Combination. Additionally, pursuant to the Sponsor Parties are not entitled to redemption rights with respect to any Plum Founder Shares held by them in connection with the consummation of the Business Combination or upon Plum’s liquidation. The Plum Founder Shares will be worthless if no Business Combination is effected by Plum by the Deadline Date. However, the Sponsor Parties are entitled to redemption rights upon Plum’s liquidation with respect to any Plum Class A Shares they may own.
Interests of Certain Persons in the Business Combination
In considering the unanimous recommendation of the Plum Board to vote in favor of the Business Combination, Plum Public Shareholders should be aware that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, those of other Plum Public Shareholders generally. Plum’s directors were aware of and considered these interests, among other matters, in evaluating the Business Combination, and in recommending to Plum Shareholders that they approve the Business Combination. Plum Shareholders should take these interests into account in deciding whether to approve the Business Combination. These interests include, among other things:
• Pursuant to the Plum Articles, the Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares and have agreed to waive redemption rights with respect to any Plum Public Shares held by them in connection with the consummation of the Initial Business Combination. Additionally, Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares held by them if Plum fails to consummate the Initial Business Combination by July 30, 2025, or such later date as approved by Plum’s shareholders. If Plum does not complete the Initial Business Combination within such applicable time period, the proceeds of the sale of the Plum Private Placement Warrants held in the Trust Account will be used to fund the redemption of the Plum Public Shares, and the Plum Private Placement Warrants will expire without the receipt of any value by the holders of such warrants. Since the Sponsor Parties directly or indirectly own Plum Common Shares and Plum Private Placement Warrants, Plum management may have a conflict of interest in determining whether a particular target business is an appropriate business with which to effectuate the Initial Business Combination;
58
• The fact that Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•];
• The fact that given the differential in the purchase price that Sponsor paid for the Plum Founder Shares as compared to the price of the Plum Units sold in the Plum IPO and the 3,902,648 PubCo Common Shares that Sponsor will receive upon conversion of the Plum Founder Shares in connection with the Business Combination, Sponsor and its affiliates may earn a positive rate of return on their investment even if the PubCo Common Shares trade below the price initially paid for the Plum Units in the Plum IPO and the Plum Public Shareholders experience a negative rate of return following the completion of the Business Combination;
• The fact that Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting;
• The fact that certain members of Plum management collectively own, directly or indirectly, a material interest in Sponsor;
• Sponsor and Plum management may have a conflict of interest with respect to evaluating a business combination and financing arrangements as Plum may obtain loans from Sponsor or an affiliate of Sponsor or any of Plum management to finance transaction costs in connection with the Initial Business Combination;
• The Plum Articles provide that Plum renounces any interest or expectancy in, or in being offered an opportunity to participate in, any potential transaction or matter which may be a corporate opportunity for any member of Plum management on the one hand, and Plum, on the other hand, or the participation of which would breach any existing legal obligation, under applicable law or otherwise, of a member of Plum management to any other entity. Plum is not aware of any such corporate opportunities not being offered to Plum and does not believe that waiver of the corporate opportunities doctrine has materially affected Plum’s search for an acquisition target or will materially affect Plum’s ability to complete an Initial Business Combination;
• If the Trust Account is liquidated, including in the event Plum is unable to complete an Initial Business Combination within the required time period, Sponsor has agreed to indemnify Plum to ensure that the proceeds in the Trust Account are not reduced below $10.00 per Plum Public Share, or such lesser amount per Plum Public Share as is in the Trust Account on the liquidation date, by the claims of (a) any third party (other than Plum’s independent public accountants) for services rendered or products sold to Plum or (b) a prospective target business with which Plum has entered into a letter of intent, confidentiality or other similar agreement or business combination agreement, but only if such a third party or target business has not executed a waiver of all rights to seek access to the Trust Account;
• The fact that the Company has borrowed certain amounts from the Sponsor pursuant to a promissory note which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants at a price of $1.50 per warrant, to be issued at Closing;
• The fact that Sponsor will benefit from the completion of an Initial Business Combination and may be incentivized to complete an acquisition of a less favorable target company or on terms less favorable to Plum Shareholders rather than liquidate;
59
• The fact that PubCo will indemnify Sponsor and its affiliates and their respective present and former directors and officers for a period of six years from the Closing, in connection with any claim, action, suit, proceeding or investigation arising out of or pertaining to the Business Combination and Sponsor’s ownership of Plum Securities or its control or ability to influence Plum; and
• The terms and provisions of the Related Agreements as set forth in detail under the subsection entitled “The Business Combination — Related Agreements.”
In addition, members of TRC’s board of directors, management and various service providers of TRC have numerous contractual relationships with TRC of which the TRC board of directors was aware when it approved TRC entering into the Business Combination Agreement. Therefore, these individuals may have conflicts of interest in entering into and negotiating the terms of the Business Combination Agreement. For a complete description of these relationships, see “Certain Relationships and Related Transactions — TRC Relationships and Related Party Transactions”.
The table set forth below summarizes the existing interests in Plum private placement securities and the anticipated interests of Former Sponsor, Sponsor, Plum management, and the lender under a subscription agreement in PubCo as of Closing along with the value of such interests based on (i) in the case of Sponsor’s and Plum management’s interests, the closing price of the Plum Public Warrants and Plum Class A Shares as of [•], 2025, which would be lost if an Initial Business Combination is not completed by Plum by the Deadline Date, and (ii) the transaction value:
|
Name of Holder |
Type of |
Total |
Number of |
Number of |
Value of |
Number of |
Number of |
Value of |
|||||||||
|
Mercury Capital, |
Sponsor |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Alpha Partners Technology Merger Sponsor, LLC(2) |
Former Sponsor |
$ |
6,675,000 |
665,000 |
221,667 |
1,128,992 |
376,331 |
||||||||||
|
Palmeira Investment |
Lender to Sponsor |
$ |
750,000 |
0 |
0 |
637,500 |
0 |
||||||||||
|
Kanishka Roy(4) |
CEO & |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Steven Handwerker |
CFO |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Hume Kyle |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Alan Black |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
David Sable |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
____________
(1) On December 27, 2023, Plum, Alpha Partners Technology Merger Sponsor, LLC, and Mercury Capital, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which Mercury Capital, LLC the Sponsor (i) purchased 3,902,648 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B share, and (ii) became entitled to 70% of the 2,030,860 Founder Units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such Founder Units are not allocated to investors who hold and do not redeem their Class A Shares of Plum at the time of Plum’s initial business combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(2) Alpha Partners Technology Merger Sponsor, LLC paid an aggregate of $25,000 for 7,187,500 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B share, 125,000 of which were forfeited due to only a partial exercise of the over-allotment option. Additionally, Alpha Partners Technology Merger Sponsor, LLC purchased 665,000 private placement units at an aggregate price of $6,650,000. On December 27, 2023, Alpha Partners Technology Merger Sponsor, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which they sold 3,902,648 Founder Units to Mercury Capital, LLC, and put 2,030,860 Founder Units into escrow, of which they are entitled to 30% of the Founder Units in Escrow if they are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of the Company’s initial Business Combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(3) Palmeira Investment Limited and Mercury Capital, LLC are party to a subscription agreement, dated January 3, 2024, pursuant to which Mercury Capital, LLC may raise funds to pay for extension payments and working capital on behalf of Plum Acquisition Corp. III. Pursuant to the terms of the subscription agreement, Mercury Capital, LLC will forfeit 0.85 Class B Shares for every $1.00 loaned under the agreement and cause Plum Acquisition Corp. III to issue such number of
60
shares forfeited to Palmeira Investment Limited upon closing of the business combination. As of Mercury Capital LLC’s last drawdown under the subscription agreement, Palmeira Investment Limited had loaned $750,000 to Mercury Capital, LLC under the subscription agreement.
(4) Kanishka Roy serves as manager for Mercury Capital, LLC and may be deemed to beneficially own shares held by Mercury Capital, LLC by virtue of his control over Mercury Capital, LLC. Mr. Roy disclaims beneficial ownership of such shares other than to the extent of his pecuniary interest in such shares.
Redemption Rights
Pursuant to the Plum Articles, a Plum Public Shareholder may request that PubCo redeem all or a portion of the PubCo Common Shares it receives in exchange for its Plum Public Shares for cash if the Business Combination is consummated. The redemption will take place following the TRC Amalgamation Effective Time and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. As a Plum Public Shareholder, you will be entitled to exercise your redemption rights if you:
(a) hold Plum Public Shares, or if you hold Plum Units, you elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising your redemption rights;
(b) submit a written request to Continental Stock Transfer & Trust Company, the Transfer Agent, in which you (i) request to exercise your redemption rights with respect to all or a portion of your Plum Public Shares for cash, and (ii) identify yourself as the beneficial holder of the Plum Public Shares and provide your legal name, phone number and address; and
(c) deliver your Plum Public Shares to the Transfer Agent, physically or electronically through DTC.
Holders must complete the procedures for electing to redeem their Plum Public Shares in the manner described above prior to 10:30 a.m., Eastern Time, on [•], 2025 (two business days before the Plum Shareholders’ Meeting) in order for their shares to be redeemed.
Holders of Plum Units must elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising their redemption rights with respect to the Plum Public Shares. If Plum Public Shareholders hold their Plum Units in an account at a brokerage firm or bank, such Plum Public Shareholders must notify their broker or bank that they elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants, or if a holder holds Plum Units registered in its own name, the holder must contact Continental Stock Transfer & Trust Company, the Transfer Agent, directly and instruct it to do so. The redemption rights include the requirement that a holder must identify itself to Plum in order to validly exercise its redemption rights. Plum Public Shareholders may elect to exercise their redemption rights with respect to their Plum Public Shares even if they vote “FOR” the Business Combination Proposal. If the Business Combination is not consummated, the Plum Public Shares will be returned to the respective holder, broker or bank. If the Business Combination is consummated, and if a Plum Public Shareholder properly exercises its redemption rights with respect to all or a portion of the Plum Public Shares that it holds and timely delivers its shares to the Transfer Agent, PubCo will redeem the related PubCo Common Shares for a per share price, payable in cash, equal to the pro rata portion of the Trust Account, including interest earned on the fund held in the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination. For illustrative purposes, as of [•], 2025, this would have amounted to approximately $[•] per issued and outstanding Plum Public Share. If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation, and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. Please see the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” elsewhere in this proxy statement/prospectus for a detailed description of the procedures to be followed if you wish to exercise your redemption rights with respect to your Plum Public Shares.
Certain Information Relating to PubCo
PubCo/PubCo Board Before the Business Combination
Prior to the consummation of the Plum Amalgamation, the PubCo Board consists of Kanishka Roy and Steven Handwerker. In connection with the Amalgamations, the members of the TRC Board will become the members of the PubCo Board.
61
PubCo Board and Executive Officers Following the Business Combination
The executive officers and directors of PubCo following the TRC Amalgamation will be as follows:
|
Name |
Age |
Position |
||
|
Ranjeet Sunder |
58 |
Chief Executive Officer and Director |
||
|
Kuljit Basi |
41 |
President, Executive Chairman and Director |
||
|
Alnesh Mohan |
53 |
Chief Financial Officer |
||
|
Matthew Chatterton |
44 |
Director |
||
|
Manavdeep Mukhija |
38 |
Director |
||
|
J. Garry Clark |
64 |
Director |
Please see the section entitled “Management of PubCo After the Business Combination” elsewhere in this proxy statement/prospectus for biographies and additional information.
Listing of PubCo Common Shares and PubCo Warrants on the NASDAQ
PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of the NASDAQ. It is anticipated that upon the Closing the PubCo Common Shares and PubCo Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively.
Delisting of Plum Common Stock and Deregistration of Plum
Plum and TRC anticipate that, following consummation of the Business Combination, the Plum Class A Shares, Plum Units and Plum Warrants will be no longer qualified on the OTC Pink, and Plum will be deregistered under the Exchange Act.
Comparison of Corporate Governance and Shareholder Rights
There are certain differences in the rights of Plum Shareholders prior to the Business Combination and the rights of PubCo Shareholders after the Business Combination. Please see the section entitled “Comparison of Corporate Governance and Shareholder Rights” elsewhere in this proxy statement/prospectus for additional information.
The PubCo Closing Articles differ materially from the Plum Articles. The following table sets forth a summary of the principal differences between the Plum Articles and the PubCo Closing Articles. This summary is qualified by reference to the complete text of the Plum Articles, attached to this proxy statement/prospectus as Annex M, and the complete text of the form of PubCo Closing Articles, which are attached to this proxy statement/prospectus as Annex E. All shareholders are encouraged to read the PubCo Closing Articles in their entirety for a more complete description of its terms. Additionally, as the Plum Articles are governed by the Cayman Islands law and the PubCo Closing Articles will be governed by the BCBCA, we encourage shareholders to carefully consult the information set out under this section, “Proposal No. 3 — The Charter Proposal” and “Comparison of Corporate Governance and Shareholder Rights.”
|
Plum Articles |
PubCo Closing Articles |
|||
|
Governing Statute |
The Companies Act (As Revised) of the Cayman Islands. |
Business Corporations Act (British Columbia) |
||
|
Corporate Name |
Plum Acquisition Corp. III |
Plum III Merger Corp. |
||
|
Authorized Capital |
200,000,000 Class A ordinary shares, 20,000,000 Class B ordinary shares, and 1,000,000 preference shares, each with a par value of $0.0001 per share. |
An unlimited number of common shares, par value of $0.0001 per share. See “Description of PubCo Securities” for a description of the rights and restrictions attached to the securities of PubCo. |
62
|
Plum Articles |
PubCo Closing Articles |
|||
|
Directors; Classes |
The directors are divided into three classes: Class I; Class II; and Class III. The Class I directors stand appointed for a term expiring at Plum’s first annual general meeting, the Class II directors stand appointed for a term expiring at Plum’s second annual general meeting and the Class III directors shall stand appointed for a term expiring at Plum’s third annual general meeting. Directors appointed to succeed those directors who terms expire shall be appointed for a term of office to expire at the third succeeding annual general meeting after their appointment. |
The directors are divided into three classes: Class I; Class II; and Class III. The Class I directors stand appointed for a term expiring at the first annual general meeting following the effectiveness of the PubCo Closing Articles, the Class II directors stand appointed for a term expiring at the second annual general meeting following the effectiveness of the PubCo Closing Articles, and Class III directors stand appointed for a term expiring at the third annual general meeting following the effectiveness of the PubCo Closing Articles. |
||
|
Notice of Shareholder Meeting |
At least five clear days’ notice is given of any general meeting. |
The board of directors of PubCo will have the power to call a meeting of shareholders. Under the BCBCA and in certain circumstances, shareholders can also requisition meetings. The time period to provide notice of the time and place of a meeting of shareholders is not less than 21 days and not more than two months before the meeting. |
||
|
Shareholder Written Consent in Lieu of a Meeting |
No special business shall be transacted at any general meeting unless notice of such special business has been given in the notice convening that meeting. A resolution signed by all shareholders shall be as valid and effective as if the resolution had been passed at a general meeting of the company. |
The shareholders may consent to all of the business that is required to be transacted at an annual general meeting of shareholders by unanimous written resolution, as provided for under the BCBCA. |
||
|
Quorum |
The holders of a majority of the shares being individuals present in person or by proxy or if a corporation or other non-natural person by its duly authorized representative or proxy shall be a quorum. |
Subject to the special rights and restrictions attached to the shares of any class or series of shares of the company, a quorum is present at a meeting of shareholders if at least one shareholder, representing not less than five percent (5%) of the shares entitled to vote at such meeting, are present in person or represented by proxy. |
||
|
Shareholder Vote; Casting Vote |
In the case of an equality of votes, at either a general meeting or a meeting of directors, the chairman shall be entitled to a second or casting vote. Provisions of the memorandum and articles of association may be amended with the approval of a special resolution of the shareholders. |
In the case of an equality of votes, at a meeting of shareholders, the chair of the meeting is not entitled to a second or casting vote. Provisions of the PubCo Closing Articles may be amended with a shareholder vote. In the case of an equality of votes at a meeting of directors, the chair of the meeting is entitled to a second or casting vote. |
63
|
Plum Articles |
PubCo Closing Articles |
|||
|
Advance Notice; Director Nominations; Shareholder Proposals; |
Members seeking to bring business before the annual general meeting or to nominate candidates for appointment as directors at the annual general meeting must deliver notice to the principal executive offices of Plum not less than 120 calendar days before the date of Plum’s proxy statement released to members in connection with the previous year’s annual general meeting or, if the company did not hold an annual general meeting the previous year, or if the date of the current year’s annual general meeting |
Nominations of persons for election to the board may be made for any annual meeting of shareholders, or for any special meeting of shareholders if one of the purposes for which the special meeting was called was the election of directors by a nominating shareholder provided that the nomination is made, in the case of an annual meeting of shareholders, not less than 30 days nor more than 65 days prior to the date of the annual meeting of shareholders; provided, however, that in the event that the annual meeting |
||
|
has been changed by more than 30 days from the date of the previous year’s annual general meeting, then the deadline shall be set by the board of Directors with such deadline being a reasonable time before the company begins to print and send its related proxy materials. |
of shareholders is to be held on a date that is less than 40 days after the date (the “Notice Date”) on which the first public announcement of the date of the annual meeting was made, notice by the nominating shareholder may be made not later than the close of business on the tenth (10th) day following the Notice Date; and in the case of a special meeting (which is not also an annual meeting) of shareholders called for the purpose of electing directors of the Corporation, not later than the close of business on the fifteenth (15th) day following the Notice Date. To be in proper form, the notice of nomination must include certain prescribed information about the nominating shareholder and the proposed nominee. Shareholder proposals are otherwise governed by the provisions of the BCBCA. |
|||
|
Forum Selection |
None. |
None. |
||
|
Takeovers by Interested Shareholders |
None. |
The PubCo Closing Articles will not include provisions with respect to takeovers of the company. |
Appraisal or Dissent Rights
There is no mandatory statutory right of dissent and appraisal in respect of plans of arrangement under the BCBCA unless the terms of the arrangement permits dissent. The Business Combination Agreement does not contemplate any dissent rights or appraisal rights to be available to holders of Plum Class A Shares and Plum Class B Shares in connection with the Business Combination. However, Plum Shareholders are still entitled to exercise the rights of redemption as set out in the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” and the Plum Board has determined that the redemption proceeds payable to Plum Shareholders who exercise such redemption rights represents the fair value of those Plum Common Shares. Please see the subsection entitled “The Business Combination — Appraisal or Dissent Rights” for more information.
64
Material Tax Considerations with Respect to the Business Combination and Ownership of PubCo Securities
Please see the sections entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders” and “Material Canadian Tax Considerations” elsewhere in this proxy statement/prospectus.
Anticipated Accounting Treatment
The Business Combination will be accounted for as a “reverse recapitalization” in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). Under this method of accounting, PubCo will be treated as the “acquired” company for financial reporting purposes. This determination is primarily based on TRC expecting to have a majority of the voting power of the combined company, TRC conducting the ongoing operations of the combined entity, TRC comprising a majority of the governing body of the combined company, and TRC’s senior management comprising the senior management of the combined company. Accordingly, for accounting purposes, the Business Combination will be treated as the equivalent of TRC issuing stock for the net assets of Plum, accompanied by a recapitalization. The net assets of Plum will be stated at historical cost, with no goodwill or other intangible assets will be recorded. Operations prior to the Business Combination will be those of TRC. As it is expected the fair value of Plum Public Warrants and Plum Private Placement Warrants will have similar fair value as those of PubCo Public Warrants as of the Closing, no material impact into profit or loss is expected.
Risk Factor Summary
In evaluating the proposals set forth in this proxy statement/prospectus, you should carefully read this proxy statement/prospectus, including the annexes, and especially consider the factors discussed in the section entitled “Risk Factors.” Some of the risks related to PubCo and TRC’s business and industry and the Business Combination are summarized below.
• TRC’s financial statements have been prepared assuming that TRC will continue as a going concern.
• We have a history of losses in every year since inception and will require additional financing to fund operations.
• We will need to raise additional capital or financing to continue to execute and expand our business.
• Our future performance is difficult to evaluate because we have had a limited operating history on which to base an evaluation of our business and properties.
• The Peak REE Project is in the exploration stage.
• There is no history of producing metals from the Peak REE Project and determining if mineral reserves in commercially exploitable quantities exist and any future development of such resources will be capital intensive.
• Our exploration activities may not be commercially successful.
• The Sierra Blanca Quarry has been leased pursuant to the Project Lease which expires by its terms in February 2028.
• Mining and mineral exploration is inherently dangerous and subject to conditions or events beyond our control, which could have a material adverse effect on our business and plans.
• Mineral operations are subject to market forces outside of our control which could negatively impact us.
• We may be adversely affected by fluctuations in demand for, and prices of, rare earth minerals and products.
• TRC competes with larger, better capitalized competitors in the mining industry.
• Our business and our continued growth depends on our ability to complete the Phase 1 Technical Work Program at the Peak REE Project, which is our only rare earth mining project.
65
• An increase in the global supply of REE products, dumping, predatory pricing and other tactics designed to inhibit our further expansion by our competitors could have a material adverse effect on our prospective profitability.
• Increasing costs or limited access to raw materials, including chemical reagents, may adversely affect our profitability.
• Fluctuations in transportation costs or disruptions in transportation services or damage or loss during transport could
• Permitting, licensing and approval processes are required for the operations at the Peak REE Project and obtaining and maintaining required permits and licenses is subject to conditions which may be unable to be achieved.
• We are subject to significant governmental regulations, which affect operations and costs of conducting business.
• Regulations and pending legislation governing issues involving climate change could result in increased operating costs, which could have a material adverse effect on TRC as well as any other business in which we engage.
• Our exploration and development activities are subject to environmental risks, which could expose us to significant liability and result in the delay, suspension or termination of our operations.
• Plum has not obtained an opinion from an independent investment banking firm, and consequently, there is no assurance from an independent source that the Business Combination consideration is fair to Plum Shareholders from a financial point of view.
• Plum Shareholders may be held liable for claims by third parties against Plum to the extent of distributions received by them upon redemption of their shares.
• Plum Shareholders will experience immediate dilution as a consequence of the issuance of the PubCo Common Shares as consideration in the Business Combination and the PIPE Investment.
• Plum Warrants and TRC Warrants will become exercisable for PubCo Common Shares, which, if exercised, would increase the number of shares eligible for future resale in the public market and result in dilution to Plum Shareholders.
• The Nasdaq may not approve the listing of PubCo’s securities on its exchange, which could limit investors’ ability to make transactions in PubCo’s securities and subject PubCo to additional trading restrictions.
• If Plum is unable to complete the Business Combination or an alternative business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, Plum will cease all operations except for the purpose of winding up, redeem 100% of the outstanding Plum Class A Shares. In such event, holders of Plum Class A Shares may only receive $10.00 per share (or less than such amount in certain circumstances) and Plum Warrants will expire worthless.
• In the event of liquidation by Plum, third parties may bring claims against Plum and, as a result, the proceeds held in the Trust Account could be reduced and the per-share liquidation price received by Plum Shareholders could be less than $10.00 per share.
• Plum’s securities have been delisted from Nasdaq which could make it more difficult to consummate the Business Combination.
• Plum shareholders may be held liable for claims by third parties against Plum to the extent of distributions received by them.
66
• TRC and Plum have no history operating as a combined company. The unaudited pro forma condensed combined financial information may not be an indication of PubCo’s financial condition or results of operations following the Business Combination, and accordingly, you have limited financial information on which to evaluate TRC and your investment decision.
• The exercise of Plum’s directors’ and officers’ discretion in agreeing to changes or waivers in the terms of the Business Combination may result in a conflict of interest when determining whether such changes to the terms of the Business Combination or waivers of conditions are appropriate and in Plum Shareholders’ best interest.
• Citigroup Global Markets, Inc., Morgan Stanley & Co. LLC and William Blair & Company, L.L.C., the underwriters for Plum’s IPO, have waived their deferred underwriting fees.
• Plum and TRC have incurred, and expect to continue to incur, significant transaction costs in connection with the Business Combination.
• Plum’s board of directors has potential conflicts of interest in recommending that Plum Shareholders vote in favor of approval of the Business Combination Agreement and the transactions contemplated thereby, including the Business Combination, and approval of the other proposals described in this proxy statement/prospectus.
• The Business Combination may be completed even though material adverse effects may result from the announcement of the Business Combination, industry-wide changes and other causes.
• Delays in completing the Business Combination may substantially reduce the expected benefits of the Business Combination.
• The Sponsor, as well as Plum’s current and former officers and directors, have agreed to vote in favor of the Business Combination, regardless of how the holders of Plum Class A Shares vote.
• PubCo will have broad discretion in the use of the net proceeds post-Closing and may not use them effectively.
• PubCo’s management has limited experience in operating a public company.
• PubCo’s disclosure controls and procedures may not prevent or detect all errors or acts of fraud.
• Following the consummation of the Business Combination, PubCo may incur significant increased expenses and administrative burdens as a listed public company, which could have an adverse effect on its business, financial condition and results of operations.
• TRC’s internal controls over financial reporting currently do not meet all of the standards contemplated by Section 404 of the Sarbanes-Oxley Act, and the failure of PubCo to achieve and maintain effective internal controls over financial reporting in accordance with Section 404 of the Sarbanes-Oxley Act of 2002 could have a material adverse effect on its business and the market price of PubCo Common Shares.
• PubCo may amend the terms of the warrants in a manner that may be adverse to holders of Plum Warrants with the approval by the holders of at least 50% of the then outstanding Plum Warrants.
• PubCo may redeem your unexpired warrants prior to their exercise at a time that is disadvantageous to you, thereby making your warrants worthless.
• There has been no prior market for PubCo’s Common Shares and an active trading market for such securities may never develop or be sustained, which may cause its shares to trade at a discount and make it difficult to sell the shares.
• The ability of holders of Plum Class A Shares to exercise redemption rights with respect to a large number of Plum Class A Shares could increase the probability that the Business Combination would be unsuccessful and that you would have to wait for liquidation in order to redeem Plum Class A Shares.
67
• We cannot be certain as to the number of Plum Class A Shares that will be redeemed and as to the potential impact to holders of Plum Class A Shares who do elect to redeem their Plum Class A Shares. There is no guarantee that the decision of a holder of Plum Class A Shares to redeem its Plum Class A Shares for a pro rata portion of the funds held in the Trust Account will put the shareholder in a better future economic position.
Market Prices and Dividends
PubCo
Historical market price information regarding PubCo is not provided because there is no public market for its securities.
PubCo has not paid any cash dividends on the PubCo Common Shares to date.
Plum
The Plum Units, Plum Class A Shares and Plum Public Warrants are currently qualified on the OTC Pink under the symbols “PLMUF”,” “PLMJF” and “PLMWF,” respectively. Each Plum Unit consists of one Plum Class A Share and one-third of one Plum Public Warrant. The Plum Units commenced trading on August 11, 2021. Commencing October 1, 2021, holders of Plum Units were permitted to elect to separately trade Plum Class A Shares and Plum Public Warrants included in the Plum Units.
The following table sets forth, for the period indicated, the high and low sales prices per Plum Unit, Plum Class A Share and Plum Public Warrant as reported on the NASDAQ or OTC Pink, as applicable, for the periods presented:
|
Plum Units |
Plum Class A |
Plum Public |
||||||||||||||||
|
High |
Low |
High |
Low |
High |
Low |
|||||||||||||
|
2024 |
|
|
|
|
|
|
||||||||||||
|
Quarter ending December 31, |
$ |
11.63 |
$ |
10.58 |
$ |
11.18 |
$ |
10.88 |
$ |
0.21 |
$ |
0.04 |
||||||
|
Quarter ending September 30 |
$ |
13.63 |
$ |
10.71 |
$ |
10.96 |
$ |
10.77 |
$ |
0.14 |
$ |
0.03 |
||||||
|
Quarter ended June 30, |
$ |
11.00 |
$ |
10.56 |
$ |
10.89 |
$ |
10.63 |
$ |
0.23 |
$ |
0.05 |
||||||
|
Quarter ended March 31, |
$ |
11.08 |
$ |
10.56 |
$ |
11.29 |
$ |
10.50 |
$ |
0.37 |
$ |
0.07 |
||||||
|
|
|
|
|
|
|
|||||||||||||
|
2023 |
|
|
|
|
|
|
||||||||||||
|
Quarter ended December 31, 2023 |
$ |
10.73 |
$ |
10.61 |
$ |
10.83 |
$ |
10.56 |
$ |
0.10 |
$ |
0.00 |
||||||
|
Quarter ended September 30, 2023 |
$ |
10.64 |
$ |
9.71 |
$ |
11.05 |
$ |
10.38 |
$ |
0.36 |
$ |
0.01 |
||||||
|
Quarter ended June 30, |
$ |
10.65 |
$ |
10.21 |
$ |
11.35 |
$ |
10.21 |
$ |
0.12 |
$ |
0.01 |
||||||
|
Quarter ended March 31, 2023 |
$ |
12.27 |
$ |
9.55 |
$ |
10.80 |
$ |
10.02 |
$ |
0.16 |
$ |
0.05 |
||||||
On August 22, 2024, the last trading date before the public announcement of the Business Combination, Plum Units, Plum Class A Shares and Plum Public Warrants closed at $11.40, $10.84 and $0.077, respectively.
Plum has not paid any cash dividends on the Plum Common Shares to date and does not intend to pay cash dividends prior to the completion of the Business Combination.
68
TRC
The TRC Common Shares are currently listed on the TSXV under the symbol “RARE”. The TRC Common Shares began trading on the TSXV on August 31, 2023. The TRC Common Shares are also quoted on the OTC Markets under the symbol “USREF.”
The following table sets forth, for the period indicated, the high and low sales prices per TRC Common Share as reported on the TSXV for the periods presented:
|
High |
Low |
|||
|
2024 |
||||
|
Quarter ended December 31, 2024 |
C$0.560 |
C$0.245 |
||
|
Quarter ending September 30, 2024 |
C$0.670 |
C$0.250 |
||
|
Quarter ended June 30, 2024 |
C$0.400 |
C$0.085 |
||
|
Quarter ended March 31, 2024 |
C$0.150 |
C$0.040 |
||
|
2023 |
||||
|
Quarter ended December 31, 2023 |
C$0.100 |
C$0.025 |
||
|
Quarter ended September 30, 2023 |
C$0.200 |
C$0.100 |
||
|
Quarter ended June 30, 2023 |
C$0.300 |
C$0.160 |
||
|
Quarter ended March 31, 2023 |
C$0.500 |
C$0.250 |
On August 22, 2024, the last trading date before the public announcement of the Business Combination, TRC Common Shares closed at $0.25.
TRC has also not paid any dividends since incorporation. The amount of future cash dividends, if any, is not assured and will be subject to the discretion of the TRC Board. See “Risk Factors.”
69
You should carefully review and consider the following risk factors and the other information contained in this proxy statement/prospectus, including the financial statements and notes to the financial statements included herein, in evaluating the Business Combination and the proposals to be voted on at the Plum Shareholders’ Meeting. The following risk factors apply to the business of TRC, the operation of the business by TRC and will also apply to the business and operations of PubCo following the completion of the Business Combination. The occurrence of one or more of the events or circumstances described in these risk factors, alone or in combination with other events or circumstances, may adversely affect the ability to complete or realize the anticipated benefits of the Business Combination, and may have a material adverse effect on the business, cash flows, financial condition and results of operations of PubCo. You should carefully consider the following risk factors in addition to the other information included in this proxy statement/prospectus, including matters addressed in the section entitled “Cautionary Note Regarding Forward-Looking Statements.” PubCo may face additional risks and uncertainties that are not presently known to us, or that we currently deem immaterial, which may also impair PubCo’s business or financial condition. The following discussion should be read in conjunction with the financial statements and notes to the financial statements included herein. Unless the context requires otherwise, as used herein, references to “we,” “us,” “our,” and “ours” refer both to the business of TRC and its subsidiaries as presently conducted, as well as the business of PubCo and its subsidiaries following the Business Combination.
Risks Relating to TRC’s Business and Industry
TRC’s financial statements have been prepared assuming that TRC will continue as a going concern.
Our financial statements have been prepared assuming that TRC will continue as a going concern. TRC has an accumulated deficit from inception through July 31, 2024, of approximately $8,615,197, has yet to achieve profitable operations, and projects further losses in the development of its business. TRC’s ability to continue as a going concern is dependent upon its ability to obtain the necessary financing to meet its obligations and pay its liabilities arising from normal business operations when they come due.
There can be no assurance that TRC will be able to raise the necessary capital to fund its expected operating expenses. We have no firm commitments for equity or debt financing and any financing that may be obtained will be on a best efforts basis. Based on these factors, there is substantial doubt as to TRC’s ability to continue as a going concern for a period of twelve months from the issuance date of its most recent audited financial statements. The failure to obtain sufficient financing may cause us to curtail or discontinue operations.
We have a history of losses in every year since inception and will require additional financing to fund operations. Failure to obtain additional financing could have a material adverse effect on our financial condition and results of operation and could cast uncertainty on our ability to continue as a going concern in future periods.
During the fiscal year ended July 31, 2024, we had no revenues. For the fiscal year ended July 31, 2024, our net loss was approximately $2.6 million and our accumulated deficit at July 31, 2024 was approximately $8.6 million. At July 31, 2024, our cash position was approximately $0.03 million and our working capital deficit was approximately $1.4 million. There can be no assurance that the Peak REE Project will ever commence commercial production.
We will need to raise additional capital or financing to continue to execute and expand our business.
We will need to raise additional capital to support operations and execute on our business plan, which may include the issuance of equity or convertible debt securities. There is no guarantee that we will be able to raise additional capital on a timely basis or on acceptable terms. To the extent that we raise additional funds by issuing equity or convertible debt securities, TRC shareholders, PubCo Shareholders and Plum Shareholders may experience additional dilution. Newly issued securities may include preferences, superior voting rights, and the issuance of warrants or other convertible securities that will have additional dilutive effects. Further, we may incur substantial costs in pursuing such capital and/or financing. We may also be required to recognize non-cash expenses in connection with certain securities we may issue, such as convertible notes and warrants, which will adversely impact our financial condition and results of operations. Our ability to obtain needed financing may be impaired by such factors as the weakness of capital markets, and the fact that we have not been profitable, which could impact the availability and cost of future financings.
70
Our future performance is difficult to evaluate because we have had a limited operating history on which to base an evaluation of our business and properties.
We have not realized any revenues to date from the sale of rare earth minerals and our operating cash flow needs have been financed through the issuances of debt and equity raises and not through cash flows derived from our operations. As a result, we have little historical financial and operating information available to help you evaluate our performance. Any investment in TRC should be considered a high-risk investment because investors will be placing funds at risk in an early stage, under-capitalized business with unforeseen costs, expenses, competition, a history of operating losses and other problems to which start-up ventures are often subject. Investors should not invest in TRC unless they can afford to lose their entire investment. Your investment must be considered in light of the risks, expenses, and difficulties encountered in establishing a new business in a highly competitive industry. Our operating history has been limited to the acquisition and sampling of the tailings from the Peak REE Project which does not yet provide a meaningful basis for an evaluation of the Peak REE Project. Other than through conventional and typical exploration methods and procedures, we have no additional way to evaluate the likelihood of whether the Peak REE Project contains commercial quantities of mineral reserves or, if it does, that it will be operated successfully. We anticipate that we will continue to incur significant operating costs without realizing any revenues for the foreseeable future.
The Peak REE Project is in the exploration stage. There is no assurance that TRC can establish the existence of any mineral reserve from the Peak REE Project in commercially exploitable quantities. Until then, we cannot earn any revenues from the Peak REE Project, and our business could fail.
We have not established that the Peak REE Project contains any commercially exploitable quantities of mineral reserve, nor can there be any assurance that we will be able to do so. The probability of the Peak REE Project ever having a commercially exploitable mineral reserve that meets the requirements of the SEC may be remote. Even if we do eventually discover commercially exploitable quantities of mineral reserve on the Peak REE Project, there can be no assurance that it can be developed into a producing mine and extract those minerals. Both mineral exploration and development involve a high degree of risk and few properties, which are explored, are ultimately developed into producing mines.
The commercial viability of an established mineral deposit will depend on a number of factors including, by way of example, the size, grade and other attributes of the mineral deposit, the proximity of the deposit to infrastructure such as a smelter, roads and a point for shipping, government regulation and market prices. Most of these factors will be beyond our control, and any of them could increase costs and make extraction of any identified mineral deposit unprofitable.
Even if commercial viability of a mineral deposit is established, it may take several years until production is possible, during which time the economic feasibility of production may change. Substantial expenditures are required to establish proven and probable reserves through sampling, to determine the optimal metallurgical process to extract the metals from the tailings and, in the case of new properties, to construct processing facilities. Because of these uncertainties, no assurance can be given that our exploration programs will result in the establishment or expansion of a mineral deposit or reserves.
The Peak REE Project is a high-risk project and investors should not make an investment in TRC unless you have the ability to lose your entire investment.
There is no history of producing metals from the Peak REE Project and determining if mineral reserves in commercially exploitable quantities exist and any future development of such resources will be capital intensive.
There is no history of producing metals from the Peak REE Project. The Peak REE Project is an exploration stage property in the early stage of exploration and evaluation. Advancing properties from exploration into the development stage requires significant capital and time, and successful commercial production from the Peak REE Project will be subject to permitting and construction of processing plants, roads, and other related works and infrastructure. As a result, we are subject to all of the risks associated with developing and establishing new mining operations and business enterprises including:
• verifying reserves and commercial viability, including the ability to find sufficient REE reserves to support a commercial mining operation;
• the timing and cost, which can be considerable, of further exploration, permitting and construction of infrastructure and processing facilities;
71
• the availability and costs of exploration personnel, skilled labor and processing equipment, if required;
• the availability and cost of appropriate smelting and/or refining arrangements, if required, and securing a commercially viable sales outlet for our products;
• compliance with environmental and other governmental approval and permit requirements;
• the availability of funds to finance exploration, development and construction activities, as warranted;
• potential opposition from non-governmental organizations, environmental groups, local groups or local inhabitants which may delay or prevent development activities;
• potential increases in exploration, construction and operating costs due to changes in the cost of fuel, power, materials and supplies; and
• potential shortages of mineral processing, construction and other facilities related supplies.
The costs, timing and complexities of exploration, development and construction activities may be increased by the location of the Peak REE Project and demand by other mineral exploration and mining companies. It is common in exploration programs to experience unexpected problems and delays during development, construction and mine start-up activities. Accordingly, TRC’s activities may not result in profitable processing operations and TRC may not succeed in establishing processing operations or profitably producing metals with respect to the Peak REE Project.
If we establish the existence of a mineral reserve in the Peak REE Project in a commercially exploitable quantity, we will require additional capital in order to fund our costs to develop the property into a producing mine.
TRC will be required to expend significant funds to determine if mineral reserves in commercially exploitable quantities exist in the Peak REE Project, and then TRC will be required to expend substantial additional sums of money to establish the extent of the reserve, develop processes to extract it and develop extraction and processing facilities and infrastructure. There is no assurance that any project level financing can ever be obtained. As such, there is no assurance that the necessary financing can be obtained to develop necessary facilities and infrastructure to accomplish our goals. Although TRC may derive substantial benefits from the discovery of a major mineral deposit, there can be no assurance that such a deposit will be large enough to justify commercial operations, nor can there be any assurance that TRC will be able to raise the funds at the level required for development on a timely basis.
Our exploration activities may not be commercially successful.
Our long-term success depends on our ability to identify mineral deposits in the Peak REE Project or other properties we may acquire that we can then develop into commercially viable processing operations. Our belief that the Peak REE Project contains commercially exploitable minerals has been based solely on preliminary tests that TRC has conducted and data provided by our third-party expert. There can be no assurance that the tests and data upon which we have relied is correct or accurate and, accordingly, there is no assurance that the Peak REE Project contains commercially exploitable minerals. Moreover, mineral exploration is highly speculative in nature, involves many risks and is frequently non-productive. The inability to obtain suitable or adequate machinery, equipment or labor are risks involved in the conduct of exploration programs. The success of mineral exploration and development is determined in part by the following factors:
• the identification of potential mineralization based on analysis;
• the availability of exploration permits;
• the quality of our management and our geological and technical expertise; and
• the capital available for exploration.
Substantial expenditures and time are required to establish existing proven and probable reserves through analysis, to develop metallurgical processes to extract metal, and to develop the processing facilities and infrastructure at any site chosen for processing. Whether a mineral deposit will be commercially viable depends on a number of factors, which include, without limitation, the particular attributes of the deposit, such as size, grade and
72
proximity to infrastructure; metal prices, which fluctuate widely; and government regulations, including, without limitation, regulations relating to prices, taxes, royalties, land tenure, land use, allowable production, importing and exporting of minerals and environmental protection. Any one or a combination of these factors may result in us not receiving an adequate return on our investment in TRC or any other mineral project we may pursue. The decision to abandon a project will have an adverse effect on the market value of our securities and our ability to raise future financing.
The Sierra Blanca Quarry has been leased to Sierra Blanca Quarry, LLC (“SBQ”) pursuant to Mining Lease M-11469 (the “Project Lease”), which expires by its terms in February 2028.
The Project Lease is between SBQ and the State of Texas. All of TRC’s rights under the SBQ Offtake Agreement are subject to the continued existence of the Project Lease. TRC has no right to cause SBQ to extend the Project Lease after the expiration of its term. TRC also has no right to cause SBQ to continue to mine the Project Lease and provide TRC with a continuous stream of tailings. If SBQ decides to let the Project Lease expire, TRC would lose all access to the Project Lease and the tailings located thereon. This would effectively prevent TRC from conducting any extraction of REEs from the mine tailings. TRC does have an option to acquire all of the membership interests in TRC. However, if TRC were to acquire SBQ, TRC would then be in the business of running SBQ’s mining operations. TRC’s management has no history of operating such a mining operation.
Mining and mineral exploration is inherently dangerous and subject to conditions or events beyond our control, which could have a material adverse effect on our business and plans.
Mining and mineral exploration involves various types of risks and hazards, including:
• environmental hazards;
• power outages;
• metallurgical and other processing problems;
• personal injury, flooding, fire, explosions, cave-ins, landslides and rock-bursts;
• inability to obtain suitable or adequate machinery, equipment, or labor;
• metals losses;
• fluctuations in exploration, development and production costs;
• labor disputes;
• unanticipated variations in grade;
• mechanical equipment failure; and
• periodic interruptions due to inclement or hazardous weather conditions.
These risks could result in damage to, or destruction of, the Peak REE Project, production facilities or other properties, personal injury, environmental damage, delays in mining, increased production costs, monetary losses and possible legal liability. TRC may not be able to obtain insurance to cover these risks at economically feasible premiums. Insurance against certain environmental risks, including potential liability for pollution or other hazards as a result of the disposal of waste products occurring from production, may be prohibitively expensive. TRC may suffer a material adverse effect on its business if not covered by insurance policies. TRC operations may contain significant uninsured risks which could negatively impact future profitability.
Any exploration of the Peak REE Project contains and will contain certain risks, including unexpected or unusual operating conditions. It is not always possible to insure against these risks. Should events such as these arise, they could reduce or eliminate our investment in TRC as well as result in increased costs and a decline in the value of our investment.
73
Mineral operations are subject to market forces outside of our control which could negatively impact us.
The marketability of minerals is affected by numerous factors beyond our control including market fluctuations, government regulations relating to prices, taxes, royalties, allowable production, imports, exports and supply and demand. One or more of these risk elements could have an impact on the costs of TRC’s operations and, if significant enough, could impact our investment.
We may be adversely affected by fluctuations in demand for, and prices of, rare earth minerals and products.
Our goal is for TRC to derive revenues from the sale of rare earth and related minerals. Changes in demand for, and the market price of, these minerals could significantly affect us. The value and price of our securities and our financial results may be significantly adversely affected by declines in the prices of rare earth minerals and products. Rare earth minerals and product prices may fluctuate and are affected by numerous factors beyond our control such as interest rates, exchange rates, inflation or deflation, fluctuation in the relative value of the U.S. dollar against foreign currencies on the world market, global and regional supply and demand for rare earth minerals and products, and the political and economic conditions of countries (including specifically China and the U.S.’s relationship with China at any given time) that produce rare earth minerals and products.
A prolonged or significant economic contraction in the United States or worldwide could put further downward pressure on market prices of rare earth minerals and products. Protracted periods of low prices for rare earth minerals and products could significantly reduce revenues and the availability of required development funds in the future. This could cause substantial reductions to, or a suspension of, REE production operations, impair asset values and if reserves are established on our prospects, reduce our proven and probable rare earth reserves.
In contrast, extended periods of high commodity prices may create economic dislocations that may be destabilizing to rare earth minerals supply and demand and ultimately to the broader markets. Periods of high rare earth mineral market prices generally would be beneficial to us. However, strong rare earth mineral prices also create economic pressure to identify or create alternate technologies that ultimately could depress future long-term demand for rare earth minerals and products, and at the same time may incentivize development of otherwise marginal mining properties.
Increased competition could adversely affect our ability to attract necessary capital funding or acquire suitable producing properties or prospects for mineral exploration in the future.
The mining industry is intensely competitive. Significant competition exists for the acquisition of properties producing or capable of producing REE or other metals. We likely are at a competitive disadvantage in acquiring additional mining properties because we must compete with other individuals and companies, most of which have greater financial resources, operational experience and technical capabilities than us. We may also encounter increasing competition from other mining companies in our efforts to hire experienced mining professionals. Competition for exploration resources at all levels is currently very intense, particularly affecting the availability of manpower, mining equipment and production equipment. Increased competition could adversely affect our ability to attract necessary capital funding or acquire suitable producing properties or prospects for mineral exploration in the future.
TRC competes with larger, better capitalized competitors in the mining industry.
The mining industry is competitive in all of its phases, including financing, technical resources, personnel and property acquisition. TRC will require significant capital, technical resources, personnel and operational experience to effectively compete in the mining industry. Because of the high costs associated with exploration, the expertise required to analyze a project’s potential and the capital required to develop a mine, larger companies with significant resources may have a competitive advantage over TRC. TRC faces strong competition from other mining companies, some with greater financial resources, operational experience and technical capabilities than us. As a result of this competition, TRC may not be able to acquire financing, personnel, technical resources or attractive mining properties on acceptable terms, if at all.
74
The actual amount of capital required for the Phase 1 Technical Work Program at the Peak REE Project may vary materially from our current estimates, in which case we may need to raise additional funds, which could delay completion and have a material adverse effect on our business, financial condition and results of operations.
The anticipated funding required to complete the Phase 1 Technical Work Program at the Peak REE Project is based on certain estimates and assumptions we have made about the additional equipment, labor, permits and other factors required to complete the project. If any of these estimates or assumptions change, the actual timing and amount of capital required to complete the Phase 1 Technical Work Program may vary materially from what we anticipate. Additional funds may be required in the event of significant departures from our current plans, unforeseen delays, cost overruns, engineering design changes or other unanticipated events or expenses. There can be no assurance that additional financing will be available to us, or, if available, that it can be obtained on a timely basis and on commercially acceptable terms.
Our business and our continued growth depends on our ability to complete the Phase 1 Technical Work Program at the Peak REE Project, which is our only rare earth mining project.
Our only rare earth mining project at this time is at the Peak REE Project. Our business and our continued growth will be based on successfully completing the Phase 1 Technical Work Program and reaching anticipated production rates for the production of REEs in accordance with our expected timeframe. The deterioration or destruction of any part of the Peak REE Project, or a delay in the procurement of any necessary equipment, may significantly hinder our ability to reach or maintain anticipated production rates within the expected time frame or at all. If we are unsuccessful in reaching and maintaining expected production rates for REEs at the Peak REE Project, within expected time frames or at all, we may not be able to build a sustainable or profitable business as currently expected or at all.
The success of our business will depend, in part, on the growth of existing and emerging uses for REE products.
The success of our business will depend, in part, on the growth of existing and emerging uses for rare earth products. Our strategy is to develop rare earth products which are used in critical existing and emerging technologies, such as hybrid and electric vehicles, wind turbines, robotics, medical equipment, military equipment and other high-growth, advanced motion technologies. The success of our business depends on the continued growth of these end markets and successfully commercializing rare earth products in such markets. If the market for these critical existing and emerging technologies does not grow as we expect, grows more slowly than we expect, or if the demand for our products in these markets decreases, then our business, prospects, financial condition and operating results could be harmed. In addition, the market for these technologies, particularly in the automotive industry, tends to be cyclical, which exposes us to increased volatility, and it is uncertain as to how such macroeconomic factors will impact our business. Any unexpected costs or delays in the commercialization of our expected products, or less than expected demand for the critical existing and emerging technologies that use rare earth products, could have a material adverse effect on our financial condition or results of operations.
Our ability to generate revenue will be diminished if we are unable to compete with substitutions for the rare earth minerals that we intend to mine.
Technology changes rapidly in the industries and end markets that we expect to utilize our materials. If these industries introduce new technologies or products that no longer require the rare earth materials we intend to mine to function or suitable substitutes become available, it could result in a decline in demand for our rare earth minerals. If the demand for our rare earth minerals decreases, it will have a material adverse effect on our business and the results of our operations and financial condition.
An increase in the global supply of REE products, dumping, predatory pricing and other tactics designed to inhibit our further expansion by our competitors could have a material adverse effect on our prospective profitability.
The pricing and demand for REEs is affected by a number of factors beyond our control, including growth of economic development and the global supply and demand for REE products. According to a study from the Brooking’s Institution, China presently produces some 60% of the world’s rare earth elements and processes 85% of them China also dominates the manufacture of metals and NdFeB magnets from rare earths, capabilities that are
75
not currently present in the United States, and the Chinese Central Government regulates production via quotas and environmental standards. Over the past few years, there has been significant restructuring of the Chinese markets in line with China Central Government policy. Assuming that we reach anticipated production rates for REEs, the increased competition may lead our competitors to engage in predatory pricing or other behaviors designed to inhibit our further expansion. Any increase in the amount of REEs and rare earth products exported from other nations and increased competition may result in price reductions, reduced margins or loss of potential market share, any of which could materially adversely affect our profitability. As a result of these factors, we may not be able to compete effectively against current and future competitors.
A power shortage at the Peak REE Project could temporarily delay processing operations and increase costs, which could have a material adverse effect on our business, financial condition and results of operations.
Operations relating to our Peak REE Project currently rely on electricity provided by a single utility company. Instability in electrical supply could cause sporadic outages and brownouts and result in temporary interruptions of processing operations. If power to the Peak REE Project is disrupted during certain phases of our REE extraction process, we may incur significant delays and expenses that may adversely impact our ability to generate future revenues.
Increasing costs or limited access to raw materials, including chemical reagents, may adversely affect our profitability.
We intend to use significant amounts of chemical reagents to process REEs. On-site production of these reagents could be delayed and any production could be hampered by any disruptions in the process used to produce these chemicals. A significant increase in the price, or decrease in the availability of these chemicals before we restart our ability to produce them on-site, or restrictions imposed by environmental regulations or law on chemical use, could materially increase our operating costs and adversely affect our profit margins and production volumes.
Fluctuations in transportation costs or disruptions in transportation services or damage or loss during transport could decrease our competitiveness or impair our ability to supply REE products to future customers, which could adversely affect our results of operations.
We expect to transport our products to future customers wherever they are located. Finding affordable and dependable transportation will be important because it will allow us to supply customers around the world. Labor disputes, embargos, government restrictions, work stoppages, pandemics, derailments, damage or loss events, adverse weather conditions, other environmental events, changes to rail or ocean freight systems or other events and activities beyond our control could interrupt or limit available transport services, which could result in customer dissatisfaction and loss of sales potential and could materially adversely affect our results of operations.
We will need to process REEs to exacting specifications in order to provide future customers with a consistently high-quality product. An inability to perfect the mineral extraction processes to meet individual customer specifications could have a material adverse effect on our business, financial condition and results of operations.
Upon the completion of our Phase 1 Technical Work Program, we will need to be able to process REEs to meet customer needs and specifications and to provide customers with a consistently high-quality product and to meet ever-stricter purity requirements. An inability to perfect the mineral extraction processes to meet individual customer specifications may have a material adverse effect on our financial condition or results of operations. In addition, customer needs and specifications may change with time. Any delay or failure in developing processes to meet changing customer needs and specifications may have a material adverse effect on our financial condition or results of operations.
A shortage of skilled personnel may further increase operating costs, which could have a material adverse effect on our results of operations.
Efficient production of REEs using modern techniques and equipment will require skilled management, scientific, technical, marketing and support personnel. In addition, optimization and eventual downstream efforts will significantly increase the number of skilled operators, maintenance technicians, engineers and other personnel required to successfully operate our business. In the event that we are unable to hire, train and retain the necessary
76
number of skilled management, scientific, technical, marketing and support personnel, there could be an adverse impact on our labor costs and our ability to reach production in a timely manner, which could have a material adverse effect on our results of operations.
We are dependent upon information technology systems, which are subject to cyber threats, disruption, damage and failure.
We depend upon information technology systems in the conduct of our operations. Our information technology systems are subject to disruption, damage or failure from a variety of sources, including, without limitation, computer viruses, security breaches, cyber-attacks, natural disasters and defects in design. Cybersecurity incidents, in particular, are evolving and include, but are not limited to, malicious software, attempts to gain unauthorized access to data and other electronic security breaches that could lead to disruptions in systems, unauthorized release of confidential or otherwise protected information or the corruption of data. Various measures have been implemented to manage our risks related to information technology systems and network disruptions. However, given the unpredictability of the timing, nature and scope of information technology disruptions, we could potentially be subject to downtimes, operational delays, the compromising of confidential or otherwise protected information, destruction or corruption of data, security breaches, other manipulation or improper use of our systems and networks or financial losses from remedial actions, any of which could have a material adverse effect on our business, operating results and financial condition.
Risks Related to Legal, Compliance and Regulations
Permitting, licensing and approval processes are required for the operations at the Peak REE Project and obtaining and maintaining required permits and licenses is subject to conditions which may be unable to be achieved.
Both mineral exploration and extraction at the Peak REE Project requires permits from various federal, state, provincial and local governmental authorities and are governed by laws and regulations, including those with respect to prospecting, mine development, mineral production, transport, export, taxation, labor standards, occupational health, waste disposal, toxic substances, land use, environmental protection, mine safety and other matters. Permits currently required include (i) an operating plan for the conduct of exploration and development approved by the Texas General Land Office (“GLO”), (ii) an operating plan for production approved by the GLO, and (iii) reporting to and compliance with regulations of the Texas Commission of Environmental Quality. If TRC recovers uranium at the Peak REE Project, it will be required to obtain a source material license from the United States Nuclear Regulatory Commission. TRC may also be subject to the reporting requirements and regulations of the Texas Department of Health. Such licenses and permits are subject to changes in regulations and changes in various operating circumstances. Companies that engage in exploration activities often experience increased costs and delays in production and other schedules as a result of the need to comply with applicable laws, regulations and permits. Issuance of permits for TRC’s activities is subject to the discretion of government authorities, and TRC may be unable to obtain or maintain such permits. Permits required for future exploration or development may not be obtainable on reasonable terms or on a timely basis. There can be no assurance that TRC will be able to obtain or maintain any of the permits required for the continued exploration or development of the Peak REE Project (or any other of our mineral properties that we may subsequently acquire) or for the construction and operation of a mine on our properties that we may subsequently acquire at economically viable costs. If we cannot accomplish these objectives, our business could face difficulty and/or fail.
We are subject to significant governmental regulations, which affect operations and costs of conducting business.
Our current and future operations are and will be governed by laws and regulations, including:
• laws and regulations governing mineral concession acquisition, prospecting, development, mining and production;
• laws and regulations related to exports, taxes and fees;
• labor standards and regulations related to occupational health and mine safety;
77
• environmental standards and regulations related to waste disposal, toxic substances, land use and environmental protection; and
• other matters.
Corporations engaged in exploration activities often experience increased costs and delays in production and other schedules as a result of the need to comply with applicable laws, regulations and permits. Failure to comply with applicable laws, regulations and permits may result in enforcement actions, including the forfeiture of claims, orders issued by regulatory or judicial authorities requiring operations to cease or be curtailed, and may include corrective measures requiring capital expenditures, installation of additional equipment or costly remedial actions. TRC may be required to compensate those suffering loss or damage by reason of its mineral exploration activities and may have civil or criminal fines or penalties imposed for violations of such laws, regulations and permits.
Existing and possible future laws, regulations and permits governing operations and activities of exploration companies, or more stringent implementation, could have a material adverse impact on TRC’s business and cause increases in capital expenditures or require abandonment or delays in exploration.
Regulations and pending legislation governing issues involving climate change could result in increased operating costs, which could have a material adverse effect on TRC as well as any other business in which we engage.
A number of governments or governmental bodies have introduced or are contemplating regulatory changes in response to various climate change interest groups and the potential impact of climate change. Legislation and increased regulation regarding climate change could impose significant costs on TRC and our suppliers, including costs related to increased energy requirements, capital equipment, environmental monitoring and reporting and other costs to comply with such regulations. Any adopted future climate change regulations could also negatively impact the ability to compete with companies situated in areas not subject to such limitations. Given the emotion, political significance and uncertainty around the impact of climate change and how it should be dealt with, we cannot predict how legislation and regulation will affect our financial condition, operating performance and ability to compete. Furthermore, even without such regulation, increased awareness and any adverse publicity in the global marketplace about potential impacts on climate change by us or other companies in our industry could harm our reputation. The potential physical impacts of climate change on our operations are highly uncertain and would be particular to the geographic circumstances in areas in which we operate. These may include changes in rainfall and storm patterns and intensities, water shortages, changing sea levels and changing temperatures. These impacts may adversely impact the cost, production and financial performance of TRC’s operations or any other mineral projects we may pursue.
Our exploration and development activities are subject to environmental risks, which could expose us to significant liability and result in the delay, suspension or termination of our operations.
The exploration, future development and production phases of our business will be subject to federal, state and local environmental regulation. These regulations mandate, among other things, the maintenance of air and water quality standards and land reclamation. They also set out limitations on the generation, transportation, storage and disposal of solid and hazardous waste. Environmental legislation is evolving in a manner which will require stricter standards and enforcement, increased fines and penalties for non-compliance, more stringent environmental assessments, and a heightened degree of responsibility for companies and their officers, directors and employees. Future changes in environmental regulations may adversely affect our operations. If we fail to comply with any of the applicable environmental laws, regulations or permit requirements, we could face regulatory or judicial sanctions. Penalties imposed by either the courts or administrative bodies could delay or stop operations or require a considerable capital expenditure. Although we intend to comply with all environmental laws and permitting obligations in conducting our business, there is a possibility that those opposed to exploration and mining will attempt to interfere with our operations, whether by legal process, regulatory process or otherwise.
Environmental hazards unknown to TRC, which have been caused by previous or existing owners or operators of the properties, may exist on the properties comprising the Peak REE Project. It is possible that these properties could be located on or near the site of a Federal Superfund cleanup project; as such, it is possible that environmental cleanup or other environmental restoration procedures could remain to be completed or mandated by law, causing unpredictable and unexpected liabilities to arise.
78
The Comprehensive Environmental, Response, Compensation, and Liability Act (“CERCLA”), and comparable state statutes, impose strict, joint and several liability on current and former owners and operators of sites and on persons who disposed of or arranged for the disposal of hazardous substances found at such sites. It is not uncommon for the government to file claims requiring cleanup actions, demands for reimbursement for government-incurred cleanup costs, or natural resource damages, or for neighboring landowners and other third parties to file claims for personal injury and property damage allegedly caused by hazardous substances released into the environment. The Federal Resource Conservation and Recovery Act (“RCRA”), and comparable state statutes, govern the disposal of solid waste and hazardous waste and authorize the imposition of substantial fines and penalties for noncompliance, as well as requirements for corrective actions. CERCLA, RCRA and comparable state statutes can impose liability for clean-up of sites and disposal of substances found on exploration, mining and processing sites long after activities on such sites have been completed.
The Clean Air Act restricts the emission of air pollutants from many sources, including mining and processing activities. Our processing operations may produce air emissions, including fugitive dust and other air pollutants from stationary equipment, storage facilities and the use of mobile sources such as trucks and heavy construction equipment, which are subject to review, monitoring and/or control requirements under the Clean Air Act and state air quality laws. New facilities may be required to obtain permits before work can begin, and existing facilities may be required to incur capital costs in order to remain in compliance. In addition, permitting rules may impose limitations on our production levels or result in additional capital expenditures in order to comply with the rules.
The National Environmental Policy Act (“NEPA”) requires federal agencies to integrate environmental considerations into their decision-making processes by evaluating the environmental impacts of their proposed actions, including issuance of permits to mining facilities, and assessing alternatives to those actions. If a proposed action could significantly affect the environment, the agency must prepare a detailed statement known as an Environmental Impact Statement (“EIS”). The U.S. Environmental Protection Agency (“EPA”), other federal agencies, and any interested third parties will review and comment on the scoping of the EIS and the adequacy of and findings set forth in the draft and final EIS. This process can cause delays in issuance of required permits or result in changes to a project to mitigate its potential environmental impacts, which can in turn impact the economic feasibility of a proposed project.
The Clean Water Act (“CWA”), and comparable state statutes, imposes restrictions and controls on the discharge of pollutants into waters of the United States. The discharge of pollutants into regulated waters is prohibited, except in accordance with the terms of a permit issued by the EPA or an analogous state agency. The CWA regulates storm water mining facilities and requires a storm water discharge permit for certain activities. Such a permit requires the regulated facility to monitor and sample storm water run-off from its operations. The CWA and regulations implemented thereunder also prohibit discharges of dredged and fill material in wetlands and other waters of the United States unless authorized by an appropriately issued permit. The CWA and comparable state statutes provide for civil, criminal and administrative penalties for unauthorized discharges of pollutants and impose liability on parties responsible for those discharges for the costs of cleaning up any environmental damage caused by the release and for natural resource damages resulting from the release.
The Safe Drinking Water Act (“SDWA”) and the Underground Injection Control (“UIC”) program promulgated thereunder, regulate the drilling and operation of subsurface injection wells. EPA directly administers the UIC program in some states and in others the responsibility for the program has been delegated to the state. The program requires that a permit be obtained before drilling a disposal or injection well. Violation of these regulations and/or contamination of groundwater by mining related activities may result in fines, penalties, and remediation costs, among other sanctions and liabilities under the SDWA and state laws. In addition, third party claims may be filed by landowners and other parties claiming damages for alternative water supplies, property damages, and bodily injury.
We could be subject to environmental lawsuits.
Neighboring landowners and other third parties could file claims based on environmental statutes and common law for personal injury and property damage allegedly caused by the release of hazardous substances or other waste material into the environment on or around the Peak REE Project. While currently SBQ is the legal and beneficiary holder of the Project Lease and the agreement between SBQ and TRC for the Peak REE Project is solely related to the sale and purchase of tailings such that TRC is not bound by any environmental liabilities related to the Quarry mining activity at this time, TRC’s future operations, including the exercise of its option to acquire SBQ, could
79
expose TRC to potential environmental claims. There can be no assurance that any defense of such claims will be successful. A successful claim against TRC could have an adverse effect on not only TRC, but us and our business prospects, financial condition and results of operation.
Land reclamation requirements for the Peak REE Project may be burdensome and expensive.
Although variability exists by location and the governing authority, land reclamation requirements are generally imposed on mineral exploration companies (as well as companies with mining operations) in order to minimize long term effects of land disturbance.
Reclamation may include requirements to:
• control dispersion of potentially deleterious effluents;
• treat ground and surface water to drinking water standards; and
• reasonably re-establish pre-disturbance land forms and vegetation.
In accordance with GLO lease/prospecting permits, all the areas impacted by the surface operations shall be reclaimed upon completion of the activity, including (a) removal of all trash, debris, plastic and contaminated soil by off-site disposal, and (b) upon completion of surface grading, the soil surface shall be left in a roughened condition to negate wind and enhance water infiltration.
In order to carry out reclamation obligations imposed on TRC in connection with potential development activities, TRC must allocate financial resources that might otherwise be spent on further exploration and development programs. TRC plans to set up a provision for reclamation obligations on its properties, as appropriate, but this provision may not be adequate. If TRC is required to carry out unanticipated reclamation work, its financial position could be adversely affected.
Mining presents potential health risks; payment of any liabilities that arise from these health risks may adversely impact TRC.
Complying with health and safety standards will require additional expenditure on testing and the installation of safety equipment. Moreover, inhalation of certain minerals can result in specific potential health risks. Symptoms of these associated diseases may take years to manifest. Failure to comply with health and safety standards could result in statutory penalties and civil liability. TRC does not currently maintain any insurance coverage against these health risks. The payment of any liabilities that arise from any such occurrences could have a material, adverse impact on TRC.
There may be challenges to the title of the Peak REE Project or any other mineral properties that we may acquire.
We expect that any additional properties to be acquired by TRC (with respect to any other opportunities) will be by unpatented claims or by lease from those owning the property. The lease of the Peak REE Project property was issued by the State of Texas. In addition, we are not parties to the lease and do not have the right to cause its extension. Also, if SBQ’s contract to supply ballast to Union Pacific Railroad were to terminate, SBQ would no longer have any reason to continue mining operations at the quarry. The validity of title to many types of natural resource property depends upon numerous circumstances and factual matters (many of which are not discoverable of record or by other readily available means) and is subject to many uncertainties of existing law and its application. We cannot assure you that the validity of TRC’s titles to its properties or our title to properties we may purchase in the future will be upheld or that third parties will not otherwise invalidate those rights. In the event the validity of TRC’s or our titles with respect to any future properties are not upheld, such an event would have a material adverse effect on TRC.
80
Risks Related to Plum, PubCo and the Business Combination
Plum has not obtained an opinion from an independent investment banking firm, and consequently, there is no assurance from an independent source that the Business Combination consideration is fair to Plum Shareholders from a financial point of view.
Plum is not required to, and has not, obtained an opinion from an independent investment banking firm that the consideration it is paying for TRC in the Business Combination is fair to Plum Shareholders from a financial point of view. Plum is also not required to, and has not, obtained any third party report, opinion or appraisal in establishing a valuation for TRC. The Plum Board relied on the financial skills and background of its officers and directors in determining the value of TRC and in making its assessment of the Business Combination. Plum Shareholders will be relying on the judgment of the Plum Board with respect to such matters and assuming the risk that the Plum Board may not have properly valued such business or may have been incorrect in its assessment of the Business Combination.
Going public through a merger rather than an underwritten offering presents risks to unaffiliated investors. Following the closing of the Business Combination, PubCo may be required to take write-downs or write-offs, restructuring and impairment or other charges that could have a significant negative effect on PubCo’s financial condition, results of operations and share price, which could cause you to lose some or all of your investment.
Plum cannot assure you that the due diligence conducted in relation to TRC has identified all material issues or risks associated with TRC, its business or the industry in which it competes. As a result of these factors, we may incur additional costs and expenses and PubCo may be forced to later write-down or write-off assets, restructure operations, or incur impairment or other charges that could result in reporting losses. Even if due diligence has identified certain risks, unexpected risks may arise and previously known risks may materialize in a manner not consistent with the preliminary risk analysis. If any of these risks materialize, this could have a material adverse effect on PubCo’s financial condition and results of operations and could contribute to negative market perceptions about the securities or PubCo. Accordingly, any shareholders of Plum who choose to remain PubCo shareholders following the Business Combination could suffer a reduction in the value of their shares and warrants. Such shareholders are unlikely to have a remedy for such reduction in value unless they are able to successfully claim that the reduction was due to the breach by our officers or directors of a duty of care or other fiduciary duty owed to them, or if they are able to successfully bring a private claim under securities laws that the registration statement or joint proxy statement/prospectus relating to the Business Combination contained an actionable material misstatement or material omission.
If, after Plum distributes the proceeds in the trust account to the public shareholders, Plum files a bankruptcy petition or an involuntary bankruptcy petition is filed against Plum that is not dismissed, a bankruptcy court may seek to recover such proceeds, and Plum and the Plum Board may be exposed to claims of punitive damages.
If, after Plum distributes the proceeds in the trust account to the public shareholders, Plum files a winding-up or bankruptcy or insolvency petition or an involuntary winding-up or bankruptcy or insolvency petition is filed against Plum that is not dismissed, any distributions received by shareholders could be viewed under applicable debtor/creditor and/or insolvency laws as a voidable performance. As a result, a liquidator could seek to recover some or all amounts received by Plum’s shareholders. In addition, the board of directors may be viewed as having breached its fiduciary duty or having acted in bad faith, thereby exposing it and us to claims of damages. Plum cannot assure you that claims will not be brought against us for these reasons.
If, before distributing the proceeds in the trust account to the public shareholders, Plum files a bankruptcy petition or an involuntary bankruptcy petition is filed against Plum that is not dismissed, the claims of creditors in such proceeding may have priority over the claims of Plum shareholders and the per share amount that would otherwise be received by Plum Shareholders in connection with Plum’s liquidation may be reduced.
If, before distributing the proceeds in the trust account to the public shareholders, Plum files a winding-up or bankruptcy or insolvency petition or an involuntary winding-up or bankruptcy or insolvency petition is filed against Plum that is not dismissed, the proceeds held in the trust account could be subject to applicable insolvency law, and may be included in Plum’s liquidation estate and subject to the claims of third parties with priority over the claims of Plum Shareholders. To the extent any liquidation claims deplete the trust account, the per-share amount that would otherwise be received by Plum Shareholders in connection with our liquidation would be reduced.
81
Plum Shareholders may be held liable for claims by third parties against Plum to the extent of distributions received by them upon redemption of their shares.
If Plum is forced to enter into an insolvent liquidation, any distributions received by Plum Shareholders could be viewed as an unlawful payment if it was proved that, immediately following the date on which the distribution was made, Plum was unable to pay its debts as they fall due in the ordinary course of business. As a result, a liquidator could seek to recover some or all amounts received by Plum Shareholders. Furthermore, the directors may be viewed as having breached their fiduciary duties to Plum or its creditors and/or may have acted in bad faith, and thereby exposing itself and the company to claims, by paying public shareholders from the trust account prior to addressing the claims of creditors. Plum cannot assure you that claims will not be brought against Plum for these reasons.
Plum Shareholders will experience immediate dilution as a consequence of the issuance of the PubCo Common Shares as consideration in the Business Combination and the PIPE Investment.
In accordance with the terms and subject to the conditions of the Business Combination Agreement, at the Effective Time, each TRC Common Share will be cancelled and converted into the right to receive a number of PubCo Common Shares equal to the TRC Exchange Ratio. In addition, the PIPE Investors shall purchase PubCo Common Shares pursuant to the PIPE Subscription Agreements. In addition, TRC employees, directors and consultants hold, and after the Business Combination may be granted, equity awards under PubCo’s incentive plan. Plum Shareholders will experience additional dilution when those equity awards become vested and settled or exercisable, as applicable, for PubCo Common Shares.
The issuance of additional PubCo Common Shares will significantly dilute the equity interests of Plum Shareholders and may adversely affect prevailing market prices for the PubCo Common Shares and/or the PubCo Warrants.
Plum Warrants and TRC Warrants will become exercisable for PubCo Common Shares, which, if exercised, would increase the number of shares eligible for future resale in the public market and result in dilution to Plum Shareholders.
If the Business Combination is completed, outstanding warrants to purchase an aggregate of 12,059,166 PubCo Common Shares will become exercisable in accordance with the terms of the Warrant Agreement governing those securities. These warrants will become exercisable 30 days after the completion of the Business Combination. The exercise price of these warrants will be $11.50 per share. To the extent such warrants are exercised, additional shares of PubCo Common Shares will be issued, which will result in dilution to the existing holders of PubCo Common Shares and increase the number of shares eligible for resale in the public market. Sales of substantial numbers of such shares in the public market or the fact that such warrants may be exercised could adversely affect the market price of PubCo Common Shares. However, there is no guarantee that the PubCo Warrants will ever be in the money prior to their expiration, and as such, the PubCo Warrants may expire worthless.
In addition, Plum Shareholders who exercise redemption rights with respect to their Plum Shares will retain their Plum Warrants, which will become PubCo Warrants upon completion of the Business Combination and may be exercised by such redeeming shareholders for PubCo Common Shares. Such exercises of PubCo Warrants held by redeeming Plum Shareholders will result in dilution to non-redeeming shareholders.
Following the closing, there will also be outstanding (i) TRC Options to purchase up to a total of 2,085,673 PubCo Common Shares, (ii) TRC Warrants to purchase up to a total of 6,406,368 PubCo Common Shares, (iii) 3,104,561 PubCo Common Shares issuable pursuant to TRC RSUs, (iv) TRC Convertible Debt convertible into up to a total of 3,918,801 PubCo Common Shares, and (v) 1,188,950 PubCo Common Shares issuable to bankers.
The Nasdaq may not approve the listing of PubCo’s securities on its exchange, which could limit investors’ ability to make transactions in PubCo’s securities and subject PubCo to additional trading restrictions.
An active trading market for PubCo’s securities following the Business Combination may never develop or, if developed, it may not be sustained. In connection with the Business Combination, in order to continue to maintain the listing of our securities on the Nasdaq, PubCo will be required to demonstrate compliance with the Nasdaq’s listing
82
requirements. Plum will apply to have PubCo’s securities listed on the Nasdaq upon consummation of the Business Combination. We cannot assure you that PubCo will be able to meet all listing requirements. Even if PubCo’s securities are listed on the Nasdaq, PubCo may be unable to maintain the listing of its securities in the future.
If PubCo fails to meet the initial listing requirements and Nasdaq does not list its securities on its exchange, TRC and Plum would not be required to consummate the Business Combination, as applicable. In the event that TRC and Plum elected to waive this condition, and the Business Combination was consummated without PubCo’s securities being listed on Nasdaq or on another national securities exchange, PubCo could face significant material adverse consequences, including:
• a limited availability of market quotations for PubCo’s securities;
• reduced liquidity for PubCo’s securities;
• a determination that PubCo Common Shares are a “penny stock”, which will require brokers trading in PubCo Common Shares to adhere to more stringent rules and possibly result in a reduced level of trading activity in the secondary trading market for PubCo’s securities;
• a limited amount of news and analyst coverage; and
• a decreased ability to issue additional securities or obtain additional financing in the future.
The National Securities Markets Improvement Act of 1996, which is a federal statute, prevents or preempts the states from regulating the sale of certain securities, which are referred to as “covered securities.” If PubCo’s securities were not listed on Nasdaq, such securities would not qualify as covered securities and PubCo would be subject to regulation in each state in which PubCo offers its securities because states are not preempted from regulating the sale of securities that are not covered securities.
Other General Risks Related to Plum
Unless the context requires otherwise, references to “Plum,” “we,” “us” or “our” in this section are to the business and operations of Plum prior to the Business Combination.
Plum has no operating history and is subject to a mandatory liquidation and subsequent dissolution requirement. If Plum is unable to consummate a business combination, including the Business Combination, holders of Plum Shareholders may be forced to wait until after July 30, 2025, or such later date as approved by Plum’s shareholders, before receiving distributions from the Trust Account.
Plum is a development-stage blank check company and has no operating history and is subject to mandatory liquidation and subsequent dissolution requirements. Plum currently has until July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, to complete a business combination (unless such date is subsequently extended by the shareholders of Plum). Plum has no obligation to return funds to investors prior to such date unless (i) it consummates a business combination prior thereto or (ii) it seeks to amend the Plum Articles prior to consummation of a business combination, and only then in cases where investors have sought redemption of their Plum Class A Shares by Plum. Only after the expiration of this full period will holders of Plum Class A Shares be entitled to distributions from the Trust Account if Plum is unable to complete a business combination. Accordingly, investors’ funds may be unavailable to them until after such date and to liquidate their investment public security holders may be forced to sell their Plum Class A Shares or Plum Public Warrants, potentially at a loss. In addition, if Plum fails to complete an initial business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, there will be no redemption rights or liquidating distributions with respect to the Plum Public Warrants, which will expire worthless, unless Plum amends the Plum Articles to extend the time by which it must consummate an initial business combination and certain other agreements it has entered into.
83
If Plum is unable to complete the Business Combination or an alternative business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, Plum will cease all operations except for the purpose of winding up, redeem 100% of the outstanding Plum Class A Shares (other than Founder Shares) and, subject to the approval of its remaining shareholders and Plum’s board of directors, dissolve and liquidate. In such event, holders of Plum Class A Shares may only receive $10.00 per share (or less than such amount in certain circumstances) and Plum Warrants will expire worthless.
If Plum is unable to complete the Business Combination or another business combination within the required time period, Plum will (i) cease all operations except for the purpose of winding up, (ii) as promptly as reasonably possible but not more than ten (10) business days thereafter, redeem the Plum Class A Shares (other than Founder Shares), at a per-share price, payable in cash, equal to the aggregate amount then on deposit in the Trust Account, (including interest earned on the funds held in the Trust Account and not previously released to Plum to pay its taxes), divided by the number of then issued and outstanding Plum Class A Shares (other than Founder Shares), which redemption will completely extinguish the rights as shareholders of the holders of Plum Class A Shares (including the right to receive further liquidating distributions, if any); and (iii) as promptly as reasonably possible following such redemption, subject to the approval of Plum’s remaining shareholders and Plum’s board of directors, liquidate and dissolve, subject in each case to its obligations under Cayman Islands law to provide for claims of creditors and the requirements of other applicable law. In such case, holders of Plum Class A Shares may only receive $10.00 per share (or less than such amount in certain circumstances), and Plum Warrants will expire worthless. In certain circumstances, holders of Plum Class A Shares may receive less than $10.00 per share on the redemption of their Plum Class A Shares.
Plum has incurred, and expects to continue to incur, significant costs in pursuit of its acquisition plans, and it has expressed substantial doubt about its ability to continue as a “going concern”.
Plum has incurred, and expects to continue to incur, significant costs in pursuit of its acquisition plans. As of December 31, 2024, Plum had $27,418 in its operating bank account. As of December 31, 2024, Plum had a working capital deficit of $3,064,428, which was composed primarily of accrued expenses and accounts payable in connection with searching for target businesses, performing business due diligence and negotiating business combination agreements, including in connection with the Business Combination. The investigation of each specific target business and the negotiation, drafting and execution of relevant agreements, disclosure documents and other instruments require substantial management time and attention and substantial costs for accountants, attorneys and others. Plum has spent substantial time and attention and incurred significant costs in pursuing potential transactions that have not been completed and it may continue to do so. Such costs likely will not be recoverable. Furthermore, Plum may fail to complete the Business Combination or an alternative business combination for any number of reasons including those beyond its control. Any such event will result in a loss to Plum of the related costs incurred, which could adversely affect subsequent attempts to locate and acquire or merge with another business.
Plum may need to raise additional funds in order to meet the expenditures required for operating its business. However, if Plum’s estimate of the costs of consummating the Business Combination or identifying a target business, undertaking in-depth due diligence and negotiating an alternative business combination are less than the actual amount necessary to do so, it may have insufficient funds available to operate its business prior to the Business Combination or such other business combination. Moreover, Plum may need to obtain additional financing to complete the Business Combination or an alternative business combination, in which case it may issue additional securities or incur debt in connection with such business combination. If Plum has not completed its initial business combination within the required time period because it does not have sufficient funds available to it, Plum will be forced to cease operations and liquidate the Trust Account. These factors, among others, raise substantial doubt about Plum’s ability to continue as a going concern. The financial statements contained elsewhere in this proxy statement/prospectus do not include any adjustments that might result from Plum’s inability to continue as a going concern. Management’s plans to address this need are further discussed under “Plum’s Management’s Discussion and Analysis of Financial Condition and Results of Operations.” Plum’s plans to raise capital and to consummate the Business Combination or an alternative business combination may not be successful.
84
Plum may not have sufficient funds to consummate the Business Combination.
As of December 31, 2024, Plum had approximately $27,418 available to it outside the Trust Account to fund its working capital requirements. If Plum is required to seek additional capital, it would need to borrow funds from the Sponsor, its management team or other third parties to operate or it may be forced to liquidate. None of such persons is under any obligation to advance funds to Plum in such circumstances. Any such advances would be repaid only from funds held outside the Trust Account or from funds released to Plum upon completion of the Business Combination. Plum does not currently expect that the amount of working capital held outside the Trust Account will be sufficient to repay all or any portion of such loaned amounts in the event the Business Combination or another business combination is not consummated. If Plum is unable to consummate the Business Combination because it does not have sufficient funds available, Plum will be forced to cease operations and liquidate the Trust Account. Consequently, holders of Plum Class A Shares may receive less than $10.00 per share and their warrants will expire worthless.
Termination of the Business Combination Agreement could negatively impact Plum.
If the Business Combination is not completed for any reason, including as a result of Plum shareholders declining to approve the proposals required to consummate the Business Combination, the ongoing business of Plum may be adversely affected and, without realizing any of the anticipated benefits of completing the Business Combination, Plum would be subject to a number of risks, including the following:
• Plum may experience negative reactions from the financial markets, including negative impacts on the stock price of Plum Class A Shares (including to the extent that the current market price reflects a market assumption that the Business Combination will be completed);
• Plum will have incurred substantial expenses and will be required to pay certain costs relating to the Business Combination, whether the Business Combination is completed; and
• since the Business Combination Agreement restricts the conduct of Plum’s businesses prior to completion of the Business Combination, Plum may not have been able to take certain actions during the pendency of the Business Combination that would have benefitted it as an independent company, and the opportunity to take such actions may no longer be available. See “The Business Combination Agreement and Ancillary Documents — The Business Combination Agreement — Other Covenants and Agreements.”
If the Business Combination Agreement is terminated and Plum’s board of directors seeks another merger or business combination, Plum shareholders cannot be certain that Plum will be able to find another acquisition target that would constitute a business combination that such other merger or business combination will be completed by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders. See “The Business Combination Agreement and Ancillary Documents — The Business Combination Agreement — Termination.”
In the event of liquidation by Plum, third parties may bring claims against Plum and, as a result, the proceeds held in the Trust Account could be reduced and the per-share liquidation price received by Plum Shareholders could be less than $10.00 per share.
Under the terms of the Plum Articles, Plum must complete the Business Combination or an alternative business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, or Plum must cease all operations except for the purpose of winding up, redeem 100% of the outstanding Plum Class A Shares (other than Founder Shares) and, subject to the approval of its remaining shareholders and Plum’s board of directors, dissolve and liquidate. In such event, third parties may bring claims against Plum.
The Sponsor has agreed that it will be liable if and to the extent any claims by a third party (other than the independent auditors) for services rendered or products sold to Plum, or a prospective target business with which Plum has discussed entering into a transaction agreement, reduce the amount of funds held in the Trust Account to below (1) $10.00 per Plum Class A Share or (2) such lesser amount per Plum Class A Share held in the Trust Account as of the date of the liquidation of the Trust Account, due to reductions in value of the trust assets, in each case net of the amount of interest which may be withdrawn to pay taxes, except as to any claims by a third party who executed a waiver of any and all rights to seek access to the Trust Account and except as to any claims under the indemnity of the underwriters of the IPO against certain liabilities, including liabilities under the Securities Act. In the event that
85
an executed waiver is deemed to be unenforceable against a third party, then the Sponsor will not be responsible to the extent of any liability for such third-party claims. Plum has not independently verified whether the Sponsor has sufficient funds to satisfy its indemnity obligations and believes that the Sponsor’s only assets are securities of Plum and, therefore, the Sponsor may not be able to satisfy those obligations. None of Plum’s other officers will indemnify it for claims by third parties including, without limitation, claims by vendors and prospective target businesses.
Additionally, if Plum is forced to file a bankruptcy case or an involuntary bankruptcy case is filed against it which is not dismissed, or if Plum otherwise enters compulsory or court supervised liquidation, the proceeds held in the Trust Account could be subject to applicable bankruptcy law and may be included in its bankruptcy estate.
Plum may be a target of securities class action and derivative lawsuits which could result in substantial costs and may delay or prevent the Business Combination from being completed.
Securities class action lawsuits and derivative lawsuits are often brought against companies that have entered into business combination agreements or similar agreements. Even if the lawsuits are without merit, defending against these claims can result in substantial costs and divert management time and resources. An adverse judgment could result in monetary damages, which could have a negative impact on Plum’s liquidity and financial condition. Additionally, if a plaintiff is successful in obtaining an injunction prohibiting consummation of the Business Combination, then that injunction may delay or prevent the Business Combination from being completed. Currently, Plum is not aware of any securities class action lawsuits or derivative lawsuits being filed in connection with the Business Combination.
Plum’s securities have been delisted by Nasdaq and are no longer listed on a national securities exchange, which could make it more difficult to consummate the Business Combination.
Plum’s securities were previously listed on Nasdaq. On January 27, 2025, Plum’s securities were suspended on Nasdaq with immediate effect after Plum gave notice that it would be unable to regain compliance with Nasdaq’s continued listing requirements. On January 28, 2025, Plum Class A Shares, warrants and units were listed and began trading on the Pink Current tier of the OTC Markets. Plum Class A Shares, warrants and units are listed under the symbols “PLMJF”, “PLMWF”, and “PLMUF”.
As a result of being traded on the over-the-counter market, Plum could face significant material adverse consequences, including:
• a limited availability of market quotations for its securities;
• reduced liquidity for its securities;
• a limited amount of news and analyst coverage;
• a decreased ability to issue additional securities or obtain additional financing in the future; and
• being subject to regulation in each state in which Plum offers its securities.
Additionally, the National Securities Markets Improvement Act of 1996, which is a federal statute, prevents or preempts the states from regulating the sale of certain securities, which are referred to as “covered securities.” Because Plum’s securities are no longer listed on a national securities exchange, they would not be considered covered securities. As a result, Plum’s securities would be subject to regulation in each state in which it offers its securities. However, since the Business Combination is structured such that PubCo is issuing its securities, rather than Plum, and PubCo’s securities are expected to be listed on Nasdaq upon the closing of the Business Combination, it is not expected that such designation will have a negative impact on the parties’ ability to consummate the Business Combination. Nevertheless, there is no assurance that a state could not seek to hinder or delay the Business Combination, which could possibly lead to Plum being forced to dissolve and liquidate. While we are not aware of a state having used these powers to prohibit or restrict the sale of securities issued by SPACs, certain state securities regulators view blank check companies unfavorably and might use these powers, or threaten to use these powers, to hinder the sale of securities of blank check companies in their states. Further, if Plum’s securities no longer not qualify as covered securities under such statute and Plum may be subject to regulation in each state in which it offers its securities.
If Plum fails to meet criteria set forth in Rule 15c2-11 (the “Rule”) under the Exchange Act (for example, by failing to file periodic reports as required by the Exchange Act), various practice requirements are imposed on broker-dealers who sell securities governed by the Rule to persons other than established customers and accredited investors. For these types
86
of transactions, the broker-dealer must make a special suitability determination for the purchaser and have received the purchaser’s written consent to the transactions prior to sale. Consequently, the Rule may have a material adverse effect on the ability of broker-dealers to sell Plum securities, which may materially affect the ability of investors to sell the securities in the secondary market. Not being listed on a national securities exchange may make trading Plum securities difficult for investors, potentially leading to declines in the share price. It may also make it more difficult for Plum to raise additional capital.
Plum is a Shell Company with Penny Stock.
Plum is a blank check company incorporated on February 5, 2021 as a Cayman Islands exempted company formed for the purpose of effecting a merger, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses or entities. As a result, Plum is a shell company. Rule 405 and 12b-2 of the Exchange Act defines a shell company as an issuer that that has no or nominal operations and either (i) no or nominal assets, (ii) assets consisting solely of cash and cash equivalents; or (iii) assets consisting of any amount of cash and cash equivalents and nominal other assets.
Plum Class A Shares are a “penny stock,” as defined in Rule 3a51-1 promulgated by the SEC under the Exchange Act. The penny stock rules require a broker-dealer, prior to a transaction in penny stock not otherwise exempt from the rules, to deliver a standardized risk disclosure document that provides information about penny stocks and the nature and level of risks in the penny stock market. These disclosure rules have the effect of reducing the level of trading activity in the secondary market for a stock that becomes subject to the penny stock rules. So long as the Plum Class A Shares are subject to the penny stock rules, it may be more difficult to sell Plum Class A Shares.
A shell issuer may also be a blank check company or a blind pool company, a company in the developmental stage, any company that has no specific business plan or purpose, or a company that has as its business plan to merge with or acquire an unidentified third property. Accordingly, Plum may be required, under current and proposed new rules and amendments of the SEC, to provide enhanced disclosures for investor protection in the event that we engage in a merger or acquisition with an unidentified company substantially similar to those required in registration statements for an initial public offering.
If third parties bring claims against Plum, the proceeds held in trust could be reduced and the per-share redemption price received by shareholders may be less than $10.00 per share.
Plum’s placing of funds in trust may not protect those funds from third-party claims against Plum. Although Plum has sought to have all vendors and service providers it engages and prospective target businesses it negotiated with execute agreements with Plum waiving any right, title, interest or claim of any kind in or to any monies held in the Trust Account for the benefit of Plum’s public shareholders, they may not execute such agreements. Furthermore, even if such entities execute such agreements with Plum, they may seek recourse against the Trust Account. A court may not uphold the validity of such agreements. Accordingly, the proceeds held in trust could be subject to claims which could take priority over those of Plum’s public shareholders. If Plum is unable to complete a business combination and distribute the proceeds held in trust to Plum’s public shareholders, the Sponsor has agreed (subject to certain exceptions described elsewhere in this proxy statement/prospectus) that it will be liable to ensure that the proceeds in the Trust Account are not reduced below $10.00 per share by the claims of target businesses or claims of vendors or other entities that are owed money by Plum for services rendered or contracted for or products sold to Plum. However, it may not be able to meet such obligation. Therefore, the per-share distribution from the Trust Account may be less than $10.00, plus interest, due to such claims.
Additionally, if Plum is forced to file a bankruptcy case or an involuntary bankruptcy case is filed against Plum which is not dismissed, the proceeds held in the Trust Account could be subject to applicable bankruptcy law, and may be included in Plum’s bankruptcy estate and subject to the claims of third parties with priority over the claims of Plum’s shareholders. To the extent any bankruptcy claims deplete the Trust Account, Plum may not be able to return to Plum’s public shareholders at least $10.00. The Sponsor may not have sufficient funds to satisfy its indemnity obligations, as we believe its only assets are securities of Plum. Plum has not asked the Sponsor to reserve for such indemnification obligations. As a result, if any such claims were successfully made against the Trust Account, the funds available for Plum’s initial business combination, including the Business Combination, and redemptions could be reduced to less than $10.00 per Plum Class A Share.
87
Changes to laws or regulations or in how such laws or regulations are interpreted or applied, or a failure to comply with any laws, regulations, interpretations or applications, may adversely affect Plum’s business, including its ability to negotiate and complete the Business Combination or an alternative business combination.
Plum is subject to the laws and regulations, and interpretations and applications of such laws and regulations, of national, regional, state and local governments and, potentially, non-U.S. jurisdictions. In particular, Plum is required to comply with certain SEC and potentially other legal and regulatory requirements, and its consummation of an initial business combination, including the Business Combination, may be contingent on its ability to comply with certain laws, regulations, interpretations and applications and any post-business combination company, including PubCo, may be subject to additional laws, regulations, interpretations and applications. Compliance with, and monitoring of, the foregoing may be difficult, time consuming and costly. Those laws and regulations and their interpretation and application may also change from time to time, and those changes could have a material adverse effect on Plum’s business, including its ability to complete the Business Combination or negotiate and complete an alternative business combination. A failure to comply with applicable laws or regulations, as interpreted and applied, could have a material adverse effect on Plum’s business, including its ability to complete the Business Combination or negotiate and complete an alternative business combination.
On January 24, 2024, the SEC adopted a series of new rules relating to SPACs (the “SPAC Rules”) requiring, among other items, (i) additional disclosures relating to SPAC business combination transactions; (ii) additional disclosures relating to dilution and to conflicts of interest involving sponsors and their affiliates in both SPAC initial public offerings and SPAC initial business combinations (“de-SPAC transactions”); (iii) the use of projections by SPACs in SEC filings in connection with proposed business combination transactions; and (iv) both the SPAC and the target company’s status as co-registrants on de-SPAC transaction registration statements with respect to the issuance of securities of a SPAC.
In addition, the SEC’s adopting release provided guidance describing circumstances in which a SPAC could become subject to regulation under the Investment Company Act, including its duration, asset composition, business purpose, and the activities of the SPAC and its management team in furtherance of such goals.
Compliance with the SPAC Rules and related guidance may increase the costs of and the time needed to complete the Business Combination or negotiate and complete an alternative business combination and may constrain the circumstances under which Plum could complete an initial business combination, including the Business Combination.
If Plum is deemed to be an investment company under the Investment Company Act, it may be required to institute burdensome compliance requirements and its activities may be restricted, which may make it difficult for it to complete an initial business combination.
As described above, the SEC’s adopting release with respect to the SPAC Rules provided guidance describing the extent to which SPACs could become subject to regulation under the Investment Company Act and the regulations thereunder. Whether a SPAC is an investment company will be a question of facts and circumstances. We can give no assurance that a claim will not be made that Plum has been operating as an unregistered investment company.
If Plum is deemed to be an investment company under the Investment Company Act, its activities may be restricted, including:
• restrictions on the nature of its investments, if any; and
• restrictions on the issuance of securities, each of which may make it difficult for Plum to complete its initial business combination, including the Business Combination.
In addition, Plum may be imposed with burdensome requirements, including:
• registration as an investment company;
• adoption of a specific form of corporate structure; and
• reporting, record keeping, voting, proxy and disclosure requirements and other rules and regulations.
In order not to be regulated as an investment company under the Investment Company Act, unless Plum can qualify for an exclusion, it must ensure that it is engaged primarily in a business other than investing, reinvesting or trading in securities and that its activities do not include investing, reinvesting, owning, holding or trading “investment securities” constituting more than 40% of its total assets (exclusive of U.S. government securities and cash items) on an unconsolidated basis.
88
We do not believe that Plum’s anticipated activities will subject it to the Investment Company Act. To mitigate the risk that it might be deemed to be an investment company for purposes of the Investment Company Act, in January 2024, Plum instructed the trustee to liquidate the investments held in the Trust Account and instead to hold the funds in the Trust Account in an interest-bearing demand deposit account at a bank until the earlier of the consummation of its initial business combination or its liquidation.
However, if Plum is deemed to be an investment company and subject to compliance with and regulation under the Investment Company Act, it would be subject to additional regulatory burdens and expenses for which it has not allotted funds. As a result, if Plum is deemed to be an investment company, unless it is able to modify its activities so that it would not be deemed an investment company, it may abandon its efforts to complete a business combination and instead liquidate. Holders of Plum Class A Shares may receive only approximately $[•] per share on the liquidation of the Trust Account (based on the amount in the Trust Account as of [•], 2025 and including interest not previously released to pay taxes) and the Plum Warrants will expire worthless.
Plum’s directors may decide not to enforce the indemnification obligations of the Sponsor, resulting in a reduction in the amount of funds held in the Trust Account available for distribution to holders of Plum Class A Shares in the event a business combination is not consummated.
If proceeds in the Trust Account are reduced below $10.00 per Plum Class A Share and the Sponsor asserts that it is unable to satisfy its indemnification obligations or that it has no indemnification obligations related to a particular claim, Plum’s independent directors would determine whether to take legal action against the Sponsor to enforce its indemnification obligations. While Plum currently expects that its independent directors would take legal action on Plum’s behalf against the Sponsor to enforce the Sponsor’s indemnification obligations, it is possible that Plum’s independent directors in exercising their business judgment may choose not to do so in any particular instance. If Plum’s independent directors choose not to enforce these indemnification obligations, the amount of funds held in the Trust Account available for distribution to holders of Plum Class A Shares may be reduced below $10.00 per share.
Plum’s ability to consummate an initial business combination may be adversely affected by economic uncertainty and volatility in the financial markets, including as a result of the military conflicts in Ukraine and the Middle East.
Recent increases in inflation and interest rates in the United States and elsewhere, military conflict in the Ukraine, Middle East or elsewhere, and other economic or geopolitical events, may lead to increased price volatility for publicly-traded securities, including Plum’s, and may lead to other national, regional and international economic disruptions or economic uncertainty, and of which could make it more difficult for us to consummate the Business Combination.
Additionally, in the U.S. and other jurisdictions, central banks have undertaken efforts to combat inflation by raising interest rates, which increase the likelihood of a slowdown in U.S. and global economic growth, and which in turn, have caused, and may continue to cause, declines in the prices of financial assets in the public and private markets as investors react to these and other economic developments. This has also caused, and may continue to cause, market volatility and downward price pressure on the capital markets, which may negatively impact Plum’s ability to consummate a business combination, including the Business Combination.
If the Business Combination is not completed, potential target businesses may have leverage over Plum in negotiating an initial business combination, Plum’s ability to conduct due diligence on a potential target may decrease as Plum approaches its business combination deadline, and it may have insufficient working capital to continue to pursue one or more potential target businesses, each of which could undermine its ability to complete an initial business combination on terms that would produce value for Plum Shareholders.
Any potential target business with which Plum enters into negotiations concerning an initial business combination will be aware that, unless Plum amends the Plum Articles to extend the business combination deadline and amend certain other agreements it has entered into, Plum must complete its initial business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders. Consequently, if Plum is unable to complete the Business Combination, a potential target business may obtain leverage over it in negotiating an initial business combination, knowing that if Plum does
89
not complete its initial business combination with that particular target business, it may be unable to complete its initial business combination with any target business. This risk will increase as Plum gets closer to the business combination deadline. In addition, Plum may have limited time to conduct due diligence and may enter into its initial business combination on terms that it would have rejected upon a more comprehensive investigation. Additionally, Plum may have insufficient working capital to continue efforts to pursue a business combination.
Plum shareholders may be held liable for claims by third parties against Plum to the extent of distributions received by them.
If Plum is unable to complete the Business Combination or an alternative business combination prior to the business combination deadline, Plum will (i) cease all operations except for the purpose of winding up, (ii) as promptly as reasonably possible but not more than ten (10) business days thereafter, redeem 100% of the outstanding Plum Class A Shares (other than Founder Shares), at a per-share price, payable in cash, equal to the aggregate amount then on deposit in the Trust Account (including interest earned on the funds held in the Trust Account and not previously released to Plum to pay its taxes), divided by the number of then-outstanding Plum Class A Shares (excluding Founder Shares), which redemption will completely extinguish the rights of holders of Plum Class A Shares as shareholders (including the right to receive further liquidation distributions, if any), subject to applicable law, and (iii) as promptly as reasonably possible following such redemption, subject to the approval of Plum’s remaining shareholders and Plum’s board of directors, dissolve and liquidate, subject in each case to its obligations under Cayman Islands law to provide for claims of creditors and the requirements of other applicable law. Plum cannot assure you that it will properly assess all claims that may be potentially brought against Plum. As a result, Plum Shareholders could potentially be liable for any claims to the extent of distributions received by them (but no more) and any liability of its shareholders may extend well beyond the third anniversary of the date of distribution. Accordingly, Plum cannot assure you that third parties will not seek to recover from its shareholders amounts owed to them by Plum.
Additionally, if Plum files a winding-up or bankruptcy petition or an involuntary winding-up or bankruptcy petition is filed against it that is not dismissed, any distributions received by shareholders could be viewed under applicable debtor/creditor and/or insolvency laws as a voidable performance or preference. As a result, a bankruptcy court could seek to recover some or all amounts received by Plum Shareholders. Furthermore, Plum’s board of directors may be viewed as having breached its fiduciary duty to its creditors and/or may have acted in bad faith, and thereby exposing itself and Plum to claims of punitive damages, by paying holders of Plum Class A Shares from the Trust Account prior to addressing the claims of creditors. Plum cannot assure you that claims will not be brought against it for these reasons.
In Plum’s Annual Report on Form 10-K for the year ended December 31, 2024, it reported a material weakness in its internal control over financial reporting.
In connection with the preparation of Plum’s audited consolidated financial statements for the year ended December 31, 2024, Plum’s management identified a material weaknesses in its internal control over financial reporting as of December 31, 2024. A material weakness is a deficiency, or a combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of our annual or interim financial statements will not be prevented or detected on a timely basis.
The material weakness identified relates to the compliance with an agreement it entered during the fiscal year ended December 31, 2023, and the recording of necessary accruals in relation to recording of accruals and stock-based compensation. While Plum has processes in place to identify and appropriately apply applicable accounting requirements, it did not identify certain stipulations in the Trust Agreement, and accordingly failed to make appropriate accounting entries.
Plum management has implemented remediation steps to improve its internal control over financial reporting. However, Plum cannot assure investors that its efforts will be effective or prevent any future material weakness or significant deficiency in its internal control over financial reporting. If Plum is unable to remediate the identified deficiency or maintain effective internal controls, it may fail to accurately report our results or prevent the occurrence of malpractices or errors. Failure or ineffectiveness in our internal controls could have a material adverse effect on the business.”
90
Risks Related to the Business Combination
TRC and Plum have no history operating as a combined company. The unaudited pro forma condensed combined financial information may not be an indication of PubCo’s financial condition or results of operations following the Business Combination, and accordingly, you have limited financial information on which to evaluate TRC and your investment decision.
TRC and Plum have no prior history as a combined entity and their operations have not been previously managed on a combined basis. The unaudited pro forma condensed combined financial information contained in this proxy statement/prospectus has been prepared using the consolidated historical financial statements of Plum and TRC, and is presented for illustrative purposes only and should not be considered to be an indication of the results of operations including, without limitation, future revenue, or financial condition of PubCo following the Business Combination. Certain adjustments and assumptions have been made regarding TRC after giving effect to the Business Combination. TRC and Plum believe these assumptions are reasonable, however, the information upon which these adjustments and assumptions have been made is preliminary, and these kinds of adjustments are difficult to make with accuracy. These assumptions may not prove to be accurate, and other factors may affect PubCo’s results of operations or financial condition following the consummation of the Business Combination. For these and other reasons, the historical and pro forma condensed combined financial information included in this proxy statement/prospectus does not necessarily reflect TRC’s results of operations and financial condition and the actual financial condition and results of operations of PubCo following the Business Combination may not be consistent with, or evident from, this pro forma financial information.
If the benefits of the Business Combination or the valuation of TRC in the Business Combination do not meet the expectations of investors or securities analysts, the value of, prior to the Business Combination, Plum’s securities or, following the Business Combination, PubCo’s securities, may decline.
If the benefits of the Business Combination or the valuation of TRC in the Business Combination do not meet the expectations of investors or securities analysts, the market price of the Plum Class A Shares prior to the consummation of the Business Combination may decline. The trading prices of the Plum Class A Shares at the time of the Business Combination may vary significantly from their trading prices on the date the Business Combination Agreement was executed, the date of this proxy statement/prospectus, or the date on which Plum Shareholders vote to approve the Business Combination. Because the number of PubCo Shares to be issued pursuant to the Business Combination Agreement will not be adjusted to reflect any changes in the market price of the Plum Class A Shares, the trading price of Plum Class A Shares issued in the Business Combination may be higher or lower than the values of these shares on earlier dates.
In addition, following the Business Combination, fluctuations in the trading price of PubCo Shares could contribute to the loss of all or part of your investment. Prior to the Business Combination, there has not been a public market for TRC’s securities. Accordingly, the valuation ascribed to TRC in the Business Combination may not be indicative of the price that will prevail in the trading market following the Business Combination. If an active market for TRC’s securities develops and continues, the trading price of PubCo Shares following the Business Combination could be volatile and subject to wide fluctuations in response to various factors, some of which are beyond PubCo’s control. Any of the factors listed below could have a material adverse effect on your investment in shares PubCo Shares and PubCo Shares may trade at prices significantly below the price you paid for them. In such circumstances, the trading price of PubCo Shares may not recover and may experience a further decline.
Factors affecting the trading price of PubCo Shares may include:
• actual or anticipated fluctuations in PubCo’s quarterly and annual financial results or the quarterly or annual financial results of companies perceived to be similar to PubCo;
• changes in the market’s expectations about PubCo’s operating results;
• success of competitors;
• PubCo’s operating results failing to meet the expectation of securities analysts or investors in a particular period;
91
• changes in financial estimates and recommendations by securities analysts concerning PubCo or the industries in which PubCo operates in general;
• operating and share price performance of other companies that investors deem comparable to PubCo;
• changes in laws and regulations affecting PubCo’s business;
• commencement of, or involvement in, litigation involving PubCo;
• changes in PubCo’s capital structure, such as future issuances of securities or the incurrence of additional debt;
• the volume of PubCo Shares available for public sale;
• any major change in PubCo’s board of directors or management;
• sales of substantial amounts of PubCo Shares by PubCo’s directors, executive officers or significant shareholders or the perception that such sales could occur;
• general economic and political conditions such as recessions, interest rates, international currency fluctuations and acts of war or terrorism; and
• occurrence of natural disasters, pandemics or other unanticipated catastrophes.
Broad market and industry factors may materially harm the trading price of PubCo Shares irrespective of PubCo’s operating performance. The stock market in general has experienced price and volume fluctuations that have often been unrelated or disproportionate to the operating performance of the particular companies affected. The trading prices and valuations of these stocks, and of PubCo Common Shares, may not be predictable. A loss of investor confidence in the market for the stocks of other companies that investors perceive to be similar to PubCo could depress its share price regardless of its business, prospects, financial conditions, or results of operations. A decline in the trading price of PubCo Shares also could adversely affect PubCo’s ability to issue additional securities and its ability to obtain additional financing in the future.
The consummation of the Business Combination is subject to a number of conditions, many of which are beyond the control of TRC and Plum, including the approval of the Plum Shareholders.
The Business Combination is subject to a number of conditions, including the condition that there is no legal prohibition against consummation of the Business Combination, that the PubCo Shares issued in connection with the Business Combination be approved for listing on Nasdaq subject only to official notice of issuance thereof and the requirement to have a sufficient number of round lot holders, receipt of shareholder approvals, continued effectiveness of the Registration Statement (of which this proxy statement/prospectus is a part), the truth and accuracy of Plum’s and TRC’s representations and warranties made in the Business Combination Agreement, the non-termination of the Business Combination Agreement and consummation of certain ancillary agreements. There are no assurances that all conditions to the Business Combination will be satisfied or that the conditions will be satisfied in the time frame expected.
If the conditions to the Business Combination are not met (and are not waived, to the extent waivable), either Plum or TRC may, subject to the terms and conditions of the Business Combination Agreement, terminate the Business Combination Agreement. See the section of this proxy statement/prospectus entitled “The Business Combination Agreement and Ancillary Documents — The Business Combination Agreement — Termination.”
The exercise of Plum’s directors’ and officers’ discretion in agreeing to changes or waivers in the terms of the Business Combination may result in a conflict of interest when determining whether such changes to the terms of the Business Combination or waivers of conditions are appropriate and in Plum Shareholders’ best interest.
In the period leading up to the closing of the Business Combination, events may occur that would require Plum to agree to amend the Business Combination Agreement, to consent to certain actions taken by TRC or to waive rights that Plum is entitled to under the Business Combination Agreement. Waivers may arise because of changes in the course of TRC’s business, a request by TRC to undertake actions that would otherwise be prohibited by the terms of the Business Combination Agreement or the occurrence of other events that would
92
have a material adverse effect on TRC’s business and would entitle Plum to terminate the Business Combination Agreement. In any of such circumstances, it would be at Plum’s discretion, acting through Plum’s board of directors, to grant its consent or waive those rights. The existence of the financial and personal interests of the directors and officers described in the following risk factors may result in a conflict of interest on the part of one or more of the directors or officers between what they may believe is best for Plum and what they may believe is best for themselves in determining whether to take the requested action. As of the date of this proxy statement/prospectus, Plum does not believe there will be any changes or waivers that Plum’s directors and officers would be likely to make after shareholder approval of the Business Combination Proposal has been obtained. While certain changes could be made without further shareholder approval, Plum will circulate a new or amended proxy statement/prospectus and resolicit Plum’s shareholders if changes to the terms of the Business Combination would have a material impact on its shareholders or represent a fundamental change in the proposals being voted upon.
TRC will be subject to business uncertainties and contractual restrictions while the Business Combination is pending.
Uncertainty about the effect of the Business Combination may have an adverse effect on TRC and consequently on Plum. These uncertainties may impair TRC’s ability to attract, retain and motivate key personnel until the Business Combination is completed and could cause others that deal with TRC to seek to change existing business relationships with TRC. Retention of certain employees may be challenging during the pendency of the Business Combination as certain employees may experience uncertainty about their future roles. If key employees depart because of issues relating to the uncertainty and difficulty of integration or a desire not to remain with the business, TRC’s business following the Business Combination could be negatively affected. In addition, the Business Combination Agreement restricts TRC from making certain expenditures and taking other specified actions without the consent of Plum until the Business Combination occurs. These restrictions may prevent TRC from pursuing attractive business opportunities that may arise prior to the completion of the Business Combination. See “The Business Combination Agreement and Ancillary Documents — The Business Combination Agreement — Other Covenants and Agreements.”
During the pendency of the Business Combination, Plum and TRC may not be able to enter into a business combination with another party because of restrictions in the Business Combination Agreement, which could adversely affect their respective businesses and the Business Combination Agreement may discourage third parties from submitting alternative takeover proposals, including proposals that may be superior to the arrangements contemplated by the Business Combination Agreement.
Covenants in the Business Combination Agreement impede the ability of Plum and TRC to make acquisitions or complete other transactions that are not in the ordinary course of business during the pendency of the Business Combination. As a result, if the Business Combination is not completed, the parties may be at a disadvantage to their competitors during that period. In addition, while the Business Combination Agreement is in effect, each party is generally prohibited from soliciting, initiating, encouraging or entering into certain extraordinary transactions, such as a business combination, sale of assets or other business combination outside the ordinary course of business, with any third party. Any such transactions could be favorable to such party’s shareholders.
Citigroup Global Markets, Inc., Morgan Stanley & Co. LLC and William Blair & Company, L.L.C., the underwriters for Plum’s IPO, were to be compensated in part on a deferred basis for already-rendered underwriting services in connection with the IPO, yet the underwriters gratuitously waived their entitlement to such compensation and terminated their association with Plum.
Pursuant to that certain Underwriting Agreement, dated July 27, 2021 (“Underwriting Agreement”), by and between Plum and Citigroup Global Markets, Inc. (“Citigroup”), as the representative for the underwriters party thereto, Citigroup, Morgan Stanley & Co. LLC and William Blair & Company, L.L.C. (the “Underwriters”), the underwriters for Plum’s IPO, were entitled to approximately $9,887,500 in deferred underwriting fees as consideration for services rendered to Plum in connection with the IPO, which were to become payable upon consummation of a business combination transaction. On December 27, 2023, the underwriters terminated their association with Plum and gratuitously waived any fees and compensation in connection with such association, including their entitlement to the payment of deferred compensation. Investors should not place any reliance on the fact that the Underwriters were involved in Plum’s IPO.
93
The Underwriters did not specify reasons for their termination of their association with Plum and gratuitous waiver of any fees and compensation in connection with such association. Further, the Underwriters were not involved in the Business Combination and have no further ongoing relationship with Plum. The Underwriters were not involved in the preparation of any disclosure that is included in this proxy statement/prospectus, including any analysis underlying such disclosure. The deferred underwriting fee was to be paid in consideration of services rendered in connection with the IPO, and such services have already been rendered. The Underwriters received no additional consideration for the waiver of their entitlement to the deferred underwriting fee. Investors should be aware that the waiver of deferred underwriting fee is unusual and some investors may find the Business Combination less attractive as a result. This may make it more difficult for Plum to complete the Business Combination.
Although the Underwriters waived their rights to deferred compensation, Plum continues to have certain potentially material obligations to the Underwriters under the Underwriting Agreement. These obligations include a customary obligation to indemnify each Underwriter and certain affiliates and control persons against certain losses, claims, damages or liabilities, to which they or any of them may become subject under the Securities Act, the Exchange Act or other U.S. federal or state statutory law or regulation, at common law or otherwise.
The Underwriting Agreement also contains a contribution provision in the event the indemnification obligations described above are unavailable or otherwise prohibited by law.
Legal proceedings in connection with the Business Combination, the outcomes of which are uncertain, could delay or prevent the completion of the Business Combination.
Lawsuits may be filed against Plum or its directors and officers in connection with the Business Combination. Defending such additional lawsuits could require Plum to incur significant costs and draw the attention of Plum’s management team away from the Business Combination. Further, the defense or settlement of any lawsuit or claim that remains unresolved at the time the Business Combination is consummated may adversely affect the combined company’s business, financial condition, results of operations and cash flows. Such legal proceedings could delay or prevent the Business Combination from becoming effective within the agreed upon timeframe.
Currently, there is no material litigation, arbitration or governmental proceeding currently pending against TRC, Plum or any members of TRC or Plum’s management team in their capacity as such, and TRC and Plum and the respective members of each company’s management team have not been subject to any such proceeding in the 12 months preceding the date hereof.
Changes in laws or regulations, or a failure to comply with any laws and regulations, may adversely affect the ability of the parties to consummate the proposed Business Combination.
Plum and TRC are subject to laws and regulations enacted by national, regional and local governments. In particular, the Plum and TRC are required to comply with certain SEC and other legal requirements, including the SPAC Rules, and the proposed Business Combination may be contingent on their ability to comply with certain laws and regulations and any post-business combination company may be subject to additional laws and regulations. Compliance with, and monitoring of, applicable laws and regulations may be difficult, time consuming and costly. A failure to comply with applicable laws or regulations, as interpreted and applied, could have a material adverse effect on TRC’s business, including TRC’s ability to negotiate and complete the proposed Business Combination, and results of operations. In addition, those laws and regulations and their interpretation and application may change from time to time, including as a result of changes in economic, political, social and government policies, and those changes could have a material adverse effect on our business, including our ability to negotiate and complete the proposed Business Combination, and results of operations.
These rules may materially adversely affect the ability to negotiate and complete the Business Combination and may increase the costs and time related thereto. The need for compliance with the SPAC Rules may cause our Sponsor to liquidate the funds in the trust account or liquidate at an earlier time than we or the Sponsor might otherwise choose. If Plum were to liquidate, Plum Shareholders would not be able to realize the benefits of owning stock in a successor operating business, including the potential appreciation in the value of the stocks and warrants following such a transaction.
94
Plum and TRC have incurred, and expect to continue to incur, significant transaction costs in connection with the Business Combination.
Plum and TRC have both incurred and expect to continue to incur significant, non-recurring costs in connection with consummating the Business Combination and operating as a public company following the consummation of the Business Combination. All expenses incurred in connection with the Business Combination, including all legal, accounting, consulting, investment banking and other fees, expenses and costs, will be paid by PubCo following the Closing.
Plum’s board of directors has potential conflicts of interest in recommending that Plum Shareholders vote in favor of approval of the Business Combination Agreement and the transactions contemplated thereby, including the Business Combination, and approval of the other proposals described in this proxy statement/prospectus.
When considering the recommendation of Plum’s board of directors that Plum Shareholders vote in favor of the approval of the Business Combination, Plum Shareholders should be aware that Plum’s directors and executive officers, and entities affiliated with them, have interests in the Business Combination that may be different from, or in addition to, the interests of Plum Shareholders generally. These interests include:
• Pursuant to the Plum Articles, the Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares and have agreed to waive redemption rights with respect to any Plum Public Shares held by them in connection with the consummation of the Initial Business Combination. Additionally, Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares held by them if Plum fails to consummate the Initial Business Combination by July 30, 2025 or such later date as approved by Plum’s shareholders. If Plum does not complete the Initial Business Combination within such applicable time period, the proceeds of the sale of the Plum Private Placement Warrants held in the Trust Account will be used to fund the redemption of the Plum Public Shares, and the Plum Private Placement Warrants will expire without the receipt of any value by the holders of such warrants. Since Sponsor and Plum management directly or indirectly own Plum Common Shares and Plum Private Placement Warrants, Plum management may have a conflict of interest in determining whether a particular target business is an appropriate business with which to effectuate the Initial Business Combination.
• The fact that Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•];
• The fact that given the differential in the purchase price that Sponsor paid for the Plum Founder Shares as compared to the price of the Plum Units sold in the Plum IPO and the 3,902,648 PubCo Common Shares that Sponsor will receive upon conversion of the Plum Founder Shares in connection with the Business Combination, Sponsor and its affiliates may earn a positive rate of return on their investment even if the PubCo Common Shares trade below the price initially paid for the Plum Units in the Plum IPO and the Plum Public Shareholders experience a negative rate of return following the completion of the Business Combination;
• The fact that Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting’
• The fact that certain members of Plum management collectively own, directly or indirectly, a material interest in Sponsor;
• Sponsor and Plum management may have a conflict of interest with respect to evaluating a business combination and financing arrangements as Plum may obtain loans from Sponsor or an affiliate of Sponsor or any of Plum management to finance transaction costs in connection with the Initial Business Combination;
95
• The Plum Articles provide that Plum renounces any interest or expectancy in, or in being offered an opportunity to participate in, any potential transaction or matter which may be a corporate opportunity for any member of Plum management on the one hand, and Plum, on the other hand, or the participation of which would breach any existing legal obligation, under applicable law or otherwise, of a member of Plum management to any other entity. Plum is not aware of any such corporate opportunities not being offered to Plum and does not believe that waiver of the corporate opportunities doctrine has materially affected Plum’s search for an acquisition target or will materially affect Plum’s ability to complete an Initial Business Combination;
• If the Trust Account is liquidated, including in the event Plum is unable to complete an Initial Business Combination within the required time period, Sponsor has agreed to indemnify Plum to ensure that the proceeds in the Trust Account are not reduced below $10.00 per Plum Public Share, or such lesser amount per Plum Public Share as is in the Trust Account on the liquidation date, by the claims of (a) any third party (other than Plum’s independent public accountants) for services rendered or products sold to Plum or (b) a prospective target business with which Plum has entered into a letter of intent, confidentiality or other similar agreement or business combination agreement, but only if such a third party or target business has not executed a waiver of all rights to seek access to the Trust Account;
• The fact that the Company has borrowed certain amounts from the Sponsor pursuant to a promissory note which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants at a price of $1.50 per warrant, to be issued at Closing;
• The fact that Sponsor will benefit from the completion of an Initial Business Combination and may be incentivized to complete an acquisition of a less favorable target company or on terms less favorable to Plum Shareholders rather than liquidate;
• The fact that PubCo will indemnify Sponsor and its affiliates and their respective present and former directors and officers for a period of six years from the Closing, in connection with any claim, action, suit, proceeding or investigation arising out of or pertaining to the Business Combination and Sponsor’s ownership of Plum Securities or its control or ability to influence Plum;
• The terms and provisions of the Related Agreements as set forth in detail under the subsection entitled “The Business Combination — Related Agreements.”
In addition, members of TRC’s board of directors, management and various service providers of TRC have numerous contractual relationships with TRC of which the TRC board of directors was aware when it approved TRC entering into the Business Combination Agreement. Therefore, these individuals may have conflicts of interest in entering into and negotiating the terms of the Business Combination Agreement. For a complete description of these relationships, see “Certain Relationships and Related Transactions — TRC Relationships and Related Party Transactions”.
The Sponsor and the Chief Executive Officer and Chairman of Plum own Founder Shares that will be worthless if the Business Combination is not approved. Such interests may have influenced their decision to approve the Business Combination.
If the Business Combination with TRC or another business combination is not consummated by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, Plum will cease all operations except for the purpose of winding up, redeem 100% of the outstanding Plum Class A Shares (other than Founder Shares) for a pro rata portion of the funds held in the Trust Account (including interest earned on the funds held in the Trust Account and not previously released to Plum to pay its taxes) which redemption will completely extinguish the rights of holders of Plum Class A Shares as shareholders (including the right to receive further liquidation distributions, if any), subject to applicable law, and, subject to the approval of its remaining shareholders and Plum’s board of directors and applicable law, dissolve and liquidate. In such event, the 7,062,500 Plum Class A Shares issued upon the division of the Founder Units and conversion of Plum Class B Shares were originally acquired by the Former Sponsor for $25,000 (or $0.004 per share), would be worthless because the Former Sponsor is not entitled to participate in any redemption or distribution with respect to such underlying shares. Sponsor purchased for approximately $1 from Former Sponsor 3,902,648 Plum Founder
96
Units which would be worthless because the Sponsor is not entitled to participate in any redemption or distribution with respect to such underlying shares. Further, the Former Sponsor purchased an aggregate of 865,000 Plum Private Placement Units in a private placement at a price of $10.00 per unit, for an aggregate purchase price of $8,650,000. The Plum Private Placement Units will become worthless if Plum does not consummate a business combination by July 30, 2025 or such earlier date as determined by Plum’s board of directors. On the other hand, if the Business Combination is consummated, each remaining outstanding Plum Share will be automatically converted into one TRC Ordinary Share subject to adjustment described herein. The managing member of the Sponsor is Kanishka Roy, the Chief Executive Officer and Chairman of Plum, and Mr. Roy has an indirect interest in the Plum Founder Units held by the Sponsor.
These financial interests may have influenced the decision of Plum’s directors and officers to approve the Business Combination and to continue to pursue the Business Combination. In considering the recommendations of Plum’s board of directors to vote for the Business Combination Proposal and other proposals, its shareholders should consider these interests. See the section of this proxy statement/prospectus entitled “The Business Combination Proposal — Interests of the Sponsor and Plum’s Directors and Officers in the Transactions.”
The Sponsor, an affiliate of current officers and directors of Plum, is liable to ensure that proceeds of the Trust Account are not reduced by vendor claims in the event the Business Combination is not consummated, which liability may have influenced Plum’s board of directors’ decision to pursue and approve the Business Combination and recommend that Plum’s shareholders approve the Business Combination and the other matters presented for approval at the extraordinary general meeting.
If the Business Combination or another business combination is not consummated by Plum by July 30, 2025 or such earlier date as determined by Plum’s board of directors or such later date as approved by Plum’s shareholders, the Sponsor, an affiliate of current officers and directors of Plum, will be liable to ensure that the proceeds in the Trust Account are not reduced by the claims of target businesses or claims of vendors or other entities that are owed money by Plum for services rendered or contracted for or for products sold to Plum, but only if such a vendor or target business has not executed a waiver agreement. If Plum consummates the Business Combination, on the other hand, TRC will be liable for all such claims.
These obligations of the Sponsor may have influenced Plum’s board of directors’ decision to pursue the Business Combination with TRC or Plum’s board of directors’ decision to approve the Business Combination. In considering the recommendations of Plum’s board of directors to vote for the Business Combination Proposal and other proposals, shareholders should consider these interests. See the section of this proxy statement/prospectus entitled “The Business Combination Proposal — Interests of the Sponsor and Plum’s Directors and Officers in the Transactions.”
Plum’s key personnel may negotiate employment or consulting agreements with PubCo in connection with the Business Combination. These agreements may provide for them to receive compensation following the Business Combination and as a result, may cause them to have conflicts of interest in determining whether the Business Combination is advantageous.
Plum’s key personnel may be able to remain with PubCo after the completion of the Business Combination only if they are able to negotiate employment or consulting agreements in connection with the Business Combination. Such negotiations may take place prior to the consummation of the Business Combination and could provide for such individuals to receive compensation in the form of cash payments and/or securities of PubCo for services they would render to PubCo after the completion of the Business Combination. The personal and financial interests of such individuals may influence their motivation in connection with the consummation of the Business Combination. However, Plum believes the ability of such individuals to remain with PubCo after the completion of the Business Combination will not be the determining factor in Plum’s decisions regarding the consummation of the Business Combination. There is no certainty, however, that any of Plum’s key personnel will remain with PubCo after the consummation of the Business Combination. Plum cannot assure you that any of its key personnel will remain in senior management or advisory positions with PubCo.
97
The Business Combination may be completed even though material adverse effects may result from the announcement of the Business Combination, industry-wide changes and other causes.
In general, either Plum or TRC may refuse to complete the Business Combination if there is a material adverse effect affecting the other party between the signing date of the Business Combination Agreement and the planned closing. However, certain types of changes do not permit either party to refuse to consummate the Business Combination, even if such change could be said to have a material adverse effect on TRC or Plum, including, but not limited to the following events (except, in certain cases where the change has a disproportionate effect on a party):
• any change or proposed change in any applicable Laws, GAAP or IFRS, or any change in interpretation thereof following the date of the Business Combination Agreement,
• any change in interest or exchange rates or economic, political, business or financial market conditions generally, including changes in the credit, debt, securities or capital markets or changes in prices of any security or market index or commodity or any disruption of such markets,
• the taking of any action required to be taken, or refraining from taking any action required not to be taken, under the Business Combination Agreement or any Ancillary Agreement,
• any act of God, natural disaster (including hurricanes, storms, tornados, flooding, earthquakes, wildfires, volcanic eruptions or similar occurrences), epidemic, pandemic, disease or other outbreak of illness or public health event, acts of nature or change in climate or any other force majeure event (including any escalation or worsening of any of the foregoing),
• any acts of terrorism or war (whether or not declared), sabotage, civil unrest, curfews, public disorder, riots, hostilities, geopolitical or local, regional, state, national or international political conditions or social conditions (including any escalation or worsening of any of the foregoing),
• any failure of TRC to meet any forecasts, guidance, estimates, milestones, budgets or financial or operating predictions of revenue, earnings, cash flow or cash position or any fluctuation in the stock price or trading volume of TRC Common Shares,
• any Events generally applicable to the industries or markets in which TRC operates,
• any matter existing as of the date of the Business Combination Agreement to the extent expressly set forth in TRC Disclosure Schedules,
• any action taken at the written request of an authorized officer of, or with the written approval or consent of, Plum,
• any Event that is cured by TRC prior to the Closing or
• any Event attributable to the announcement of the Business Combination Agreement or the pendency of the Transactions;
Furthermore, Plum or TRC may waive the occurrence of a material adverse effect affecting the other party. If a material adverse effect occurs and the parties still consummate the Business Combination, the market trading price of the TRC Ordinary Shares and TRC Warrants may suffer.
Delays in completing the Business Combination may substantially reduce the expected benefits of the Business Combination.
Satisfying the conditions to, and completion of, the Business Combination may take longer than, and could cost more than, Plum expects. Any delay in completing or any additional conditions imposed in order to complete the Business Combination may materially adversely affect the benefits that Plum expects to achieve from the Business Combination. If the Business Combination is not consummated by July 30, 2025, Plum will need to amend the Plum Articles to extend the business combination deadline.
The Sponsor, as well as Plum’s current and former officers and directors, have agreed to vote in favor of the Business Combination, regardless of how the holders of Plum Class A Shares vote.
The holders of Founder Shares have agreed to vote any Plum equity securities, including Plum Class A Shares and Plum Class B Shares, held by them in favor of the Business Combination. The holders of Founder Shares own and are entitled to vote an aggregate of approximately 87.4% of the outstanding Plum Shares. Unlike some other
98
blank check companies in which the initial shareholders agree to vote their Plum Shares in accordance with the majority of the votes cast by the holders of Plum Class A Shares in connection with an initial business combination, the holders of Founder Shares have agreed (and their permitted transferees of Plum Class B Shares and Plum Class A Shares issued upon the conversion of Plum Class B Shares will agree) to vote their Founder Shares and any Plum Class A Shares held by them in favor of our initial business combination. The Sponsor, directors and officers may from time to time purchase Plum Class A Shares prior to our initial business combination. The Plum Articles provide that, if we seek shareholder approval of an initial business combination, such initial business combination will be approved if we receive the affirmative vote of a majority of the shares voted at such meeting, including Founder Shares. The consummation of the Business Combination is not subject to the approval of a majority of unaffiliated Plum Public Shareholders. Since the Sponsor Parties own approximately 87.4% of the Plum Shares entitled to vote at the Plum Shareholders’ Meeting, the Sponsor Parties have sufficient votes to approve all of the Proposals without the vote of any of the Plum Public Shareholders.
The proposed Business Combination with TRC may be delayed or ultimately prohibited and Plum may not be able to complete the proposed Business Combination with TRC since such initial business combination may be subject to regulatory review and approval requirements, including pursuant to foreign investment regulations and review by governmental entities such as the Committee on Foreign Investment in the United States (“CFIUS”), or may be ultimately prohibited.
All but one of the current officers and directors of TRC are Canadian citizens and Canadian citizens represent a substantial portion of TRC’s significant stockholders. The Business Combination may be subject to regulatory review and approval requirements by governmental entities, which may cause the Business Combination to be delayed or ultimately prohibited. For example, CFIUS has authority to review direct or indirect foreign investments in U.S. companies. Among other things, CFIUS is empowered to require certain foreign investors to make mandatory filings, to charge filing fees related to such filings, and to self-initiate national security reviews of foreign direct and indirect investments in U.S. companies if the parties to that investment choose not to file voluntarily. If CFIUS determines that an investment threatens national security, CFIUS has the power to impose restrictions on the investment or recommend that the President prohibit and/or unwind it. Whether CFIUS has jurisdiction to review an acquisition or investment transaction depends on, among other factors, the nature and structure of the transaction, the nationality of the parties, the level of beneficial ownership interest and the nature of any information or governance rights involved. We note that (i) we are a Cayman Islands exempted company, (ii) TRC is an British Columbia business corporation and, following the Business Combination, PubCo will be a foreign private issuer, (iii) the Sponsor is a Delaware limited liability company whose managing member is controlled by a non-U.S. person and (iv) following the Business Combination, the Sponsor will be a significant PubCo shareholder. In our view, it is unlikely that the Business Combination would be subject to or impacted by a CFIUS review. We will proceed with the proposed Business Combination without submitting to CFIUS, and therefore risk CFIUS intervention, before or after closing the proposed Business Combination. CFIUS may decide to block or delay the proposed Business Combination, or impose conditions with respect to it, which may delay or prevent us from consummating the proposed Business Combination. The process of government review, whether by CFIUS or otherwise, could be lengthy. Because we have only a limited time to complete our initial business combination, our failure to obtain any required approvals within the requisite time period may require us to liquidate. In accordance with the Plum Articles, if an Initial Business Combination is not consummated by the Deadline Date, Plum will (a) cease all operations except for the purpose of winding up, (b) as promptly as reasonably possible but not more than ten business days thereafter, redeem the Plum Public Shares, at a per-share price, payable in cash, equal to the aggregate amount then on deposit in the Trust Account including interest earned on the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay taxes, if any, divided by the number of then-outstanding Plum Public Shares, which redemption will completely extinguish Plum Public Shareholders’ rights as Plum Public Shareholders (including the right to receive further liquidation distributions, if any), subject to applicable law, and (c) as promptly as reasonably possible following such redemption, subject to the approval of Plum’s remaining Plum Shareholders and the Plum Board, liquidate and dissolve, subject in the case of clause (b) and this clause (c), to Plum’s obligations under Cayman Islands law to provide for claims of creditors and in all cases subject to the other requirements of applicable law. In such event, Plum’s stockholders will miss the opportunity to benefit from the proposed Business Combination and the chance of realizing any future gains in the value of such investment. Additionally, there will be no redemption rights or liquidating distributions with respect to Plum’s warrants, which will expire worthless if Plum fails to complete an initial business combination by the required date. In the event of such distribution, it is possible that the per share value of the residual assets remaining available for distribution (including trust account assets) will be less than $10.00 per share.
99
Risks Related to Ownership of PubCo Securities Following the Business Combination
PubCo’s ability to be successful following the Business Combination will depend upon the efforts of the PubCo’s board of directors and key personnel and the loss of such persons could negatively impact the operations and profitability of PubCo’s business.
PubCo’s ability to be successful following the Business Combination will be dependent upon the efforts of the TRC’s board of directors and key personnel. We cannot assure you that PubCo’s board of directors and key personnel will be effective or successful or remain with PubCo. In addition to the other challenges they will face, such individuals may be unfamiliar with the requirements of operating a public company, which could cause PubCo’s management to have to expend time and resources helping them become familiar with such requirements.
It is estimated that, pursuant to the Business Combination Agreement, Plum’s public shareholders will own approximately 2.3% of the equity interests of PubCo (assuming no redemptions and excluding shares available for future issuance pursuant to the proposed equity incentive plan) and Plum’s management will not be engaged in the management of PubCo’s business. Accordingly, the future performance of PubCo will depend upon the quality of PubCo’s board of directors, management and key personnel of PubCo.
PubCo will have broad discretion in the use of the net proceeds post-Closing and may not use them effectively.
PubCo cannot specify with any certainty the particular uses of the net proceeds that PubCo will receive pursuant to the Business Combination with Plum. PubCo’s management will have broad discretion in the application of the net proceeds, including working capital, possible acquisitions, and other general corporate purposes, and PubCo may spend or invest these proceeds in a way with which PubCo’s shareholders disagree. The failure by PubCo’s management to apply these funds effectively could harm PubCo’s business and financial condition. Pending their use, PubCo may invest the net proceeds from the offering in a manner that does not produce income or that loses value.
PubCo’s management has limited experience in operating a public company.
PubCo’s executive officers have no experience in the management of a company that is publicly traded in the United States and subject to the rules of the U.S. Securities and Exchange Commission. PubCo’s management team may not successfully or effectively manage its transition to a public company that will be subject to significant regulatory oversight and reporting obligations under federal securities laws. Their limited experience in dealing with the increasingly complex laws pertaining to public companies could be a significant disadvantage in that it is likely that an increasing amount of their time may be devoted to these activities which will result in less time being devoted to the management and growth of PubCo. PubCo may not have adequate personnel with the appropriate level of knowledge, experience, and training in the accounting policies, practices or internal control over financial reporting required of public companies in the United States. The development and implementation of the standards and controls necessary for PubCo to achieve the level of accounting standards required of a public company in the United States may require costs greater than expected. It is possible that PubCo will be required to expand its employee base and hire additional employees to support its operations as a public company, which will increase its operating costs in future periods.
PubCo’s disclosure controls and procedures may not prevent or detect all errors or acts of fraud.
Following the Business Combination, PubCo will be subject to certain reporting requirements of the Exchange Act. PubCo’s disclosure controls and procedures will be designed to reasonably assure that information required to be disclosed in reports to file or submit under the Exchange Act is accumulated and communicated to management, recorded, processed, summarized and reported within the time periods specified in the rules and forms of the SEC. PubCo believes that any disclosure controls and procedures or internal controls and procedures, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. These inherent limitations include the realities that judgments in decision-making can be faulty, and that breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people or by an unauthorized override of the controls. Accordingly, because of the inherent limitations in the control system, misstatements, or insufficient disclosures due to error or fraud may occur and not be detected.
100
Following the consummation of the Business Combination, PubCo may incur significant increased expenses and administrative burdens as a listed public company, which could have an adverse effect on its business, financial condition and results of operations.
Following the consummation of the Business Combination, PubCo will face increased legal, accounting, administrative and other costs and expenses as a U.S.-listed public company. The Sarbanes-Oxley Act, including the requirements of Section 404, as well as rules and regulations subsequently implemented by the SEC, the Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 and the rules and regulations promulgated, and to be promulgated, thereunder by the Public Company Accounting Oversight Board (the “PCAOB”) and the securities exchanges, impose additional reporting and other obligations on public companies. Compliance with public company requirements will increase costs and make certain activities more time-consuming. A number of those requirements will require PubCo to carry out activities PubCo has not done previously. For example, PubCo will create new board committees and adopt new internal controls and disclosure controls and procedures. In addition, expenses associated with SEC reporting requirements will be incurred. Furthermore, if any issues in complying with those requirements are identified, PubCo could incur additional costs rectifying those issues, and the existence of those issues could adversely affect PubCo’s reputation or investor perceptions of it. It may also be more expensive to obtain director and officer liability insurance. Risks associated with PubCo’s status as a U.S.-listed public company may make it more difficult to attract and retain qualified persons to serve on PubCo’s board of directors or as executive officers. The additional reporting and other obligations imposed by these rules and regulations will increase legal and financial compliance costs and the costs of related legal, accounting and administrative activities. These increased costs will require PubCo to divert a significant amount of money that could otherwise be used to expand the business and achieve strategic objectives. Advocacy efforts by shareholders and third parties may also prompt additional changes in governance and reporting requirements, which could further increase costs.
TRC’s internal controls over financial reporting currently do not meet all of the standards contemplated by Section 404 of the Sarbanes-Oxley Act, and the failure of PubCo to achieve and maintain effective internal controls over financial reporting in accordance with Section 404 of the Sarbanes-Oxley Act of 2002 could have a material adverse effect on its business and the market price of PubCo Common Shares.
As a public company, PubCo will have significant requirements for enhanced financial reporting and internal controls. If PubCo is unable to establish or maintain appropriate internal financial reporting controls and procedures, it could cause PubCo to fail to meet its reporting obligations on a timely basis, result in material misstatements in PubCo’s consolidated financial statements and harm PubCo’s operating results. TRC’s internal controls over financial reporting currently do not meet all of the standards contemplated by Section 404 of the Sarbanes-Oxley Act that eventually PubCo will be required to meet. Because currently TRC does not have comprehensive documentation of its internal controls and has not yet tested its internal controls in accordance with Section 404, TRC cannot conclude in accordance with Section 404 that it does not have a material weakness in its internal controls or a combination of significant deficiencies that could result in the conclusion that it has a material weakness in our internal controls.
Matters impacting our internal controls may cause PubCo to be unable to report financial information on a timely basis and thereby subject PubCo to adverse regulatory consequences, including sanctions by the SEC or violations of applicable stock exchange listing rules, which may result in a breach of the covenants under existing or future financing arrangements. There also could be a negative reaction in the financial markets due to a loss of investor confidence in us and the reliability of our financial statements. Confidence in the reliability of our financial statements also could suffer if we or our independent registered public accounting firm were to report a material weakness in our internal controls over financial reporting. In addition, we may be required to incur costs in improving our internal control system and the hiring of additional personnel. Any such action could materially adversely affect us and lead to a decline in the market price of our Ordinary Shares.
As an “emerging growth company,” we cannot be certain if the reduced disclosure requirements applicable to “emerging growth companies” will make the PubCo Shares less attractive to investors.
As an “emerging growth company,” PubCo will be entitled to take advantage of certain exemptions from various reporting requirements that are applicable to other public companies that are not “emerging growth companies,” including not being required to obtain an assessment of the effectiveness of its internal control over financial reporting from its independent registered public accounting firm pursuant to Section 404 of the
101
Sarbanes-Oxley Act, reduced disclosure obligations regarding executive compensation in its periodic reports and proxy statements, and exemptions from the requirements of holding a non-binding advisory vote on executive compensation and shareholder approval of any golden parachute payments not previously approved. In addition, the JOBS Act provides that an emerging growth company can take advantage of an extended transition period for complying with new or revised accounting standards, which we have elected to do.
We cannot predict if investors will find the PubCo Common Shares less attractive because it will rely on these exemptions. If some investors find the PubCo Common Shares less attractive as a result, there may be a less active market for the PubCo Common Shares, the share price of PubCo Common Shares may be more volatile and the price at which our securities trade could be less than if we did not use these exemptions.
As a foreign private issuer, PubCo will be exempt from a number of rules under the U.S. securities laws and will be permitted to file less information with the SEC than U.S. public companies.
Because PubCo qualifies as a foreign private issuer under the Exchange Act, it will be exempt from certain provisions of the securities rules and regulations in the United States that are applicable to U.S. domestic issuers, including:
• the rules under the Exchange Act requiring the filing with the SEC of quarterly reports on Form 10-Q or current reports on Form 8-K;
• the sections of the Exchange Act regulating the solicitation of proxies, consents, or authorizations in respect of a security registered under the Exchange Act;
• the sections of the Exchange Act requiring insiders to file public reports of their stock ownership and trading activities and liability for insiders who profit from trades made in a short period of time; and
• the selective disclosure rules by issuers of material nonpublic information under Regulation FD.
PubCo will be required to file an annual report on Form 20-F within four months of the end of each fiscal year. Press releases relating to financial results and material events will also be furnished to the SEC on Form 6-K. However, the information PubCo is required to file with or furnish to the SEC will be less extensive and less timely compared to that required to be filed with the SEC by U.S. domestic issuers. As a result, you may not be afforded the same protections or information that would be made available to you were you investing in a U.S. domestic issuer.
While it is a foreign private issuer, PubCo may opt out of certain Nasdaq corporate governance rules applicable to public companies organized in the U.S.
We are entitled to rely on a provision in Nasdaq corporate governance rules that allows PubCo to follow Canadian corporate law with regard to certain aspects of corporate governance. This allows PubCo to follow certain corporate governance practices that differ in significant respects from the corporate governance requirements applicable to domestic issuers listed on Nasdaq, which may provide less protection to PubCo’s shareholders than what is accorded to investors under the Nasdaq rules applicable to domestic issuers.
Rather than being required to follow all of the corporate governance requirements that apply to domestic companies, a foreign private issuer may follow the corporate governance practice in its home country, except that it must:
• Disclose publicly each requirement that it does not follow and describe the home country practice that it does follow.
• Refrain from a disparate reduction or restriction of voting rights of common shareholders, subject to certain exceptions if not prohibited by home country law.
• Provide a prompt notification if an executive officer of the company becomes aware of any noncompliance by the company of Nasdaq rules.
• Have an audit committee that meets certain requirements, as discussed below.
102
PubCo may lose its foreign private issuer status, which would then require it to comply with the Exchange Act’s domestic reporting regime and cause it to incur significant legal, accounting and other expenses.
PubCo will be required to test its foreign private issuer status at the end of its second fiscal quarter in each fiscal year after the consummation of the Business Combination. If PubCo were no longer a foreign private issuer, it would be required to comply with all of the periodic disclosure and current reporting requirements of the Exchange Act applicable to U.S. domestic issuers beginning on the first day of its next fiscal year. In order to maintain PubCo’s status as a foreign private issuer, either (a) a majority of its securities must be either directly or indirectly owned of record by nonresidents of the U.S. or (b)(i) a majority of its executive officers or directors cannot be U.S. citizens or residents, (ii) more than 50% of its assets must be located outside the U.S. and (iii) its business must be administered principally outside the U.S. If PubCo loses its status as a foreign private issuer, it would be required to comply with the Exchange Act reporting and other requirements applicable to U.S. domestic issuers, which are more detailed and extensive than the requirements for foreign private issuers. PubCo may also be required to make changes in its corporate governance practices in accordance with various SEC and Nasdaq rules. The regulatory and compliance costs to PubCo under U.S. securities laws if it is required to comply with the reporting requirements applicable to a U.S. domestic issuer may be significantly higher than the cost it would incur as a foreign private issuer. As a result, we expect that a loss of foreign private issuer status for PubCo would increase its legal and financial compliance costs and is likely to make some activities highly time-consuming and costly. We also expect that if PubCo were required to comply with the rules and regulations applicable to U.S. domestic issuers, it would make it more difficult and expensive for it to obtain director and officer liability insurance, and PubCo may be required to accept reduced coverage or incur substantially higher costs to obtain coverage. These rules and regulations could also make it more difficult for PubCo to attract and retain qualified members of its board of directors.
The future exercise of registration rights may adversely affect the market price of PubCo Common Shares.
In connection with the Business Combination, PubCo will enter into a registration rights agreement that will obligate PubCo to register PubCo Common Shares held by the Sponsor and certain other holders of PubCo Common Shares. Specifically, within 15 days after the Closing, PubCo is required to file a registration statement to register the resale of (i) 7,062,500 PubCo Common Shares that will be issued to the Sponsor Parties in exchange for their Plum Shares and (ii) 2,642,500 PubCo Common Shares issuable upon the exercise of TRC Warrants to the extent such securities are “restricted securities” (as defined in Rule 144) or are otherwise held by an affiliate (as defined in Rule 144) of PubCo. Subject to certain requirements and limitations, the holders may demand that PubCo consummate an underwritten offering of the demanding holder’s or holders’ PubCo Common Shares. In addition, the holders will have certain “piggy-back” registration rights with respect to registration statements filed subsequent to the completion of the Business Combination and rights to require PubCo to register for resale such securities pursuant to Rule 415 under the Securities Act. Sales of a substantial amount of ordinary shares pursuant to a resale registration statement in the public market could occur at any time the registration statement remains effective. These sales, or the perception in the market that the holders of a large number of ordinary shares intend to sell such shares, could reduce the market price of the PubCo Common Shares.
There may be sales of a substantial amount of PubCo Common Shares after the Business Combination by Plum Shareholders, and these sales could cause the price of PubCo Common Shares to fall.
After the Business Combination, on a pro forma basis, there will be approximately 44,341,739 outstanding PubCo Common Shares (assuming no redemptions by Plum Shareholders). Of Plum’s issued and outstanding shares that were issued prior to the Business Combination, all will be freely transferable, except for any shares held by Plum’s “affiliates,” as that term is defined in Rule 144 under the Securities Act. Following completion of the Business Combination, approximately 18.2% of the PubCo Common Shares will be held by the Sponsor Parties. This percentage does not take into account (i) the issuance of up to 8,229,736 shares (or options to acquire shares) under the Equity Incentive Plan, (ii) the issuance of any shares upon the exercise of Plum Warrants to purchase up to a total of 12,059,166 PubCo Common Shares, (iii) the issuance of any shares upon the exercise of TRC Options to purchase up to a total of 2,085,673 PubCo Common Shares, (iv) the issuance of any shares upon the exercise of TRC Warrants to purchase up to a total of 6,406,368 PubCo Common Shares, or (v) the issuance of up to a total of 3,104,561 PubCo Common Shares pursuant to TRC RSUs, (vi) the issuance of any shares upon the conversion of TRC Convertible Debt acquire up to a total of 3,918,801 PubCo Common Shares, in each case that will remain outstanding following the Business Combination. Future sales of PubCo Common Shares may cause the market price of PubCo’s securities to drop significantly, even if its business is performing well. Additionally,
103
sales of substantial amounts of PubCo Common Shares in the public market after the Business Combination, or the perception that such sales will occur, could adversely affect the market price of PubCo Common Shares and make it difficult for it to raise funds through securities offerings in the future.
PubCo may amend the terms of the warrants in a manner that may be adverse to holders of Plum Warrants with the approval by the holders of at least 50% of the then outstanding Plum Warrants.
The warrants were issued in registered form under the warrant agreement. The warrant agreement provides that (a) the terms of the warrants may be amended without the consent of any holder for the purpose of (i) curing any ambiguity or correcting any mistake, including to conform the provisions of the warrant agreement to the description of the terms of the warrants and the warrant agreement set forth in the prospectus for the IPO, or defective provision or (ii) adding or changing any provisions with respect to matters or questions arising under the warrant agreement as the parties to the warrant agreement may deem necessary or desirable and that the parties deem to not adversely affect the rights of the registered holders of the warrants, provided that the approval by the holders of at least 50% of the then-outstanding Plum Warrants is required to make any change that adversely affects the interests of the registered holders of Plum Warrants. PubCo’s ability to amend the terms of the Plum Warrants with the consent of at least 50% of the then outstanding Plum Warrants is broad. Examples of such amendments could be amendments to, among other things, increase the exercise price of the warrants, shorten the exercise period or decrease the number of PubCo Common Shares purchasable upon exercise of a warrant.
PubCo may redeem your unexpired warrants prior to their exercise at a time that is disadvantageous to you, thereby making your warrants worthless.
PubCo will have the ability to redeem outstanding warrants at any time after they become exercisable and prior to their expiration, at a price of $0.01 per warrant, provided that the last reported sales price of PubCo Common Shares equals or exceeds $18.00 per share (as adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like) for any twenty (20) trading days within a thirty (30) trading-day period commencing once the warrants become exercisable and ending on the third trading day prior to the date on which PubCo gives proper notice of such redemption and provided certain other conditions are met. If and when the warrants become redeemable by PubCo, it may exercise its redemption right even if it is unable to register or qualify the underlying securities for sale under all applicable state securities laws. As a result, PubCo may redeem the warrants as set forth above even if the holders are otherwise unable to exercise the warrants. Redemption of the outstanding warrants could force you (i) to exercise your warrants and pay the exercise price therefor at a time when it may be disadvantageous for you to do so, (ii) to sell your warrants at the then-current market price when you might otherwise wish to hold your warrants or (iii) to accept the nominal redemption price which, at the time the outstanding warrants are called for redemption, is likely to be substantially less than the market value of your warrants.
In addition, PubCo may redeem outstanding warrants at any time after they become exercisable and prior to their expiration, at a price of $0.10 per warrant if, among other things, the price per PubCo Common Share equals or exceeds $10.00 per share (as adjusted for adjustments to the number of shares issuable upon exercise or the exercise price of a warrant as described below under “Description of TRC Securities — Warrants — The Public Warrants — Redemption of warrants when the price per TRC Ordinary Shares equals or exceeds $10.00”). The value received upon exercise of the warrants (i) may be less than the value the holders would have received if they had exercised their warrants at a later time where the underlying share price is higher and (ii) may not compensate the holders for the value of the warrants, including because the number of shares received will be capped at 0.361 PubCo Common Shares per warrant (subject to adjustment) irrespective of the remaining life of the warrants. PubCo will have no obligation to notify holders of the warrants that they have become eligible for redemption. However, pursuant to the warrant agreement, in the event PubCo decides to redeem the warrants, it will be required to mail notice of such redemption to the registered warrant holders not less than 30 days prior to the redemption date.
PubCo’s warrant agreement will designate the courts of the State of New York or the United States District Court for the Southern District of New York as the sole and exclusive forum for certain types of actions and proceedings that may be initiated by holders of its warrants, which could limit the ability of warrant holders to obtain a favorable judicial forum for disputes with PubCo.
PubCo’s warrant agreement will provide that, subject to applicable law, (i) any action, proceeding or claim against us arising out of or relating in any way to the warrant agreement, including under the Securities Act, will be brought and enforced in the courts of the State of New York or the United States District Court for the Southern
104
District of New York, and (ii) that PubCo irrevocably submits to such jurisdiction, which jurisdiction shall be the exclusive forum for any such action, proceeding or claim. PubCo will waive any objection to such exclusive jurisdiction and that such courts represent an inconvenient forum.
Notwithstanding the foregoing, these provisions of the warrant agreement will not apply to suits brought to enforce any liability or duty created by the Exchange Act or any other claim for which the federal district courts of the United States of America are the sole and exclusive forum. Any person or entity purchasing or otherwise acquiring any interest in any of PubCo’s warrants shall be deemed to have notice of and to have consented to the forum provisions in its warrant agreement. If any action, the subject matter of which is within the scope of the forum provisions of the warrant agreement, is filed in a court other than a court of the State of New York or the United States District Court for the Southern District of New York (a “foreign action”) in the name of any holder of PubCo’s warrants, such holder shall be deemed to have consented to: (x) the personal jurisdiction of the state and federal courts located in the State of New York in connection with any action brought in any such court to enforce the forum provisions (an “enforcement action”), and (y) having service of process made upon such warrant holder in any such enforcement action by service upon such warrant holder’s counsel in the foreign action as agent for such warrant holder.
This choice-of-forum provision may limit a warrant holder’s ability to bring a claim in a judicial forum that it finds favorable for disputes with PubCo, which may discourage such lawsuits. Alternatively, if a court were to find this provision of PubCo’s warrant agreement inapplicable or unenforceable with respect to one or more of the specified types of actions or proceedings, PubCo may incur additional costs associated with resolving such matters in other jurisdictions, which could materially and adversely affect its business, financial condition and results of operations and result in a diversion of the time and resources of its team and board of directors.
PubCo may not pay dividends and, as a result, your ability to achieve a return on your investment will depend on appreciation in the price of PubCo Common Shares.
PubCo may retain any future earnings to finance the growth and development of the business and, therefore, may not pay any cash dividends on PubCo Common Shares in the medium term. Any determination to pay dividends in the future will be at the discretion of PubCo’s board of directors and will be dependent upon its future financial condition, results of operations and capital requirements, general business conditions and other relevant factors. Accordingly, investors must rely on sales of their PubCo Common Shares after price appreciation, which may never occur, as the only way to realize any future gains on their investments.
There has been no prior market for PubCo’s Common Shares and an active trading market for such securities may never develop or be sustained, which may cause its shares to trade at a discount and make it difficult to sell the shares.
Prior to the Business Combination, there has not been a public trading market for PubCo Common Shares. We cannot predict the extent to which investor interest in PubCo will lead to the development of an active trading market or how liquid that market might become. An active public market for PubCo Common Shares may not develop or be sustained after the Business Combination, which would make it difficult for you to sell your PubCo Common Shares at a price that is attractive to you, or at all. The market price of PubCo Common Shares may decline below the current price.
Risks Relating to Redemption
If holders of Plum Class A Shares fail to properly demand redemption rights, they will not be entitled to convert their Plum Class A Shares into a pro rata portion of the funds held in the Trust Account.
Plum shareholders holding Plum Class A Shares (other than Founder Shares) may demand that Plum redeem their Plum Class A Shares into a pro rata portion of the funds held in the Trust Account, calculated as of two (2) business days prior to the consummation of the transactions contemplated by the Business Combination Proposal (including interest earned on the funds held in the Trust Account and not previously released to Plum to pay its taxes). To demand redemption rights, Plum Shareholders must deliver their shares to Plum’s transfer agent no later than two (2) business days prior to the extraordinary general meeting. Any Plum Shareholder who fails to properly demand redemption rights by delivering his, her or its shares will not be entitled to convert his, her or its shares into
105
a pro rata portion of the funds held in the Trust Account. See the section of this proxy statement/prospectus entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” for the procedures to be followed if you wish to exercise your redemption rights.
If you or a “group” of shareholders of which you are a part are deemed to hold an aggregate of more than 15% of the Plum Class A Shares you (or, if a member of such a group, all of the members of such group in the aggregate) will lose the ability to redeem all such shares in excess of 15% of the Plum Class A Shares.
A Plum Class A Shareholder, together with any of his, her or its affiliates or any other person with whom it is acting in concert or as a “group” (as defined in Section 13(d)(3) of the Exchange Act), will be restricted from redeeming in the aggregate his, her or its Plum Class A Shares or, if part of such a group, the group’s Plum Class A Shares, in excess of 15% of the Plum Class A Shares. Your inability to redeem any such excess Plum Class A Shares could resulting in you suffering a material loss on your investment in Plum if you sell such excess public shares in open market transactions. Plum cannot assure you that the value of such excess public shares will appreciate over time following the Business Combination or that the market price of the public shares will exceed the per-share redemption price.
However, Plum’s shareholders’ ability to vote all of their public shares (including such excess shares) for or against the Business Combination Proposal is not restricted by this limitation on redemption.
If a Plum Shareholder fails to receive notice of Plum’s offer to redeem Plum Class A Shares in connection with the Business Combination, or fails to comply with the procedures for tendering its shares, such Plum Class A Shares may not be redeemed.
If, despite Plum’s compliance with the proxy rules, a Plum Class A Shareholder fails to receive Plum proxy materials, such shareholder may not become aware of the opportunity to redeem its Plum Class A Shares. In addition, the proxy materials that Plum is furnishing to holders of public Plum Class A Shares in connection with the Business Combination describe the various procedures that must be complied with in order to validly redeem public Plum Common Shares. In the event that a Plum Class A Shareholder fails to comply with these procedures, its Plum Class A Shares may not be redeemed.
Plum Shareholders can exercise redemption rights with respect to a large number of Plum Class A Shares, which may impair Plum’s ability to complete the Business Combination or optimize PubCo’s capital structure.
If a larger number of Plum Class A Shares are submitted for redemption than Plum currently expects, Plum may need to seek to restructure the transaction to reserve a greater portion of the cash in the Trust Account. If Plum is required to seek additional capital, it may need to borrow funds from the Sponsor, management team (such a loan, a “Working Capital Loan”) or arrange for third-party financing including, but not limited to, dilutive equity issuances or the incurrence of indebtedness at higher than desirable levels. Neither the Sponsor, members of Plum’s management team nor any of their affiliates is under any obligation to advance funds to Plum in such circumstances. Any such advances would be repaid only from funds held outside the Trust Account or from funds released to Plum upon completion of Plum’s initial business combination. The Sponsor has loaned Plum an aggregate of $250,000 under a promissory note as of January 3, 2024, which is due on the earlier of the consummation of Plum’s initial business combination or Plum’s liquidation. Third-party financing may not be available on favorable terms to Plum or at all. Prior to the completion of the Business Combination, Plum does not expect to seek loans from parties other than the Sponsor or an affiliate of the Sponsor, as Plum does not believe third parties will be willing to loan such funds and provide a waiver against any and all rights to seek access to funds in the Trust Account.
If the Business Combination is unsuccessful and you did not submit your shares for redemption you would not receive your pro rata portion of the Trust Account until Plum liquidates the Trust Account or consummates an alternative initial business combination or upon the occurrence of an extension of the business combination deadline or certain other corporation actions as set forth in the Plum Articles. If you are in need of immediate liquidity, you could attempt to sell your stock in the open market; however, at such time the Plum Class A Shares may trade at a discount to the pro rata amount per share in the Trust Account or there may be limited market demand at such time. In either situation, you may suffer a material loss on your investment or lose the benefit of funds expected in connection with Plum’s redemption until Plum liquidates, consummates
106
an alternative initial business combination, effectuates an extension of the Business Combination Deadline or takes certain other actions set forth in the Plum Articles or you are able to sell your Plum Class A Shares in the open market.
The ability of holders of Plum Class A Shares to exercise redemption rights with respect to a large number of Plum Class A Shares could increase the probability that the Business Combination would be unsuccessful and that you would have to wait for liquidation in order to redeem Plum Class A Shares.
If the Business Combination is not consummated, you would not receive your pro rata portion of the funds held in the Trust Account until the Trust Account is liquidated. If you are in need of immediate liquidity, you could attempt to sell your Plum Class A Shares in the open market; however, at the time you attempt to sell your Plum Class A Shares, Plum Class A Shares may trade at a discount to the pro rata amount per share in the Trust Account. In either situation, you may suffer a material loss on your investment or lose the benefit of funds expected in connection with Plum’s redemption until Plum liquidates or you are able to sell your Plum Class A Shares in the open market.
We cannot be certain as to the number of Plum Class A Shares that will be redeemed and as to the potential impact to holders of Plum Class A Shares who do elect to redeem their Plum Class A Shares. There is no guarantee that the decision of a holder of Plum Class A Shares to redeem its Plum Class A Shares for a pro rata portion of the funds held in the Trust Account will put the shareholder in a better future economic position.
There is no assurance as to the price at which a holder of Plum Class A Shares may be able to sell its PubCo Common Shares received in connection with the Business Combination or shares with respect to any alternative business combination. Certain events following the consummation of any initial business combination, including the Business Combination, may cause an increase in the share price, and may result in a lower value realized now than a holder of PubCo Common Shares might realize in the future had the shareholder not redeemed his, her or its Plum Class A Shares. Similarly, if a holder of Plum Class A Shares does not redeem its Plum Class A Shares, such shareholder will bear the risk of ownership of the PubCo Common Shares after the consummation of the Business Combination or shares with respect to any alternative business combination, and there can be no assurance that a shareholder can sell its shares in the future for a greater amount than the redemption price set forth in this proxy statement/prospectus. A Plum Shareholder should consult such shareholder’s tax and/or financial advisor for assistance on how this may affect his, her or its individual situation. On [•], 2025, the most recent practicable date prior to the date of this proxy statement/prospectus, the closing price per Plum Class A Share quoted on OTC Pink was $ [•]. Holders of Plum Class A Shares should be aware that, while we are unable to predict the price per PubCo Common Share following the consummation of the Business Combination — and accordingly we are unable to predict the potential impact of redemptions on the per share value of Plum Class A Shares owned by non-redeeming holders of Plum Class A Shares — increased levels of redemptions by holders of Plum Class A Shares may be a result of the price per Plum Class A Share falling below the redemption price. We expect that more holders of Plum Class A Shares may elect to redeem their Plum Class A Shares if the share price of the Plum Class A Shares is below the projected redemption price of $ [•] per share, and we expect that more holders of Plum Class A Shares may elect not to redeem their Plum Class A Shares if the share price of the Plum Class A Shares are above the projected redemption price of $ [•] per share. Each Plum Class A Share that is redeemed will represent both (i) a reduction, equal to the amount of the redemption price, of the cash that will be available to PubCo from the Trust Account and (ii) a corresponding increase in each holder of Plum Class A Shares pro rata ownership interest in PubCo following the consummation of the Business Combination. Based on an estimated per share redemption price of approximately $ [•] per share that was calculated based on $ [•] in the Trust Account, a hypothetical 1% increase or decrease in the number of Plum Class A Shares would result in a decrease or increase, respectively, of $ [•] of cash available in the Trust Account. In addition, if a holder of Plum Class A Shares does not redeem its shares, but if other holders of Plum Class A Shares do elect to redeem their shares, the non-redeeming holders of Plum Class A Shares would own shares with a lower book value per value, which would increase from $ [•] per share (assuming no redemptions) to $ [•] per share (assuming maximum redemption scenario) on a pro forma basis as of the date of this proxy statement/prospectus. In addition, the net loss per share for non-redeeming holders of Plum Class A Shares would remain the same at $ [•] per share (assuming either no redemptions or maximum redemptions) on a pro forma basis as of the date of this proxy statement/prospectus.
107
CAUTIONARY NOTE REGARDING FORWARD-LOOKING STATEMENTS
Some of the statements contained in this proxy statement/prospectus may constitute “forward-looking statements” within the meaning of the federal securities laws. Forward-looking statements relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends and similar expressions concerning matters that are not historical facts. Forward-looking statements reflect Plum’s, TRC’s or PubCo’s current views, as applicable, with respect to, among other things, their respective capital resources, performance and results of operations. Likewise, all of PubCo’s and TRC’s statements regarding anticipated growth in operations, anticipated market conditions, demographics and results of operations are forward-looking statements. In some cases, you can identify these forward-looking statements by the use of terminology such as “outlook,” “believes,” “expects,” “potential,” “continues,” “may,” “will,” “should,” “could,” “seeks,” “approximately,” “predicts,” “intends,” “plans,” “estimates,” “anticipates” or the negative version of these words or other comparable words or phrases, but the absence of these words does not mean that a statement is not forward-looking.
The forward-looking statements contained in this proxy statement/prospectus reflect Plum’s, TRC’s or PubCo’s current views, as applicable, about future events and are subject to numerous known and unknown risks, uncertainties, assumptions and changes in circumstances that may cause actual results to differ significantly from those expressed in any forward-looking statement. None of Plum, TRC or PubCo guarantees that the transactions and events described will happen as described (or that they will happen at all). The following factors, among others, could cause actual results and future events to differ materially from those set forth or contemplated in the forward-looking statements:
• TRC’s estimates of the funding it needs to meet operational needs and to more fully evaluate the tailings at the Peak REE Project;
• the ability of TRC to finance its projected operating deficits;
• the ability of TRC to profitably extract REEs from the tailings at the Peak REE Project;
• the continued existence of the Project Lease and the extension of the termination date thereof;
• possible delays in closing the Business Combination, whether due to the inability to obtain Plum Shareholder Approval, or failure to satisfy any of the conditions to closing the Business Combination, as set forth in the Business Combination Agreement;
• the inability of the Business Combination, or an alternate business combination, to be completed by the Deadline Date, and the potential failure of Plum to obtain an extension of the Deadline Date if sought by Plum;
• any waivers of the conditions to Closing as may be permitted in the Business Combination Agreement;
• general economic uncertainty;
• PubCo’s ability to obtain and maintain financing arrangements on attractive terms;
• PubCo’s ability to obtain or maintain the listing of PubCo’s Common Shares or PubCo Warrants on the NASDAQ or any other national exchange following the Business Combination;
• the impact of and changes in governmental regulations or the enforcement thereof, tax laws and rates, accounting guidance and similar matters in regions in which PubCo operates or will operate in the future;
• potential litigation, governmental or regulatory proceedings, investigations or inquiries involving PubCo, TRC or Plum, including in relation to the Business Combination;
• international, national or local economic, social or political conditions that could adversely affect the companies and their business;
• the effectiveness of PubCo’s internal controls and its corporate policies and procedures;
• changes in personnel and availability of qualified personnel;
108
• environmental uncertainties and risks related to adverse weather conditions and natural disasters;
• the volatility of the market price and liquidity of Plum Units, Plum Public Shares and Plum Public Warrants;
• potential write-downs, write-offs, restructuring and impairment or other charges required to be taken by PubCo subsequent to the Business Combination;
• the possibility that the Plum Board’s valuation of TRC was inaccurate, including the failure of Plum’s diligence review to identify all material risks associated with the Business Combination;
• the limited experience of certain members of PubCo’s management team in operating a public company in the United States; and
• the volatility of the market price and liquidity of PubCo Common Shares and PubCo Warrants.
Forward-looking statements regarding expected ownership of PubCo Common Shares by existing Plum Shareholders and TRC Shareholders following the Business Combination have been calculated based on each of Plum’s and TRC’s outstanding share capital, each as of the date of this proxy statement/prospectus. Forward-looking statements representing post-closing expectations are inherently uncertain. Estimates such as expected revenue, production, operating expenses, EBITDA, general and administrative expenses, capital expenditures, free cash flow, net debt, reserves and other measures are preliminary in nature. There can be no assurance that the forward-looking statements will prove to be accurate and reliance should not be placed on these estimates in deciding how to vote on the Proposals.
The forward-looking statements contained herein are subject to risks, uncertainties and other factors, which could cause actual results to differ materially from future results expressed, projected or implied by the forward-looking statements. For a further discussion of the risks and other factors that could cause Plum’s, TRC’s or PubCo’s future results, performance or transactions to differ significantly from those expressed in any forward-looking statements, please see the section entitled “Risk Factors.” There may be additional risks that Plum, TRC and/or PubCo do not presently know or that Plum, TRC and/or PubCo currently believes are immaterial, that could also cause actual results to differ from those contained in the forward-looking statements. Should one or more of these risks or uncertainties materialize, or should any of the assumptions made in making these forward-looking statements prove incorrect, actual results may vary in material respects from those projected in these forward-looking statements. While such forward-looking statements reflect Plum’s, TRC’s and PubCo’s good faith beliefs, as applicable, they are not guarantees of future performance. Plum, TRC and PubCo disclaim any obligation to publicly update or revise any forward-looking statement to reflect changes in underlying assumptions or factors, new information, data or methods, future events or other changes after the date of this proxy statement/prospectus, except as required by applicable law. You should not place undue reliance on any forward-looking statements, which are based only on information currently available to Plum, TRC and PubCo, as applicable.
109
EXTRAORDINARY GENERAL MEETING OF Plum SHAREHOLDERS
Overview
Plum is furnishing this proxy statement/prospectus to its shareholders as part of the solicitation of proxies by the Plum Board for use at the Plum Shareholders’ Meeting to be held on [•], 2025, and at any adjournment or postponement thereof. This proxy statement/prospectus is first being furnished to Plum Shareholders on or about [•], 2025 in connection with the vote on the proposals described in this proxy statement/prospectus. This proxy statement/prospectus provides Plum Shareholders with information they need to know to be able to vote or instruct their vote to be cast at the Plum Shareholders’ Meeting.
Date, Time and Place
The Plum Shareholders’ Meeting will be held both in person on [•], 2025 at 10:00 a.m., Eastern Time, virtually at https://www [•], using technology designed to increase shareholder access, save Plum and Plum Shareholders time and money and provide Plum Shareholders’ rights and opportunities to participate in the Plum Shareholders’ Meeting similar to those they would have had had they attended in person. Plum will provide Plum Shareholders with an opportunity to hear all portions of the Plum Shareholders’ Meeting as conducted by the Plum Board, submit written questions and comments during the Plum Shareholders’ Meeting and vote online during the open poll portion of the Plum Shareholders’ Meeting.
Attending the Plum Shareholders’ Meeting
All Plum Shareholders as of the record date, or their duly appointed proxies, may attend the Plum Shareholders’ Meeting either in person or via the live webcast. If you were a Plum Shareholder as of the close of business on [•], 2025, you may attend the Plum Shareholders’ Meeting. Plum Shareholders do not need to attend the Plum Shareholders’ Meeting to vote their shares. For information on how to vote your Plum Common Shares, please see the subsection entitled “Voting Your Shares.”
In order to attend the Plum Shareholders’ Meeting, submit questions and vote, Plum Shareholders will need a control number. If you are a registered Plum Shareholder, you received a proxy card with this proxy statement/prospectus that includes your control number. If you do not have your control number, contact the Transfer Agent, Continental Stock Transfer & Trust Company, by telephone at (917) 262-2373 or by email at proxy@continentalstock.com. If your Plum Common Shares are held in “street name” or are in a margin or similar account, you will need to contact your bank, broker or other nominee and obtain a legal proxy. Once you have received your legal proxy, you will need to contact the Transfer Agent to have a control number generated. Please allow up to 72 hours for processing your request for a control number.
Plum Shareholders can pre-register to attend the meeting. To pre-register, visit https://www [•] and enter your control number, name and email address. After pre-registering, Plum Shareholders will be able to vote or submit questions for the Plum Shareholders’ Meeting.
Plum Shareholders have multiple opportunities to submit questions to Plum for the Plum Shareholders’ Meeting. Plum Shareholders who wish to submit a question in advance may do so by pre-registering and then selecting the chat box link. Plum Shareholders also may submit questions live during the meeting. Questions pertinent to Plum Shareholders’ Meeting matters may be recognized and answered during the Plum Shareholders’ Meeting in Plum’s discretion, subject to time constraints. Plum reserves the right to edit or reject questions that are inappropriate for Plum Shareholders’ Meeting matters. In addition, Plum will offer live technical support for all Plum Shareholders attending the Plum Shareholders’ Meeting.
To attend and participate in the Plum Shareholders’ Meeting virtually, Plum Shareholders of record may visit https://www [•] and enter their 12 digit control number, regardless of whether such shareholders have pre-registered.
Pursuant to the Plum Articles, the Plum Board may postpone any general meeting at any time prior to such meeting for any reason or for no reason at any time prior to the time for holding such meeting or, if the meeting is adjourned, the time for holding such adjourned meeting. The Plum Board will give Plum Shareholders notice in writing of any cancellation or postponement. A postponement may be for a stated period of any length or indefinitely as the Plum Board may determine.
110
Proposals
At the Plum Shareholders’ Meeting, Plum Shareholders will vote on the following Proposals:
• The Domestication Proposal — To approve, by Special Resolution, the transfer of Plum by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and Cayman Islands Companies Act (As Revised) (the “Companies Act”) and the domestication of Plum (the “Domestication”) as a British Columbia corporation in accordance with the applicable provisions of the Business Corporations Act (British Columbia) (the “BCBCA”), including the adoption of the Domestication Articles (the “Domestication Proposal” or “Proposal No. 1”);
• Business Combination Proposal — To approve, by Ordinary Resolution, the Business Combination Agreement, dated as of August 22, 2024 (as may be amended, supplemented or otherwise modified from time to time, the “Business Combination Agreement” and the transactions contemplated thereby, collectively, the “Business Combination”) by Plum, Plum III Amalco Corp., a corporation formed under the Laws of the Province of British Columbia and a direct, wholly owned subsidiary of Plum (“Amalco”), Plum III Merger Corp., a corporation formed under the Laws of the Province of British Columbia (“PubCo”), and Tactical Resources Corp., a corporation formed under the Laws of the Province of British Columbia (“TRC”), including the Arrangement Resolution pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement attached hereto as Annex B, (i) Plum shall effect the Domestication, (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation (the “Business Combination Proposal” or “Proposal No. 2”). A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A.
• Advisory Organization Documents Proposal — To approve on a non-binding advisory basis, by Ordinary Resolution, the governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights, presented separately in accordance with U.S. Securities and Exchange Commission guidance (the “Advisory Organizational Documents Proposals” or “Proposal No. 3”). The full text of the PubCo Closing Articles are attached to the accompanying proxy statement/prospectus as Annex E. Proposal No. 3 is separated into sub-proposals submitted to Plum Shareholders to approve on a non-binding advisory basis, by Ordinary Resolution, those governance provisions contained in the PubCo Closing Articles that materially affect Plum Shareholders’ rights as described in the following paragraphs (a) – (d):
(a) the proposed PubCo Closing Articles would change the authorized share capital from the existing (i) 200,000,000 Plum Class A Shares, (ii) 20,000,000 Plum Class B Shares, and (iii) 1,000,000 preference shares of a nominal or par value of $0.0001 each, to an unlimited number of PubCo Common Shares (the “Authorized Capital Proposal” or “Proposal No. 3A”);
(b) the proposed PubCo Closing Articles would reduce the requisite quorum for a meeting of shareholders from (x) one or more shareholders holding at least a majority of the paid up voting share capital present in person or by proxy and entitled to vote at that meeting to (y) not less than one person holding or representing not less than 5% of the shares entitled to be voted at the meeting (the “Quorum Proposal” or “Proposal No. 3B”);
(c) the proposed PubCo Closing Articles would change the name of the company from “Plum III Merger Corp.” to “Tactical Resources Corporation” (the “Name Change Proposal” or “Proposal No. 3C”); and
(d) the proposed PubCo Closing Articles would not include provisions relating to the Plum Class B Shares, the Plum IPO, Sponsor, the Initial Business Combination and other related matters (the “Other Matters Proposal” or “Proposal No. 3D” and, together with the Authorized Capital Proposal, the Quorum Proposal and the Name Change Proposal, the “Sub-Proposals”);
111
• Incentive Plan Proposal — To approve, by Ordinary Resolution, for the purposes of complying with the rules of the Nasdaq Stock Market, the issuance of PubCo Common Shares pursuant to the PubCo Omnibus Equity Incentive Plan (the “Incentive Plan Proposal” or “Proposal No. 4”). A copy of the Incentive Plan is attached to this proxy statement/prospectus as Annex K;
• Adjournment Proposal — If put to Plum Shareholders for a vote, a proposal to approve, by Ordinary Resolution, the adjournment of the Plum Shareholders’ Meeting (i) to a later date or dates, if necessary or appropriate, to permit further solicitation and vote of proxies in the event that there are insufficient votes for, or otherwise in connection with, the approval of the foregoing proposals or (ii) if the board of directors of Plum determines before the Plum Shareholders’ Meeting that it is not necessary or no longer desirable to proceed with the proposals (the “Adjournment Proposal” or “Proposal No. 5” and, together with the Domestication Proposal, the Business Combination Proposal, the Incentive Plan Proposal and the Advisory Organizational Documents Proposals, the “Proposals”). If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only Proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
For more information on the Proposals, please see the sections entitled “Proposal No. 1 — The Domestication Proposal,” “Proposal No. 2 — The Business Combination Proposal,” “Proposal No. 3 — The Advisory Organizational Documents Proposals”, “Proposal No. 4 — The Incentive Plan Proposal” and “Proposal No. 5 — The Adjournment Proposal.”
Recommendation of the Plum Board of Directors FOR the Proposals
The Plum Board has unanimously determined that each of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposal, the Incentive Plan Proposal and the Adjournment Proposal (if put) is in the best interests of Plum and Plum Shareholders and unanimously recommends that Plum Shareholders vote “FOR” each Proposal being submitted to a vote of the Plum Shareholders at the Plum Shareholders’ Meeting. For more information, please see the sections entitled “Proposal No. 1 — The Domestication Proposal,” “Proposal No. 2 — The Business Combination Proposal,” “Proposal No. 3 — The Advisory Organizational Documents Proposals”, “Proposal No. 4 — The Incentive Plan Proposal” and “Proposal No. 5 — The Adjournment Proposal.”
When you consider the unanimous recommendation of the Plum Board in favor of approval of these Proposals, you should keep in mind that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, your interests as a shareholder. The existence of financial and personal interests of one or more of Plum’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of Plum and Plum Shareholders and what he, she or they may believe is best for himself or themselves in determining to recommend that shareholders vote for the proposals. Please see the subsection entitled “The Business Combination — Interests of Certain Persons in the Business Combination.”
Voting Power; Record Date
Only Plum Shareholders of record at the close of business on [•], 2025, the record date for the Plum Shareholders’ Meeting, will be entitled to vote at the Plum Shareholders’ Meeting. In respect of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal, each Plum Shareholder is entitled to one vote for each Plum Common Shares registered in its name as of the close of business on the record date. If a Plum Shareholder’s Plum Common Shares are held in “street name” or are in a margin or similar account, such shareholder should contact its broker, bank or other nominee to ensure that votes related to the shares beneficially owned by such shareholder are properly counted. On the record date, there were 1,016,833 Plum Public Shares outstanding and 7,062,500 Plum Class B Shares outstanding held by Sponsor and Plum’s independent directors.
Quorum and Required Vote for Proposals at the Plum Shareholders’ Meeting
A quorum of Plum Shareholders is necessary to hold a valid meeting. A quorum will be present at the Plum Shareholders’ Meeting if one or more shareholders holding at least a majority of the paid up voting share capital of Plum attend virtually or in person or are represented by proxy at the Plum Shareholders’ Meeting. Abstentions and broker non-votes will count as present for the purposes of establishing a quorum. As of the record date for the Plum Shareholders’ Meeting, 5,105,850 Plum Common Shares would be required to achieve a quorum.
112
Approval of the Domestication Proposal requires the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of not less than two thirds (662⁄3%) of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. The Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal require the affirmative vote (in person or by proxy, including by way of the online meeting option) of the holders of a majority of the outstanding Plum Class A Shares and Plum Class B Shares entitled to vote and actually cast thereon at the Plum Shareholders’ Meeting, voting as a single class. Accordingly, a Plum Shareholder’s failure to vote by proxy or to vote online at the Plum Shareholders’ Meeting will not, if a valid quorum is established, have any effect on the outcome of any vote on any of the Proposals. Abstentions and broker non-votes, while considered present for the purposes of establishing a quorum, will not count as votes cast at the Plum Shareholders’ Meeting (assuming a quorum is present).
The Closing is conditioned on the approval of the Domestication Proposal and the Business Combination Proposal at the Plum Shareholders’ Meeting. The Advisory Organizational Documents Proposals are non-binding and are not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. The Adjournment Proposal is not conditioned on the approval of any other Proposal set forth in this proxy statement/prospectus. If put forth at the Plum Shareholders’ Meeting, the Adjournment Proposal will be the first and only proposal voted upon and none of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals or the Incentive Plan Proposal will be submitted to the Plum Shareholders for a vote.
Voting Your Shares
If you are a shareholder of record, there are two ways to vote your Plum Common Shares at the Plum Shareholders’ Meeting:
• You can vote by signing and returning the enclosed proxy card. If you vote by proxy card, your “proxy,” whose name is listed on the proxy card, will vote your Plum Common Shares as you instruct on the proxy card. If you sign and return the proxy card but do not give instructions on how to vote your Plum Common Shares, your Plum Common Shares will be voted as recommended by the Plum Board “FOR” each of the Proposals;
• You can submit your proxy by telephone or over the internet by following the instructions on your proxy card; or
• You can attend the Plum Shareholders’ Meeting in person or virtually and vote.
If your Plum Common Shares are held in “street name” or are in a margin or similar account, you should contact your broker, bank or other nominee to ensure that votes related to the Plum Shares beneficially owned by you are properly counted. Beneficial shareholders who wish to vote by attending the Plum Shareholders’ Meeting in person or virtually must obtain a legal proxy by contacting the bank, broker or other nominee that holds their shares.
Revoking Your Proxy
If you are a shareholder of record and you give a proxy, you may revoke it at any time before it is exercised by doing any one of the following:
• you may send another proxy card with a later date;
• you may notify Plum, in writing, before the Plum Shareholders’ Meeting that you have revoked your proxy; or
• you may attend the Plum Shareholders’ Meeting, revoke your proxy and vote in person, as indicated above.
No Additional Matters May Be Presented at the Plum Shareholders’ Meeting
The Plum Shareholders’ Meeting has been called to consider only the approval of the Domestication Proposal, the Business Combination Proposal, the Advisory Organizational Documents Proposals, the Incentive Plan Proposal and (if put) the Adjournment Proposal. Under the Plum Articles, other than procedural matters incident to the conduct of the Plum Shareholders’ Meeting, no other matters may be considered at the Plum Shareholders’ Meeting if they are not included in this proxy statement/prospectus, which serves as the notice of the Plum Shareholders’ Meeting.
113
Who Can Answer Your Questions About Voting Your Shares
If you are a shareholder and have any questions about how to vote or direct a vote in respect of your Plum Common Shares, you may call or email [•], Plum’s proxy solicitor, at [•] (banks and brokers, please call collect at [•]) or [•].
Vote of the Sponsor or Former Sponsor
Pursuant to the Sponsor Support Agreement entered into in connection with the Business Combination, each of the Sponsor Parties agreed to vote any Plum Common Shares owned by them in favor of an Initial Business Combination. Pursuant to the Sponsor Support Agreement, the Sponsor Parties agreed, effective concurrently with the execution and delivery of the Business Combination Agreement, that Sponsor will be prohibited from voting any Plum Class A Shares purchased by Sponsor following Plum’s public announcement of Plum’s intention to engage in the Transactions for or against the Transactions. The Sponsor Support Agreement applies to Sponsor Parties as it relates to the Plum Founder Shares and the requirement to vote all of the Plum Founder Shares in favor of the Business Combination Proposal. As of the record date, the Sponsor Parties own 7,062,500 Plum Founder Shares, representing approximately 87.4% of the Plum Common Shares then outstanding and entitled to vote at the Plum Shareholders’ Meeting. The Sponsor Parties have agreed to waive any redemption rights with respect to Plum Class A Shares purchased in the Plum IPO or in the aftermarket, in connection with the Business Combination. Additionally, pursuant to the Sponsor Parties are not entitled to redemption rights with respect to any Plum Founder Shares held by them in connection with the consummation of the Business Combination or upon Plum’s liquidation. The Plum Founder Shares will be worthless if no Business Combination is effected by Plum by the Deadline Date. However, the Sponsor Parties are entitled to redemption rights upon Plum’s liquidation with respect to any Plum Class A Shares they may own.
Redemption Rights
Pursuant to the Plum Articles, any holders of Plum Public Shares other than Sponsor or Plum management may elect to have their Plum Public Shares redeemed for cash at a per-share redemption price equal to the aggregate amount then on deposit in the Trust Account, including interest earned on the funds held in the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination, divided by the number of then-outstanding Plum Public Shares. If demand is properly made and the Business Combination is consummated, such holder of PubCo Common Shares received in exchange for Plum Public Shares pursuant to the Business Combination Agreement will hold only the right to receive its pro rata share of the aggregate amount on deposit in the Trust Account which holds a portion of the proceeds of the Plum IPO and the sale of the Plum Private Placement Warrants (calculated as of two business days prior to the consummation of the Business Combination, less taxes payable). If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation Effective Time and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. You will no longer own those shares and you will have no right to participate in, or have any interest in, the future growth of PubCo, if any. You will be entitled to receive cash for your PubCo Common Shares only if you properly and timely demand redemption. For illustrative purposes, based on the fair value of marketable securities held in the Trust Account of approximately $25.6 million as of December 31, 2024, the estimated per share redemption price would have been approximately $11.22.
Each redemption of PubCo Common Shares by Plum Public Shareholders will reduce the amount in the Trust Account.
To exercise your redemption rights, you must:
• if you hold Plum Units, elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants;
114
• prior to 10:30 a.m., Eastern Time on [•], 2025 (two business days before the Plum Shareholders’ Meeting), tender your shares physically or electronically and submit a request in writing that PubCo redeem your PubCo Common Shares that you receive in exchange for your Plum Public Shares for cash to Continental Stock Transfer & Trust Company, the Transfer Agent, at the following address:
Continental Stock Transfer & Trust Company
1 State Street, 30th Floor
New York, New York 10004
Attention: Mark Zimkind
Email: mzimkind@continentalstock.com;
and
• deliver your Plum Public Shares through DTC’s DWAC system to the Transfer Agent at least two business days before the Plum Shareholders’ Meeting. Plum Shareholders who hold their shares in street name will have to coordinate with their bank, broker or other nominee to have the shares delivered electronically. If you do not submit a written request and deliver your Plum Public Shares as described above, your shares will not be redeemed.
Plum Shareholders seeking to exercise their redemption rights, whether they are record holders or hold their Plum Common Shares in “street name” are required to either tender their certificates to the Transfer Agent prior to the date set forth in this proxy statement/prospectus, or up to two business days prior to the vote on the proposal to approve the Business Combination at the Plum Shareholders’ Meeting, or to deliver their shares to the Transfer Agent electronically using DTC’s DWAC system, at such shareholder’s option. The requirement for physical or electronic delivery prior to the Plum Shareholders’ Meeting ensures that a redeeming shareholder’s election to redeem is irrevocable without Plum’s consent once the Business Combination is consummated.
Holders of outstanding Plum Units must elect to separate their Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising redemption rights with respect to the Plum Public Shares.
If you hold Plum Units registered in your own name, you must deliver the certificate for such Plum Units to Continental Stock Transfer & Trust Company, the Transfer Agent, with written instructions to separate such Plum Units into Plum Public Shares and Plum Public Warrants. This must be completed far enough in advance to permit the mailing of the Plum Public Share certificates back to you so that you may then exercise your redemption rights upon the separation of the Plum Public Shares from the Plum Units.
If a broker, dealer, commercial bank, trust company or other nominee holds your Plum Units, you must instruct such nominee to separate your Plum Units. Your nominee must send written instructions by facsimile to Continental Stock Transfer & Trust Company, the Transfer Agent. Such written instructions must include the number of Plum Units to be split and the nominee holding such Plum Units. Your nominee must also initiate electronically, using DTC’s DWAC system, a withdrawal of the relevant units and a deposit of a corresponding number of Plum Public Shares and the applicable fraction of Plum Public Warrants. This must be completed far enough in advance to permit your nominee to exercise your redemption rights upon the separation of the Plum Public Shares from the Plum Units. While this is typically done electronically on the same business day, you should allow at least one full business day to accomplish the separation. If you fail to cause your Plum Units to be separated in a timely manner, you will likely not be able to exercise your redemption rights.
Prior to exercising redemption rights, Plum Shareholders should verify the market price of the Plum Class A Shares, as shareholders may receive higher proceeds from the sale of their Plum Class A Shares in the public market than from exercising their redemption rights if the market price per share is higher than the redemption price. You may not be able to sell your Plum Class A Shares in the open market, even if the market price per share is higher than the redemption price stated above, as there may not be sufficient liquidity in the Plum Class A Shares when you wish to sell your shares.
115
If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation Effective Time and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. You will no longer own those shares and you will have no right to participate in, or have any interest in, the future growth of PubCo, if any. You will be entitled to receive cash for your PubCo Common Shares only if you properly and timely demand redemption.
Each redemption of PubCo Common Shares by Plum Public Shareholders will reduce the amount in the Trust Account.
Pursuant to Section 172 of the Plum Articles, if Plum does not consummate an Initial Business Combination by the Deadline Date, Plum will be required to dissolve and liquidate the Trust Account by returning the then remaining funds in such account to the Plum Public Shareholders and all of Plum’s warrants will expire worthless.
Any request for redemption, once made by a holder of Public Shares, may be withdrawn at any time up to the time the vote is taken with respect to the Business Combination Proposal at the Plum Shareholders’ Meeting or thereafter with Plum’s consent until the consummation of the Business Combination. If you deliver your shares for redemption to Continental, Plum’s Transfer Agent, and later decide prior to the Plum Shareholders’ Meeting not to elect redemption, you may request that Continental, Plum’s Transfer Agent, return the shares (physically or electronically) to you. You may make such request by contacting Continental, Plum’s Transfer Agent, at the phone number or address listed herein.
Appraisal or Dissent Rights
There is no mandatory statutory right of dissent and appraisal in respect of plans of arrangement under the BCBCA unless the terms of the arrangement permits dissent. The Business Combination Agreement does not contemplate any dissent rights or appraisal rights to be available to holders of Plum Class A Shares and Plum Class B Shares in connection with the Business Combination. However, Plum Shareholders are still entitled to exercise the rights of redemption as set out in the section entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” and the Plum Board has determined that the redemption proceeds payable to Plum Shareholders who exercise such redemption rights represents the fair value of those Plum Common Shares.
Proxy Solicitation Costs
Plum is soliciting proxies on behalf of the Plum Board. This solicitation is being made by mail but also may be made by telephone, in person or by electronic means. Plum will bear the cost of the solicitation.
Plum has engaged [•] to assist in the solicitation of proxies, and will pay [•] a fee of $[•], plus disbursements. Plum will reimburse [•] for reasonable and documented out-of-pocket expenses and will indemnify [•] and its affiliates against certain claims, liabilities, losses, damages and expenses.
Plum will ask banks, brokers and other institutions, nominees and fiduciaries to forward the proxy materials to their principals and to obtain their authority to execute proxies and voting instructions, and will reimburse such parties for their expenses in forwarding soliciting materials to beneficial owners of Plum Class A Shares and in obtaining voting instructions from those owners.
Plum management may also solicit proxies by telephone, by facsimile, in person or by electronic means. They will not be paid any additional amounts for soliciting proxies.
116
Overview
We are asking our shareholders to adopt and approve the Business Combination Agreement, certain related agreements and the transactions contemplated thereby.
Plum Shareholders should read carefully this proxy statement/prospectus in its entirety for more detailed information concerning the Business Combination Agreement, which is attached as Annex A to this proxy statement/prospectus, and the transactions contemplated thereby. Please see “— The Business Combination Agreement” below for additional information and a summary of certain terms of the Business Combination Agreement. You are urged to read carefully the Business Combination Agreement in its entirety before voting on this proposal.
Because we are holding a shareholder vote on the Business Combination, we may consummate the Business Combination only if it is approved by an Ordinary Resolution, being the affirmative vote of a majority of the votes cast by the holders of the outstanding Plum Class A Shares and Plum Class B Shares present in person or represented by proxy at the Plum Shareholders’ Meeting and entitled to vote on such matter.
Structure of the Business Combination
On August 22, 2024, Plum, TRC, PubCo, and Amalco, entered into a Business Combination Agreement, pursuant to which, among other things and subject to the terms and conditions contained in the Business Combination Agreement and the Plan of Arrangement, (i) Plum will transfer by way of continuation from the Cayman Islands to the Province of British Columbia, Canada in accordance with the Plum Articles and the Companies Act and domesticate as a British Columbia corporation in accordance with the BCBCA, (ii) Plum will amalgamate with PubCo, with PubCo surviving as PubCo in accordance with the terms of the Plan of Arrangement and (iii) TRC will amalgamate with Amalco, with the amalgamated company becoming a wholly owned subsidiary of PubCo in accordance with the terms of the Plan of Arrangement.
The Business Combination Agreement
The material terms of the Business Combination Agreement, which contain customary representations and warranties, covenants, closing conditions, termination provisions, and other terms relating to the Business Combination, are summarized below, but it does not purport to describe all of the terms of the Business Combination Agreement. The following summary is qualified in its entirety by reference to the complete text of the Business Combination Agreement, which is attached as Annex A to this proxy statement/prospectus. You are urged to read the Business Combination Agreement in its entirety because it is the primary legal document that governs the Business Combination.
The Business Combination Agreement contains representations, warranties and covenants that the respective parties made to each other as of the date of the Business Combination Agreement or other specific dates. The assertions embodied in those representations, warranties and covenants were made for purposes of the contract among the respective parties and are subject to important qualifications and limitations agreed to by the parties in connection with negotiating the Business Combination Agreement. The representations, warranties and covenants in the Business Combination Agreement are also modified in part by the disclosure schedules, which are not filed publicly, which are subject to a contractual standard of materiality different from that generally applicable to shareholders, and which were used for the purpose of allocating risk among the parties rather than establishing matters as facts. We do not believe that the disclosure schedules contain information that is material to an investment decision.
Additionally, the representations and warranties of the parties to the Business Combination Agreement may or may not have been accurate as of any specific date and do not purport to be accurate as of the date of this proxy statement/prospectus. Accordingly, no person should rely on the representations and warranties in the Business Combination Agreement or the summaries thereof in this proxy statement/prospectus as characterizations of the actual state of facts about TRC, Plum, PubCo or any other matter.
In connection with the Business Combination, certain related agreements have been, or will be entered into on or prior to Closing, including the Sponsor Support Agreement, TRC Securityholder Support Agreements, Registration Rights Agreement, and the Sponsor Parties Lock-Up Agreement. See “The Business Combination — Related Agreements” for more information.
117
On December 10, 2024, Plum and TRC entered into an amendment (the “Amendment”) to the Business Combination Agreement.
The Amendment, among other things, provides (a) that Plum will apply for and effect a listing of Plum’s publicly-traded securities with OTC Markets Group (“OTC Markets”), which listing will take effect no later than ten business days following any delisting of such Plum securities from Nasdaq on January 27, 2025 (the “Nasdaq De-Listing Date”), (b) that Plum shall prepare and file with the SEC a proxy statement for the purpose of amending the Amended and Restated Memorandum and Articles of Association of Plum (the “Articles”) to (i) extend the deadline for Plum to consummate an initial business combination from January 30, 2025 to July 30, 2025 (the “Extension Amendment Proposal”) and (ii) remove the requirement in Plum’s Articles that Plum have net tangible assets of at least $5,000,001 immediately prior to, or upon consummation of, an initial business combination (the “NTA Amendment Proposal” and such requirement, the “NTA Requirement”), (c) that Plum comply with all applicable rules and regulations of Nasdaq or OTC Markets, as applicable, (d) that Plum use commercially reasonable efforts to ensure that Plum’s publicly-traded securities continue to be qualified to trade on OTC Markets from and after the Nasdaq De-Listing Date, (e) that the parties use commercially reasonable efforts to cause Plum’s publicly-traded securities to be delisted from OTC Markets as of the Company Amalgamation Effective Time or as soon as practicable thereafter, (f) that the closing condition requiring PubCo to satisfy the NTA Requirement shall not be applicable in the event that Plum’s shareholders approve the NTA Amendment Proposal and Plum amends the Articles to remove the NTA Requirement, and (g) that the Agreement End Date shall be automatically extended to July 30, 2025 in the event that Plum’s shareholders approve the Extension Amendment Proposal and Plum amends the Articles to extend its deadline to consummate an initial business combination to July 30, 2025.
In January 28, 2025, Plum and TRC entered into Amendment No. 2 (the “Second Amendment”) to the Business Combination Agreement.
The Second Amendment provides that certain recently issued convertible debentures of TRC (and future issuances of convertible debentures by TRC, if any, to the extent permitted under the Business Combination Agreement) shall be subject to the same terms under the Business Combination Agreement, and shall be subject to the same treatment upon closing of the Business Combination as certain existing convertible debentures issued by TRC and already subject to the terms of the Business Combination Agreement.
Organizational Structure
The following diagram illustrates the organizational structure of Plum and TRC immediately prior to the Business Combination:
The following diagram illustrates the structure of PubCo immediately following the Business Combination. The percentages shown reflect the voting power and economic interests in PubCo on a combined basis, in each case assuming no redemptions, assuming illustrative redemptions or assuming maximum redemptions. Interests shown exclude (i) 9,416,666 PubCo Common Shares underlying the PubCo Public Warrants, (ii) 2,642,500 PubCo Common
118
Shares underlying the PubCo Private Placement Warrants and Founder Warrants, (iii) 2,085,673 PubCo Common Shares underlying the TRC Options, (iv) 3,104,561 PubCo Common Shares underlying the TRC RSUs, (v) 6,406,368 PubCo Common Shares underlying the TRC Warrants, (vi) 3,918,801 PubCo Common Shares underlying the TRC Debentures, or (vii) up to 8,229,736 PubCo Common Shares underlying the TRC Incentive Plan. Please see the subsection entitled “The Business Combination — Ownership of PubCo Common Shares After Closing” for additional assumptions used in calculating such percentages.
Conversion of Securities
Pursuant to the Plum Amalgamation, which will take place after the Domestication and on the date on which the closing of the Business Combination will occur (the “Closing” and such date the “Closing Date”):
(a) each Plum Unit shall be automatically divided, and the holder thereof shall be deemed to hold one Plum Class A Share, par value $0.0001 per share (a “Plum Class A Share”) and one-third of one Plum Warrant in accordance with the terms of the applicable Plum Unit;
(b) each Plum Class A Share and Plum Class B ordinary share, par value $0.0001 per share (a “Plum Class B Share” and together with the Plum Class A Shares, the “Plum Common Shares”), will be exchanged on a one-for-one basis, for a common share in the authorized share capital of PubCo (a “PubCo Common Share”); and
(c) each Plum Warrant shall automatically be converted into a warrant (each, a “PubCo Assumed Plum Warrant”) to purchase a number of PubCo Common Shares determined in accordance with the terms of such Plum Warrant.
119
On the Closing Date, pursuant to the TRC Amalgamation, among other things:
(a) each TRC Common Share (other than any Cancelled TRC Shares or Dissenting Shares) shall automatically be exchanged for the right to receive a number of PubCo Common Shares equal to the TRC Exchange Ratio (the aggregate of all such PubCo Common Shares, the “Arrangement Consideration Shares”). Any Arrangement Consideration Shares exchanged for TRC Common Shares which were subject to any vesting or forfeiture terms shall continue to be governed by such terms from and after the TRC Amalgamation Effective Time;
(b) each of the Dissenting Shares shall be cancelled and shall thereafter represent only the right to receive the applicable payments set forth in the Plan of Arrangement;
(c) each TRC Option shall be assumed by PubCo and converted into an option to purchase PubCo Common Shares (each, a “Converted TRC Option”), subject to the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such Converted TRC Option shall be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
(d) each TRC RSU shall be assumed by PubCo and converted into a restricted stock unit in respect of PubCo Common Shares (each, a “Converted TRC RSU”), subject to the same terms and conditions as were previously applicable thereto, except that such Converted TRC RSU shall be in respect of a number of PubCo Common Shares equal to the product of (A) the number of shares previously subject to such TRC RSU and (B) the TRC Exchange Ratio;
(e) each TRC Warrant shall automatically be converted into a warrant to purchase PubCo Common Shares (each, a “PubCo Assumed TRC Warrant”), and such PubCo Assumed TRC Warrant shall continue to be governed by the same terms and conditions as were previously applicable, except that (A) the number of TRC Common Shares subject to such PubCo Assumed TRC Warrant shall be increased by multiplying the number of shares previously issuable thereunder by the TRC Exchange Ratio, rounded down to the nearest whole PubCo Common Share, and (B) the per share exercise price shall be reduced by dividing the previous exercise price thereof by the TRC Exchange Ratio (rounded up to the nearest cent);
(f) the TRC Convertible Debenture shall survive the TRC Amalgamation in accordance with the terms thereof (subject to the conversion rights of the holder set forth therein); and
(g) each Amalco Share shall automatically be exchanged for one validly-issued, fully paid and nonassessable common share of TRC.
Dissent Rights.
To the extent available under the BCBCA, any TRC Common Shares that are outstanding immediately prior to TRC Amalgamation Effective Time and that are held by TRC Shareholders who have not voted in favor of the Arrangement nor consented thereto in writing and who have given a notice of election to dissent pursuant to Section 242 of the BCBCA and otherwise complied with all of the provisions of the BCBCA relevant to the exercise and perfection of dissenters’ rights with respect to such TRC Common Shares (the “Dissenting Shares”) shall not be exchanged for, and any such TRC Shareholder shall have no right to receive, any Arrangement Consideration pursuant to the Arrangement, and any holder of Dissenting Shares shall cease to have any of the rights as a shareholder of TRC save for the right to be paid fair value for such holder’s Dissenting Shares in accordance with the Plan of Arrangement. Any TRC Shareholder who prior to TRC Amalgamation Effective Time fails to perfect or validly withdraws a notice of election to dissent or otherwise loses his, her or its rights to payment for their TRC Common Shares pursuant to Section 245 of the BCBCA shall be treated in the same manner as a TRC Shareholder who did not give a notice of election to dissent pursuant to Section 242 of the BCBCA.
Closing and Effective Time of the Business Combination
The Closing of the transactions contemplated by the Business Combination Agreement is required to take place electronically by exchange of the Closing deliverables following the satisfaction (or, to the extent permitted by applicable law, waiver) of the conditions described below under the section entitled “The Business
120
Combination — Conditions to Closing of the Business Combination” (other than those conditions that by their nature are to be satisfied at the Closing, but subject to satisfaction or waiver of such conditions) or at such other place, date and/or time as Plum and TRC may agree in writing.
Conditions to Obligations of Each Party
The obligations of each of the Parties to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following conditions, any one or more of which may be waived in writing by PubCo, Plum and TRC:
• The Plum Shareholders’ Approval shall have been obtained.
• TRC Shareholders’ Approval shall have been obtained.
• Each of the Interim Order and the Final Order shall have been granted.
• All Regulatory Approvals shall have been obtained and any applicable waiting periods therefor shall have expired or been terminated.
• The proxy/registration statement shall have become effective under the Securities Act, and no stop order suspending the effectiveness of the proxy/registration statement shall be in effect.
• No Governmental Authority shall have enacted any Law or Governmental Order making the Transactions illegal.
• The PubCo Common Shares and the PubCo Warrants shall have been accepted for listing on Nasdaq.
• The distribution of the PubCo Common Shares pursuant to the Arrangement shall be exempt from the prospectus and registration requirements of applicable securities Laws in Canada.
• PubCo shall have paid the outstanding TRC and Plum transaction expenses as required by the Business Combination Agreement and the aggregate outstanding amount due under all working capital loans to Plum from Sponsor.
Conditions to Obligations of PubCo, Plum and Amalco
The obligations of PubCo, Plum and Amalco to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following additional conditions, any one or more of which may be waived in writing by PubCo, Plum and Amalco:
• Subject to certain limitations and qualifications, each of the representations and warranties of TRC contained in the Business Combination Agreement shall be true and correct as of the Closing Date as if made on that date.
• Each of the covenants of TRC to be performed prior to the Closing Date shall have been performed in all material respects.
• TRC shall have delivered to Plum each of the deliverables required by the Business Combination Agreement.
• No TRC Material Adverse Effect shall have occurred that is continuing.
Conditions to Obligations of TRC
The obligations of TRC to consummate, or cause to be consummated, the Transactions are subject to the satisfaction of the following additional conditions, any one or more of which may be waived in writing by TRC:
• Subject to certain limitations and qualifications, each of the representations and warranties of PubCo, Plum and Amalco contained in the Business Combination Agreement shall be true and correct as of the Closing Date as if made on that date.
• Each of the covenants of PubCo, Plum and Amalco to be performed prior to the Closing Date shall have been performed in all material respects.
121
• No Plum Material Adverse Effect shall have occurred.
• PubCo shall have delivered each of the deliverables required by the Business Combination Agreement.
• PubCo shall have deposited with the Depositary the Exchange Fund and the Irrevocable Direction.
• Effective as of the Closing, the directors and officers of PubCo and Amalco shall have resigned.
Representations and Warranties
The Business Combination Agreement contains a number of representations and warranties made by TRC, Plum, Amalco and PubCo as of the date of such agreement or other specific dates solely for the benefit of certain of the parties to the Business Combination Agreement, which in certain cases are subject to specified exceptions and materiality, Material Adverse Effect, knowledge and other qualifications contained in the Business Combination Agreement or in information provided pursuant to certain disclosure schedules to the Business Combination Agreement.
In the Business Combination Agreement, TRC made certain customary representations and warranties to Plum, including:
Representations and Warranties of TRC
1. TRC is a corporation duly incorporated, validly existing and in good standing under the Laws of the Province of British Columbia. TRC has all requisite corporate power and authority to own, lease and operate its properties and assets and to carry on its business as presently conducted.
2. TRC is presently qualified or licensed to do business as a foreign corporation in each jurisdiction in which it is required to be so qualified or licensed and is in good standing in each such jurisdiction.
3. TRC has provided to Plum true, correct and complete copies of TRC Governing Documents. Each of TRC Governing Documents is in full force and effect.
4. TRC does not directly or indirectly own any Equity Securities of any Person.
5. The authorized share capital of TRC consists of an unlimited number of TRC Common Shares.
6. All TRC Securities that are issued and outstanding have been duly authorized and validly issued in compliance with applicable Laws, are fully paid and nonassessable
7. Other than TRC Shareholders’ Approval, there is no consent required of TRC Shareholders in connection with the Transactions.
8. TRC has provided Plum with a complete list of TRC Warrants, TRC RSUs and TRC Options issued and outstanding as of the date of the Business Combination Agreement, and the identity of the Persons that are the holders thereof. Except as disclosed to Plum, there are no authorized or issued options, warrants, convertible securities or other equity appreciation, phantom equity, profit participation, purchase options, call options, rights of first refusal, rights of first offer, preemptive rights, subscription rights, conversion rights or other similar rights, or any Contracts of any character obligating TRC to issue, exchange, transfer, deliver or sell any Equity Securities of TRC.
9. TRC has all requisite corporate power and authority to execute and deliver the Business Combination Agreement and each Ancillary Agreement, to perform its obligations hereunder and thereunder and to consummate the Transactions. The Business Combination Agreement and each of the Ancillary Agreements constitute legal, valid and binding obligations of TRC, enforceable against TRC in accordance with their respective terms.
10. Each of the financial statements of TRC are true and correct in all material respects and present fairly the financial condition, operating results, changes in shareholders equity and cash flows of TRC as at the dates and during the periods therein indicated. Each of TRC Financial Statements has been prepared in accordance with IFRS, applied on a consistent basis throughout the periods indicated, and comply in all material respects with applicable accounting requirements, rules and regulations of the CSA and securities Laws.
122
11. TRC has established and maintains disclosure controls and procedures that are designed to provide reasonable assurances that material information relating to TRC and other material information required to be disclosed by TRC is recorded, processed, summarized and reported within the time periods specified in the rules and forms of the CSA. TRC has established and maintains a system of internal controls over financial reporting sufficient to provide reasonable assurances that (i) transactions are executed in accordance with management’s general or specific authorizations, (ii) transactions are recorded as necessary to permit preparation of financial statements in conformity with IFRS and to maintain asset accountability, (iii) access to assets is permitted only in accordance with management’s general or specific authorizations, (iv) the recorded accountability for assets is compared with the existing assets at reasonable intervals and appropriate action is taken with respect to any differences and (v) records are maintained in reasonable detail which accurately and fairly reflect, in all material respects, its transactions and dispositions of assets.
12. Since December 31, 2021, neither TRC nor, to the Knowledge of TRC, any Representative of TRC has received or otherwise had or obtained knowledge of any written complaint, allegation, assertion or claim regarding the accounting or auditing practices, procedures, methodologies or methods of TRC with respect to TRC Financial Statements or the internal accounting controls of TRC.
13. As of the date of the Business Combination Agreement, except for TRC Convertible Debenture, TRC has no Indebtedness.
14. TRC’s current auditors are independent with respect to TRC within the meaning of the rules of professional conduct applicable to auditors in Canada.
15. TRC Disclosure Schedules lists all Contracts (other than TRC Benefit Plans) to which TRC is a party or by which any of its assets or properties is bound that constitute or involve the following (each of the following, a “Material Contract”):
(a) Contracts (A) with any of the Affiliates of TRC or (B) pursuant to which TRC receives any “preferred pricing” or similar benefit;
(b) Contracts evidencing any Indebtedness of $100,000 or more;
(c) any Contract with the top five suppliers of TRC;
(d) any Real Property Lease;
(e) Contracts with any Governmental Authority;
(f) Contracts awarded by TRC to a third party in the performance of a Contract with a Governmental Authority;
(g) Contracts which (A) limit, or purport to limit, the right of TRC to engage or compete in any line of business or with any Person or in any geographic area or during any period of time, (B) require TRC to conduct any business on a “most favored nations” basis with any third party or (C) provide for “exclusivity” or any similar requirement in favor of any third party;
(h) Contracts between TRC and any Related Party of TRC;
(i) Contracts providing for (A) the sale of any material properties or tangible assets of TRC, (B) the grant to any Person of any preferential rights to purchase any material properties or tangible assets of TRC or (C) the acquisition by TRC of any operating business or material properties or assets for consideration in excess of $500,000;
(j) Contracts providing for any interest rate, commodity or currency protection;
(k) any partnership, joint venture or similar agreements;
(l) Contracts involving any resolution or settlement of any Action that require future payments by TRC in excess of $100,000 or impose injunctive or other non-monetary relief;
(m) Contracts granting a license or other permission to use any Intellectual Property of TRC;
123
(n) Contracts to make payments, contingent or otherwise, arising out of the prior acquisition of the business, assets or stock of other Persons;
(o) Contracts granting any Person an irrevocable power of attorney from TRC; and
(p) Contracts for the use by TRC of any tangible property where the annual lease payments are greater than $100,000.
16. Each Material Contract is in full force and effect and a legal, valid, binding obligation of TRC and, to the Knowledge of TRC, the other parties thereto.
17. The TRC Disclosure Schedules sets forth an accurate and complete list, as of the date of the Business Combination Agreement, of each item of Owned Registered IP.
18. Each item of Owned Registered IP valid and enforceable. There are no Actions currently before any Governmental Authority relating to the validity, enforceability, registrability, scope or ownership with respect to any material Owned Registered IP. Except as would not be material to TRC, TRC is the sole and exclusive owner of any and all Owned Registered IP, free and clear of all Liens, except for Permitted Liens.
19. There is no infringement, misappropriation or other violation of any material Owned Intellectual Property by any third party. The operation of TRC’s business as currently conducted does not infringe, misappropriate or otherwise violate any Intellectual Property owned by any third party
20. TRC has good and marketable title to its tangible properties, assets and rights, free and clear of any Liens, other than Permitted Liens.
21. TRC does not own any real property, and TRC is not a party to any Contract under which it has a right to purchase any real property.
22. The TRC Disclosure Schedules sets forth a true, correct and complete list of all leases real property held by TRC.
23. The property and facility leased or operated by TRC is in material compliance with all Environmental Laws.
24. TRC possesses all material Environmental Permits that are required for the operation of its business as presently conducted.
25. There has been no Release of any Hazardous Materials by TRC at, in, on, under or from any real property currently leased or operated by TRC.
26. The execution and delivery by TRC of, and the performance by TRC of its obligations pursuant to, the Business Combination Agreement and each of the Ancillary Agreements will not result in any violation of, conflict with, or require any consent, filing, notice, waiver or approval under (i) TRC Governing Documents, (ii) any Material Contract or (iii) any applicable Law, Permit or Governmental Order.
27. TRC is conducting its business and operations in compliance with all applicable Laws.
28. TRC has obtained, and is in compliance in all material respects with, all Permits required by applicable Laws necessary to conduct its business as currently conducted.
29. Since the date of the most recent TRC Financial Statements (a) there has not been, individually or in the aggregate, any TRC Material Adverse Effect and (b) TRC has conducted its business in all material respects in the Ordinary Course.
30. There are no Actions pending or threatened against TRC or any of its assets or properties.
31. TRC has in full force and effect insurance policies that cover such risks and are in such amounts as are determined by TRC to be reasonable for the business of TRC.
124
32. No consent any Governmental Authority on the part of TRC is required in connection with the execution and delivery of the Business Combination Agreement or any Ancillary Agreement to which TRC is or will be a party or the consummation of the Transactions, except those expressly contemplated in the Business Combination Agreement.
33. No broker, finder, agent or similar intermediary has acted on behalf of TRC.
34. Except with respect to actions expressly contemplated by the Business Combination Agreement, any of the Ancillary Agreements or any TRC Benefit Plan, no Related Party is a party to any Contract with TRC.
35. The TRC Disclosure Schedules sets forth a true, complete and accurate list of each independent contractor of TRC, including the terms of such engagement. Each independent contractor of TRC has been properly classified as an independent contractor and TRC has not received any notice from any Governmental Authority disputing such classification. As of the date of the Business Combination Agreement, TRC has no employees. No officer of TRC intends to terminate his or her service with TRC, nor does TRC have any present intention to terminate the service of any of the forgoing.
36. Each TRC Benefit Plan has been established, administered, operated and funded in accordance with its terms and in compliance with all applicable Laws in all material respects. There are no pending or threatened Actions by any Person against or relating to TRC Benefit Plans, other than routine benefits claims.
37. TRC: (i) has filed all material Tax Returns required to be filed by it, and all such filed Tax Returns are complete and accurate in all material respects; (ii) has timely paid all material Taxes on such filed Tax Returns and any other material Taxes that TRC is otherwise obligated to pay; (iii) has not waived any statute of limitations with respect to material Taxes or agreed to any extension of time with respect to a material Tax assessment or deficiency; and (iv) does not have any deficiency, audit, examination, investigation or other proceeding in respect of material Taxes or Tax matters pending or proposed or threatened in writing.
38. The minute books of TRC, copies of which have been provided to Plum, contain complete and accurate records in all material respects of all meetings and other corporate actions of TRC Shareholders and TRC Board and all committees thereof.
39. TRC complies, and since December 31, 2021 TRC has complied, in all material respects, with all Privacy and Information Security Requirements.
40. Neither TRC nor any of its Representatives, distributors, resellers or other third parties acting on behalf of TRC have made, directly or indirectly, any payment or promise to pay, or any gift or promise to give or authorized such a promise or gift, of any money or anything of value, directly or indirectly, corruptly, to (a) any foreign official (as such term is defined in the U.S. Foreign Corrupt Practices Act (the “FCPA”)) for the purpose of influencing any official act or decision of such foreign official or inducing him or her to use his or her influence to affect any act or decision of a Governmental Authority or (b) any foreign political party or official thereof or candidate for foreign political office for the purpose of influencing any official act or decision of such party, official or candidate or inducing such party, official or candidate to use his, her or its influence to affect any act or decision of a Governmental Authority, in the case of both clauses (a) and (b) above, in order to assist TRC to obtain or retain business for, or direct business to, TRC.
41. The operations of TRC are and have been conducted at all times since December 31, 2021 in compliance with applicable financial recordkeeping and reporting requirements of the Currency and Foreign Transactions Reporting Act of 1970, applicable provisions of the USA PATRIOT Act of 2001, applicable provisions of the Proceeds of Crime (Money Laundering) and Terrorist Financing Act (Canada), and applicable money laundering Laws of all jurisdictions in which TRC conducts its business, or similar rules, regulations or guidelines, issued, administered or enforced by any Governmental Authority having jurisdiction over TRC (collectively, the “Anti-Money Laundering Laws”).
125
42. Neither TRC nor any of its Representatives is a Person that is, or is owned or controlled by a Person that is, (a) the subject of any Sanctions or (b) located, organized, incorporated or resident in a country or territory that is the subject of comprehensive Sanctions (including the Crimea, Donetsk and Luhansk regions of Ukraine, Russia, Cuba, Iran, North Korea and Syria).
43. TRC and its Representatives in their capacities as such, have been in compliance with all applicable Export Laws.
44. None of the information supplied or to be supplied by or on behalf of TRC for inclusion or incorporation by reference in any public filing will contain any untrue statement of a material fact or omit to state a material fact required to be stated therein or necessary to make the statements contained therein, in light of the circumstances under which they are made, not misleading.
45. TRC has timely filed or furnished all statements, prospectuses, registration statements, forms, certifications, schedules, exhibits, reports and documents required to be filed or furnished by it with the CSA (collectively, as they have been amended or supplemented since the time of their filing through the date that is one Business Day prior to the date of the Business Combination Agreement, the “TRC CSA Filings”), including with respect to the Peak REE Project. Each TRC CSA Filing, as of the date of its filing, and as of the date of any amendment or supplement thereto, complied in all material respects with the requirements of applicable Law. As of the date of its filing (or if amended or superseded by a filing, the initial filing), each TRC CSA Filing did not contain any untrue statement of a material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements made therein, in light of the circumstances under which they were made, not misleading.
46. TRC Common Shares are listed for trading on (a) the OTC Markets under the symbol “USREF” and (b) TSX-V under the symbol “RARE”. TRC is in compliance in all material respects with the rules of the OTC Markets and TSX-V and there is no Action pending or, to the Knowledge of TRC, threatened against TRC by the OTC Markets Group or the TMX Group with respect to any intention by such entity to deregister TRC Common Shares or terminate the listing of TRC Common Shares on the OTC Markets or TSX-V.
47. TRC is not a “cultural business” within the meaning of the ICA.
48. TRC Board has unanimously (with conflicted directors abstaining) (a) determined that it is fair to, advisable for and in the best interests of TRC and TRC Shareholders for TRC to enter into the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and to consummate the Transactions, (b) approved the execution and delivery of the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and (c) recommended that TRC Shareholders vote in favor of TRC Arrangement Resolution at TRC Shareholders Meeting, on the terms and subject to the conditions set forth in the Business Combination Agreement. TRC Shareholders’ Approval represents the only approval of the holders of any Equity Securities of TRC necessary in connection with the entry into the Business Combination Agreement by TRC and the consummation of the Transactions.
49. TRC is not the subject of an Insolvency Event.
Representations and Warranties of Plum and Amalco
1. Plum is an exempted company duly organized, validly existing and in good standing under the Laws of the Cayman Islands. Plum has all requisite corporate power and authority to own, lease and operate its properties and assets and to carry on its business as presently conducted.
2. Plum is presently qualified or licensed to do business as a foreign corporation in each jurisdiction in which it is required to be so qualified or licensed and is in good standing in each such jurisdiction (or the equivalent thereof.
3. Plum has provided to TRC true, correct and complete copies of the Plum Governing Documents, each as amended, restated or otherwise modified and in effect as of the date of the Business Combination Agreement. Each of the Plum Governing Documents is in full force and effect, and Plum is not in violation of any of the provisions of the Plum Governing Documents.
126
4. Amalco is the only Subsidiary of Plum. Except for Amalco, Plum does not directly or indirectly own any Equity Securities of any Person.
5. The authorized share capital of Plum consists of (i) 200,000,000 Plum Class A Shares, 1,016,833 of which are issued and outstanding, (ii) 20,000,000 Plum Class B Shares, 7,062,500 of which are issued and outstanding, (iii) 1,000,000 Plum Preference Shares, none of which are issued and outstanding, (iv) Plum Public Warrants exercisable for an aggregate of 9,416,666 Plum Class A Shares, (v) Plum Private Warrants exercisable for an aggregate of 288,334 Plum Class A Shares, (vi) Plum Class B Warrants exercisable for an aggregate of 2,354,167 Plum B Ordinary Shares, (vii) 865,000 Plum Private Units, all of which are issued and outstanding and (viii) 7,062,500 Plum Class B Units, all of which are issued and outstanding.
6. All Plum Securities that are issued and outstanding have been duly authorized and validly issued in compliance with applicable Laws, are fully paid and nonassessable.
7. Plum has all requisite corporate power and authority to execute and deliver the Business Combination Agreement and each Ancillary Agreement to which it is or will be a party, to perform its obligations hereunder and thereunder and to consummate the Transactions. The (a) execution and delivery by Plum of the Business Combination Agreement and the Ancillary Agreements to which it is or will be a party, (b) consummation of the Transactions and (c) performance of its obligations hereunder and thereunder has been duly and validly authorized by all necessary corporate action on the part of Plum and its directors, officers and shareholders, and no other corporate proceedings on the part of Plum are necessary to authorize the Business Combination Agreement or the consummation of the Transactions. The Business Combination Agreement and each of the Ancillary Agreements to which Plum is or will be a party constitute legal, valid and binding obligations of Plum, enforceable against Plum in accordance with their respective terms.
8. The financial statements of Plum contained in the Plum SEC Filings (the “Plum Financial Statements”) are true and correct in all material respects and present fairly the financial condition, operating results, changes in shareholders equity and cash flows of Plum as at the dates and during the periods therein indicated. Each of the Plum Financial Statements has been prepared in accordance with GAAP, Regulation S-K, and Regulation S-X, in each case, applied on a consistent basis throughout the periods indicated, and comply in all material respects with the applicable accounting requirements and with the rules and regulations of the SEC, the Exchange Act and the Securities Act.
9. Plum has established and maintains disclosure controls and procedures that are designed to provide reasonable assurances that material information relating to Plum and other material information required to be disclosed by Plum (including any fraud that involves management or other employees who have a significant role in the internal controls of Plum) is recorded, processed, summarized and reported within the time periods specified in the rules and forms of the SEC and that all such material information is accumulated and communicated to the management of Plum by others within Plum to allow timely decisions to be made regarding required disclosures and to make the certifications required under any applicable Laws.
10. Plum has established and maintains a system of internal controls over financial reporting sufficient to provide reasonable assurances that (i) transactions are executed in accordance with management’s general or specific authorizations, (ii) transactions are recorded as necessary to permit preparation of financial statements in conformity with GAAP and to maintain asset accountability, (iii) access to assets is permitted only in accordance with management’s general or specific authorizations, (iv) the recorded accountability for assets is compared with the existing assets at reasonable intervals and appropriate action is taken with respect to any differences and (v) records are maintained in reasonable detail which accurately and fairly reflect, in all material respects, its transactions and dispositions of assets.
11. As of the date of the Business Combination Agreement, Plum does not have any Indebtedness. Plum does not have any material off-balance sheet arrangements that are not disclosed in the Plum SEC Filings.
127
12. The execution and delivery by Plum of, and the performance by Plum of its obligations pursuant to, the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party will not result in, (a) any violation of, conflict with, or subject to obtaining the Plum Shareholders’ Approval and the Regulatory Approvals, require any consent under, (i) the Plum Governing Documents, or (ii) any Contract to which it is a party or by which any of its properties or assets is bound.
13. Plum is conducting its business and operations, and otherwise is, and has been since the date of its formation, in compliance with all applicable Laws.
14. Plum has obtained, and is in compliance in all material respects with, all Permits required by applicable Laws necessary to conduct its business as currently conducted.
15. Since the date of the most recent Plum Financial Statements, (a) there has not been, individually or in the aggregate, any Plum Material Adverse Effect, and (b) Plum has conducted its business in all material respects in the Ordinary Course.
16. There are no Actions pending or threatened against Plum or any of its assets or properties, and no written notice of any such Action involving or relating to Plum, whether pending or threatened, has been received by Plum or any of its Representatives.
17. No consent, approval or authorization of, or registration, qualification, designation, declaration or filing with, or notification to, or expiration or termination of a waiting period imposed by, any Governmental Authority on the part of Plum is required in connection with the execution and delivery of the Business Combination Agreement or any Ancillary Agreement to which Plum is or will be a party or the consummation of the Transactions, except as expressly contemplated by the Business Combination Agreement.
18. No broker, finder, agent or similar intermediary has acted on behalf of Plum or Amalco in each case, in connection with the Business Combination Agreement or the consummation of any of the Transactions
19. Plum: (i) has filed all material Tax Returns required to be filed by it, and all such filed Tax Returns are complete and accurate in all material respects; (ii) has timely paid all material Taxes on such filed Tax Returns and any other material Taxes that Plum is otherwise obligated to pay; (iii) with respect to all material Tax Returns filed by it, has not waived any statute of limitations with respect to material Taxes or agreed to any extension of time with respect to a material Tax assessment or deficiency; and (iv) does not have any deficiency, audit, examination, investigation or other proceeding in respect of material Taxes or Tax matters pending or proposed or threatened in writing, for a Tax period which the statute of limitations for assessments remains open.
20. Plum and the Plum Board have taken all action necessary so that the Business Combination Agreement and the Transactions are exempted from the restrictions on business combinations and voting requirements contained in any Takeover Statute applicable to Plum.
21. None of the information supplied or to be supplied by or on behalf of Plum or Amalco for inclusion in documents to be filed in connection with the Business Combination Agreement, will contain any untrue statement of a material fact or omit to state a material fact required to be stated therein or necessary to make the statements contained therein, in light of the circumstances under which they are made, not misleading.
22. Plum has timely filed or furnished all statements, prospectuses, registration statements, forms, certifications, schedules, exhibits, reports and documents required to be filed or furnished by it with the SEC (collectively, as they have been amended or supplemented since the time of their filing through the date that is two Business Days prior to the date of the Business Combination Agreement, the “Plum SEC Filings”). Each Plum SEC Filing, as of the date of its filing, and as of the date of any amendment or supplement thereto, complied in all material respects with the requirements of the Securities Act, the Exchange Act and the Sarbanes-Oxley Act applicable to such Plum SEC Filing. As of the date of its filing (or if amended or superseded by a filing, the initial filing), each Plum SEC Filing did not contain any untrue statement of a material fact or omit to state any material fact required to be stated therein or necessary in order to make the statements made therein, in light of the circumstances under which they were made, not misleading.
128
23. Plum is in compliance with the applicable Nasdaq or OTC Pink, as applicable, rules and regulations.
24. As of the date of the Business Combination Agreement, Plum has at least $25,193,578.08 in the Trust Account, such monies invested in U.S. government securities or money market funds meeting certain conditions under Rule 2a-7 promulgated under the Investment TRC Act pursuant to the Investment Management Trust Agreement, dated as of July 27, 2021, between Plum and Continental Stock Transfer & Trust TRC, as trustee (the “Trustee,” and such Investment Management Trust Agreement, the “Trust Agreement”).
25. Plum is not an “investment company” or a Person directly or indirectly “controlled” by or acting on behalf of an “investment company”, in each case within the meaning of the Investment TRC Act. Plum constitutes an “emerging growth company” within the meaning of the JOBS Act. Plum is a “trade agreement investor” and is not a “state-owned enterprise” as such terms are defined in the ICA.
26. Since its incorporation, Plum has not conducted any business activities other than activities (i) in connection with or incident or related to its incorporation or continuing corporate existence, (ii) those that are administrative, ministerial or otherwise immaterial in nature, (iii) related to the Plum IPO, or (iv) directed toward the accomplishment of a Business Combination.
27. As of the date of the Business Combination Agreement, Plum Class A Shares, Plum Public Warrants, and Plum Public Units are each registered pursuant to Section 12(b) of the Exchange Act and are listed for trading on Nasdaq under the symbols “PLMJ”, “PLMJW” and “PLMJU” respectively.
28. The Plum Board (including any required committee or subgroup of such board) has, as of the date of the Business Combination Agreement, unanimously (a) declared the advisability of the Transactions, (b) determined that the Transactions are fair to and in the best interests of the Plum Shareholders, (c) determined that the Transactions constitute a Business Combination, and (d) recommended that the Plum Shareholders approve the Plum Shareholder Proposals. The Plum Shareholders’ Approval represents the only approval of the holders of any Equity Securities of Plum necessary in connection with the entry into the Business Combination Agreement by Plum and the consummation of the Transactions.
29. The PIPE Subscription Agreements will be, upon execution thereof, legal, valid and binding obligations of Plum and the PIPE Investor party to each such PIPE Subscription Agreement.
30. Except with respect to actions expressly contemplated by the Business Combination Agreement or any of the Ancillary Agreements no Plum Related Party is a party to a contract with Plum.
31. Amalco is a corporation duly organized, validly existing and in good standing under the Laws of the Province of British Columbia. Each of the Amalco Governing Documents is in full force and effect, and Amalco is not in violation of any of the provisions of the Amalco Governing Documents.
32. Amalco has all requisite corporate power and authority to execute and deliver the Business Combination Agreement and each Ancillary Agreement to which it is or will be a party, to perform its obligations hereunder and thereunder and to consummate the Transactions. The (a) execution and delivery by Amalco of the Business Combination Agreement and the Ancillary Agreements to which it is or will be a party, (b) consummation of the Transactions and (c) performance of its obligations hereunder and thereunder has been duly and validly authorized by all necessary corporate action on the part of Amalco and its directors, officers and shareholders. The Business Combination Agreement and each of the Ancillary Agreements constitute valid and binding obligations of Amalco, enforceable against Amalco in accordance with their respective terms.
33. The execution and delivery by Amalco of, and the performance by Amalco of its obligations pursuant to, the Business Combination Agreement and each of the Ancillary Agreements will not result in any violation of, conflict with, or subject to obtaining the Amalco Sole Shareholder Approval and the Regulatory Approvals, require any consent, filing, notice, waiver or approval or constitute a default under, (i) the Amalco Governing Documents or (ii) any Contract to which it is a party or by which any of its properties or assets is bound.
129
34. No consent, approval or authorization of, or registration, qualification, designation, declaration or filing with, or notification to, or the expiration or termination of a waiting period imposed by, any Governmental Authority on the part of Amalco is required in connection with the execution and delivery of the Business Combination Agreement or any Ancillary Agreement to which Amalco is or will be a party or the consummation of the Transactions, except for those set forth in the Business Combination Agreement.
35. The Amalco Board has, as of the date of the Business Combination Agreement, unanimously (i) determined that it is fair to, advisable for and in the best interests of Amalco and Plum, as the sole shareholder of Amalco, for Amalco to enter into the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and to consummate the Transactions, (ii) approved the execution and delivery of the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and (iii) recommended that Plum, as the sole shareholder of Amalco, approve the Transactions, on the terms and subject to the conditions set forth in the Business Combination Agreement.
Representations and Warranties of PubCo
1. PubCo is a corporation duly organized, validly existing and in good standing under the Laws of the Province of British Columbia. Each of the PubCo Governing Documents is in full force and effect, and PubCo is not in violation of any of the provisions of the PubCo Governing Documents.
2. PubCo does not directly or indirectly own any Equity Securities of any Person.
3. The authorized share capital of PubCo consists of an unlimited number of PubCo Common Shares (the “PubCo Shares”).
4. PubCo has all requisite corporate power and authority to execute and deliver the Business Combination Agreement and each Ancillary Agreement to which it is or will be a party, to perform its obligations hereunder and thereunder and to consummate the Transactions.
5. The (a) execution and delivery by PubCo of the Business Combination Agreement and the Ancillary Agreements to which it is or will be a party, (b) consummation of the Transactions and (c) performance of its obligations hereunder and thereunder has been duly and validly authorized by all necessary corporate action on the part of PubCo and its directors, officers and shareholders.
6. The Business Combination Agreement and each of the Ancillary Agreements to which PubCo is or will be a party constitute or will constitute at the Closing valid and binding obligations of PubCo, enforceable against PubCo in accordance with their respective terms.
7. The execution and delivery by PubCo of, and the performance by PubCo of its obligations pursuant to, the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party will not result in (a) any violation of, conflict with, require any consent, filing, notice, waiver or approval or constitute a default under, (i) the PubCo Governing Documents, (ii) any Contract to which it is a party or by which any of its properties or assets is bound or (iii) any applicable Law, Permit or Governmental Order.
8. PubCo is conducting its business and operations, and otherwise is, and has been since the date of its formation, in compliance with all applicable Laws.
9. PubCo has obtained, and is in compliance in all material respects with, all Permits required by applicable Laws necessary to conduct its business as currently conducted.
10. Since the date of its formation, (a) there has not been, individually or in the aggregate, any Plum Material Adverse Effect, and (b) PubCo has not conducted any business.
11. There are no Actions pending or threatened against PubCo or any of its assets or properties.
12. No consent, approval or authorization of, or registration, qualification, designation, declaration or filing with, or notification to, or expiration or termination of a waiting period imposed by, any Governmental Authority on the part of PubCo is required in connection with the execution and delivery of the Business Combination Agreement or any Ancillary Agreement to which PubCo is or will be a party or the consummation of the Transactions, except for those disclosed in the Business Combination Agreement.
130
13. No broker, finder, agent or similar intermediary has acted on behalf of PubCo, and PubCo has not incurred, directly or indirectly, as a result of any action taken by or on behalf of PubCo, any liability for any brokerage or finders’ fees or agents’ commissions or any similar charges, in each case, in connection with the Business Combination Agreement or the consummation of any of the Transactions.
14. None of the information supplied or to be supplied by or on behalf of PubCo for inclusion or incorporation by reference in any public filing in connection with the Business Combination Agreement will, when filed, made available, mailed or distributed, as the case may be, contain any untrue statement of a material fact or omit to state a material fact required to be stated therein or necessary to make the statements contained therein, in light of the circumstances under which they are made, not misleading.
15. PubCo is not an “investment company” or a Person directly or indirectly “controlled” by or acting on behalf of an “investment company”, in each case within the meaning of the Investment TRC Act. PubCo constitutes an “emerging growth company” within the meaning of the JOBS Act. PubCo is a “trade agreement investor” and is not a “state-owned enterprise” as such terms are defined in the ICA.
16. PubCo was formed solely for the purpose of engaging in the Transactions, and PubCo has not engaged in any other business or activities since its formation.
17. The PubCo Board unanimously (a) determined that it is fair to, advisable for and in the best interests of PubCo and the PubCo Sole Shareholder for PubCo to enter into the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and to consummate the Transactions, (b) approved the execution and delivery of the Business Combination Agreement and each of the Ancillary Agreements to which it is or will be a party and (c) recommended that the PubCo Sole Shareholder approve the Transactions, on the terms and subject to the conditions set forth in the Business Combination Agreement.
18. The PIPE Subscription Agreements will be, upon execution thereof, legal, valid and binding obligations of PubCo and the PIPE Investor party to each such PIPE Subscription Agreement.
Covenants of the Parties
The Business Combination Agreement contains a number of covenants made by TRC, Plum, Amalco and PubCo which in certain cases are subject to specified exceptions and qualifications contained in the Business Combination Agreement.
TRC Conduct of Business.
Except (i) as contemplated by the Business Combination Agreement, any of the Ancillary Agreements or the Plan of Arrangement, (ii) as required by applicable Law or Governmental Order, or (iii) as consented to by Plum in writing, from the date of the Business Combination Agreement through the earlier of the Closing or the termination of the Business Combination Agreement (the “Interim Period”), TRC shall use its commercially reasonable efforts to operate its business in the Ordinary Course, and shall not:
• change or amend TRC Governing Documents;
• make or declare any dividend or distribution in respect of its Equity Securities;
• split, combine, reclassify or otherwise amend any terms of any of its Equity Securities;
• purchase, repurchase, redeem or otherwise acquire any of its issued and outstanding Equity Securities;
• reduce the stated capital of TRC Common Shares;
• sell, assign, transfer, convey, exclusively license, lease or otherwise dispose of any material assets or properties of TRC;
• acquire any ownership interest in any real property;
• (A) merge, amalgamate or consolidate with or into, or acquire any other Person with a fair market value in excess of $2,500,000 in any individual transaction or $5,000,000 in the aggregate, or (B) be acquired by any other Person;
131
• engage in any new business line that is inconsistent with TRC’s business as currently conducted or proposed to be conducted;
• make any material changes to TRC’s accounting policies, principles, methods, practices or procedures;
• (A) make, change or revoke any material election in respect of Taxes, or settle or compromise any material Canadian Tax liability or material U.S. federal, state, local or non-U.S. Tax liability, except in the Ordinary Course, (B) change any annual Tax accounting period, adopt or change any method of Tax accounting, amend any Tax Return or file any claim for a Tax refunds, enter into any closing agreement, waive or extend any statute of limitations period in respect of an amount of Taxes, settle any Tax claim, audit or assessment or surrender any right to claim a Tax refund, offset or other reduction in Tax liability, (C) incur any liability for Taxes other than in the Ordinary Course, (D) prepare any Tax Return in a manner inconsistent with past practice, (E) enter into a Tax allocation agreement, Tax sharing agreement or Tax indemnity agreement or (F) grant any power of attorney relating to any Tax matter;
• issue, sell, pledge, dispose of, grant or encumber, or authorize the issuance, sale, pledge, disposition, grant or encumbrance of, any of its Equity Securities, other than the consummation of one or more financing transactions prior to TRC Amalgamation Effective Time pursuant to which Equity Securities of TRC are sold in an amount not to exceed, in the aggregate, $10,000,000 (each, a “Permitted Financing”);
• adopt a plan of, or otherwise enter into or effect a, complete or partial liquidation, dissolution, restructuring, recapitalization or other reorganization, or file for bankruptcy or otherwise wind-up its operations;
• waive, release, settle, compromise or otherwise resolve any Action;
• incur, assume or guarantee any Indebtedness, the principal amount of which exceeds $1,000,000 in the aggregate;
• enter into any interest rate, currency, equity or commodity swaps, hedges, forward sales contracts or similar transactions;
• (A) enter into any joint venture or similar agreement, arrangement or relationship or (B) enter into any Contract providing any Person control over management of the operations of TRC or the appointment of governing bodies of TRC;
• enter into, renew or amend in any material respect (A) any transaction or Contract with an Affiliate of TRC, (B) any Contract with any broker, finder, investment banker or financial advisor with respect to any of the Transactions, or (C) any Contract that would have been required to be disclosed in the TRC Disclosure Schedules;
• (A) enter into, renew or amend the material terms of any employment agreement with any executive officers of TRC, (B) hire any new employees holding an executive position or (C) transfer or terminate the employment or engagement of any employee holding an executive position other than any such termination for cause;
• adopt, enter into or incur any liability with respect to any TRC Benefit Plan;
• make any loans, advances or capital contributions to, or investments in, any other Person;
• (A) voluntarily fail to maintain or cancel any material Insurance Policy or (B) voluntarily materially and adversely change coverage under any material Insurance Policy;
• voluntarily fail to maintain in full force and effect, or to comply in all material respects with the requirements of, any Permit that is material to the conduct of the business of TRC as currently conducted; or
• enter into any Contract or otherwise make any binding commitment to take any action prohibited by the Business Combination Agreement.
132
During the Interim Period, TRC shall (a) use commercially reasonable efforts to maintain and preserve intact its business organization and business relationships and keep available the services of its officers and independent contractors as a group and (b) comply in all material respects with, and continue performing under, as applicable, TRC Governing Documents and all Material Contracts to which it is a party.
PCAOB Audited Financials.
TRC shall deliver to PubCo the following financial statements prepared in accordance with GAAP and Regulation S-X: (a) the audited balance sheet of TRC as at July 31, 2023, and the related audited statements of comprehensive income (loss), changes in shareholders’ equity and cash flows for the year then ended, audited in accordance with PCAOB standards and including the report therefor prepared by TRC’s independent auditor, and (b) the audited balance sheet of TRC as at July 31, 2024, and the related audited statements of comprehensive income (loss), changes in shareholders’ equity and cash flows for the year then ended, audited in accordance with PCAOB standards and including the report therefor prepared by TRC’s independent auditor.
TRC Public Filings.
During the Interim Period, TRC shall keep current and timely file all of the forms, reports, schedules, statements and other documents required to be filed by TRC with the CSA and otherwise comply in all material respects with applicable securities Laws (the “Additional TRC CSA Filings”). TRC shall use commercially reasonable efforts to ensure that all Additional TRC CSA Filings (i) shall be prepared in all material respects in accordance with the requirements of applicable Law and (ii) shall not contain any untrue statement of a material fact or fail to state any material fact required to be stated therein or necessary in order to make the statements therein, in light of the circumstances under which they were made, not misleading.
Covenants of Plum
Trust Account Payments.
In connection with Closing, Plum shall (i) cause any documents, opinions and notices required to be delivered to the Trustee pursuant to the Trust Agreement to be so delivered prior to or at the Closing and (ii) use its reasonable best efforts to cause the Trustee to (A) pay as and when due all amounts payable to Plum Shareholders pursuant to any Plum Share Redemptions and (B) thereafter disburse all remaining amounts then held in the Trust Account as directed by Plum.
Plum Nasdaq or OTC Market Listing.
From the date of the Business Combination Agreement until the Closing, Plum shall use commercially reasonable efforts to ensure that the Plum Class A Shares, the Plum Public Warrants and the Plum Public Units remain qualified on Nasdaq or OTC Markets, as applicable.
Plum Conduct of Business.
Except (i) as contemplated by the Business Combination Agreement or any of the Ancillary Agreements, (ii) as required by applicable Law or Governmental Order, or (iii) as consented to by TRC in writing, during the Interim Period, Plum shall use its commercially reasonable efforts to operate its business in the Ordinary Course and shall not:
• change, modify or amend the Trust Agreement or the Plum Governing Documents;
• change, modify or amend the Plum Warrant Agreement;
• make or declare any dividend or distribution in respect of its Equity Securities;
• split, combine, reclassify or otherwise amend any terms of any of its Equity Securities;
• purchase, repurchase, redeem or otherwise acquire any of its issued and outstanding Equity Securities, except for Plum Share Redemptions;
133
• reduce the stated capital of any of the Plum Shares;
• acquire any ownership interest in any real property;
• (A) merge, consolidate or amalgamate with or into, or acquire any other Person, or (B) be acquired by any other Person;
• make any material changes to Plum’s accounting policies, principles, methods, practices or procedures, except (A) as disclosed in the Plum SEC Filings or (B) as required by applicable Laws or GAAP;
• (A) make, change or revoke any material election in respect of Taxes, or settle or compromise any material Canadian Tax liability or material U.S. federal, state, local or non-U.S. Tax liability, (B) change any annual Tax accounting period, adopt or change any method of Tax accounting, amend any Tax Return or file any claim for a Tax refund, enter into any closing agreement, waive or extend any statute of limitations period in respect of an amount of Taxes, settle any Tax claim, audit or assessment or surrender any right to claim a Tax refund, offset or other reduction in Tax liability, (C) incur any liability for Taxes other than in the Ordinary Course, (D) prepare any Tax Return in a manner inconsistent with past practice, (E) enter into a Tax allocation agreement, Tax sharing agreement or Tax indemnity agreement or (F) grant any power of attorney relating to any Tax matter;
• issue, sell, pledge, dispose of, grant or encumber, or authorize the issuance, sale, pledge, disposition, grant or encumbrance of, any Equity Securities;
• adopt a plan of, or otherwise enter into or effect a, complete or partial liquidation, dissolution, restructuring, recapitalization or other reorganization, or file for bankruptcy or otherwise wind-up its operations;
• waive, release, settle, compromise or otherwise resolve any Action;
• incur, assume or guarantee any Indebtedness, except for a loan from Sponsor or an Affiliate thereof or certain of Plum’s officers and directors to finance the Plum Transaction Expenses;
• enter into any interest rate, currency, equity or commodity swaps, hedges, forward sales contracts or similar transactions;
• (A) enter into any joint venture or similar agreement, arrangement or relationship or (B) enter into any Contract providing any Person control over management of the operations of Plum or the appointment of governing bodies of Plum;
• enter into, renew or amend in any material respect, (A) any transaction or Contract with an Affiliate of Plum, other than with respect to Indebtedness expressly permitted, that would require disclosure of such transaction or Contract under Item 404 of Regulation S-K or (B) any Contract with any broker, finder, investment banker or financial advisor with respect to any of the Transactions;
• (A) hire any person, (B) grant any increase in the compensation of any current or former officer or director, (C) adopt any benefit plan for the benefit of any current or former officer or director, or (D) amend in any material respect any existing agreement with any current or former officer or director;
• make any loans, advances or capital contributions to, or investments in, any other Person; or
• enter into any Contract or otherwise make any binding commitment to take any action prohibited by the Business Combination Agreement.
During the Interim Period, Plum shall (a) use commercially reasonable efforts to maintain and preserve intact its business organization and business relationships and keep available the services of its officers and independent contractors as a group and (b) comply in all material respects with, and continue performing under, as applicable, the Plum Governing Documents, the Trust Agreement and all other material Contracts to which it is a party.
134
Plum Public Filings.
During the Interim Period, Plum shall keep current and timely file all of the forms, reports, schedules, statements and other documents required to be filed by Plum with the SEC and otherwise comply in all material respects with applicable securities Laws (the “Additional Plum SEC Filings”). Plum shall use commercially reasonable efforts to ensure that all Additional Plum SEC Filings (i) shall be prepared in all material respects in accordance with the requirements of the Securities Act, the Exchange Act and the Sarbanes-Oxley Act and (ii) shall not contain any untrue statement of a material fact or fail to state any material fact required to be stated therein or necessary in order to make the statements therein, in light of the circumstances under which they were made, not misleading.
Section 16 Matters.
Plum shall take all reasonable steps as may be required or permitted to cause any acquisition or disposition of the Beneficial Ownership of any Plum Securities that occurs or is deemed to occur by reason of or pursuant to the Transactions by each individual who is or will be subject to the reporting requirements of Section 16(a) of the Exchange Act with respect to Plum to be exempt under Rule 16b-3 promulgated under the Exchange Act.
Domestication.
Plum shall take all actions necessary to cause the Domestication to become effective in accordance with the applicable provisions of the BCBCA and the Companies Act
Non-Survival of Representations, Warranties and Covenants
None of the representations, warranties, covenants, obligations or other agreements in the Business Combination Agreement or in any certificate, statement or instrument delivered pursuant to the Business Combination Agreement, including any rights arising out of any breach of such, shall survive the Closing, and all of the representations, warranties, covenants, obligations or other agreements in the Business Combination Agreement or in any certificate, statement or instrument delivered pursuant to the Business Combination Agreement, including any rights arising out of any breach of such representations, warranties, covenants, obligations, agreements or other provisions, shall terminate and expire upon the occurrence of the Closing (and there shall be no liability after the Closing in respect thereof), in each case, except for those covenants and agreements contained herein that by their terms expressly apply in whole or in part at or after the Closing and then only with respect to any breaches occurring at or after the Closing.
Additional Covenants of the Parties
Regulatory Approvals; Other Filings.
Each of TRC and Plum shall cooperate in good faith with any Governmental Authority to obtain any required approvals or consents in order to complete lawfully the Transactions prior to the Agreement End Date TRC shall promptly furnish to Plum, and Plum shall promptly furnish to TRC, copies of any notices or written communications received by such Party from any Governmental Authority with respect to the Transactions, and each such Party shall permit the other Party reasonable opportunity to review in advance any proposed written communications by such Party or its Affiliates to any Governmental Authority concerning the Transactions.
Proxy/Registration Statement.
As promptly as reasonably practicable, Plum and TRC shall prepare, and PubCo and TRC shall file with the SEC, a proxy/registration statement on Form F-4 (the “proxy/registration statement”) relating to the Plum Shareholders Meeting (A) in connection with the registration under the Securities Act of the PubCo Common Shares to be issued to the Plum Shareholders and TRC Shareholders pursuant to the Business Combination Agreement, (B) to provide the Plum Public Shareholders an opportunity to have their Plum Class A Shares redeemed and (C) to solicit proxies from Plum Shareholders for the approval and adoption of (1) the Business Combination Agreement, the Arrangement and the other Transactions, including the Domestication, (2) the issuance of PubCo Common Shares in connection with the Transactions, including the PIPE Investment, (3) the Plum Domestication Articles and the Closing PubCo Articles, (4) the Incentive Plan, (5) any other proposals as the SEC may indicate are necessary in its comments to the proxy/registration statement or correspondence related thereto, (6) any other proposals
135
as mutually determined by Plum and TRC to be necessary or appropriate in connection with the Transactions and (7) adjournment of the Plum Shareholders Meeting, if necessary, to permit further solicitation of proxies because there are not sufficient votes to approve and adopt any of the foregoing (such proposals in (1) through (7), collectively, the “Plum Shareholder Proposals”).
The proxy/registration statement shall also be used (A) in connection with the registration under the Securities Act of the PubCo Common Shares to be issued to TRC Shareholders pursuant to the Business Combination Agreement and (B) in conjunction with TRC Information Circular to solicit proxies from TRC Shareholders at TRC Shareholders Meeting for the approval and adoption of (1) the Business Combination Agreement, the Arrangement and the other Transactions, (2) the Incentive Plan, (3) any other proposals as the SEC may indicate are necessary in its comments to the proxy/registration statement or correspondence related thereto, (4) any other proposals as mutually determined by Plum and TRC to be necessary or appropriate in connection with the Transactions and (5) adjournment of TRC Shareholders Meeting, if necessary, to permit further solicitation of proxies because there are not sufficient votes to approve and adopt any of the foregoing (such proposals in (1) through (5), collectively, the “TRC Shareholder Proposals”).
Each Party shall furnish all information concerning such Party as any of the other Parties may reasonably request in connection with the preparation of the proxy/registration statement. Each Party shall use commercially reasonable efforts to (A) cause the proxy/registration statement to comply with all applicable rules and regulations promulgated by the SEC and (B) respond as promptly as reasonably practicable to all comments received from the SEC.
After the proxy/registration statement is declared effective by the SEC, Plum shall mail (or cause to be mailed) the proxy/registration statement to the Plum Shareholders. (A) TRC, on the one hand, and Plum, on the other hand, shall each be responsible for and pay 50% of any and all filing fees payable to the SEC in connection with the proxy/registration statement, and (B) Plum shall be responsible for and pay all fees, costs and expenses for the preparation and mailing of the proxy/registration statement.
Plum Shareholders’ Approval and Plum Board Recommendation.
Plum shall (A) solicit from the Plum Shareholders proxies in favor of the approval and adoption of the Business Combination Agreement and the Plum Shareholder Proposals, including the Plum Shareholders’ Approval, and shall take all other action necessary or advisable to obtain such proxies and the Plum Shareholders’ Approval and (B) obtain the vote or consent of the Plum Shareholders required by and in compliance with all applicable Laws, Nasdaq rules and the Plum Governing Documents; provided, that, subject to the terms of the Sponsor Support Agreement, none of Plum, Sponsor or any of their Affiliates shall be required to pay any additional consideration to any Plum Shareholder in order to obtain the Plum Shareholders’ Approval.
The proxy/registration statement shall include a statement to the effect that the Plum Board has unanimously recommended that the Plum Shareholders vote in favor of the Plum Shareholder Proposals at the Plum Shareholders Meeting (such statement, the “Plum Board Recommendation”), and, except as provided in the Business Combination Agreement, neither the Plum Board nor any committee thereof shall withhold, withdraw, qualify, amend or modify, or publicly propose or resolve to withhold, withdraw, qualify, amend or modify, the Plum Board Recommendation (a “Plum Modification in Recommendation”).
The Plum Board may, at any time prior to, but not after, obtaining the Plum Shareholders’ Approval, make a Plum Modification in Recommendation solely in response to a Plum Intervening Event (a “Plum Intervening Event Change in Recommendation”) if the Plum Board determines in good faith, after consultation with outside legal counsel, that the failure to take such action would be a breach of the fiduciary duties of the Plum Board under applicable Law; provided, that (A) Plum shall have delivered written notice to TRC of the Plum Board’s intention to make a Plum Intervening Event Change in Recommendation at least five Business Days prior to the taking of such action by the Plum Board (the “Plum Intervening Event Notice Period”), (B) during the Plum Intervening Event Notice Period and prior to making a Plum Intervening Event Change in Recommendation, if requested by TRC, Plum and its Representatives shall have negotiated in good faith with TRC and its Representatives regarding any revisions or adjustments proposed by TRC to the terms and conditions of the Business Combination Agreement as would enable the Plum Board to proceed with the Plum Board Recommendation and not make such Plum Intervening Event Change in Recommendation and (C) if TRC requested negotiations in accordance with clause (B), the Plum Board may make a Plum Intervening Event Change in Recommendation only if the Plum Board, after
136
considering in good faith any revisions or adjustments to the terms and conditions of the Business Combination Agreement that TRC shall have, prior to the expiration of the Plum Intervening Event Notice Period, proposed in writing, continues to determine in good faith, after consultation with outside legal counsel, and reaffirms in writing to TRC on the date on which the Plum Intervening Event Notice Period expires, that failure to make a Plum Intervening Event Change in Recommendation would be a breach of its fiduciary duties to the Plum Shareholders under applicable Law.
A “Plum Intervening Event” shall mean any Event that (A) has had, or would reasonably be expected to have, individually or in the aggregate, a TRC Material Adverse Effect, (B) was not known and was not reasonably foreseeable to the Plum Board as of the date of the Business Combination Agreement and that becomes known to the Plum Board prior to obtaining the Plum Shareholders’ Approval and (C) does not relate to and excludes, whether alone or in combination, (1) any Acquisition Proposal (solely with respect to Plum), (2) any change in the price or trading volume of the Plum Class A Shares, the Plum Public Warrants or the Plum Units, (3) any Action filed or threatened against Plum or any member of the Plum Board arising out of or related to the Transactions by a Person other than a Governmental Authority that was not known by, or the consequences of which were not reasonably foreseeable to, the Plum Board as of the date of the Business Combination Agreement and that becomes known to the Plum Board prior to obtaining the Plum Shareholders’ Approval, (4) any action expressly required by, or required to be taken by a Party in order to comply with its obligations under the Business Combination Agreement, any Ancillary Agreement or the Plan of Arrangement or (5) the timing of any approval or clearance of any Governmental Authority required for the consummation of the Transactions, including any of the Regulatory Approvals.
TRC Shareholders’ Approval and TRC Board Recommendation.
Prior to or as promptly as practicable after the proxy/registration statement is declared effective under the Securities Act and as provided by the Interim Order, TRC shall establish a record date for, duly call, give notice of and convene and hold TRC Shareholders Meeting for the purpose of voting on TRC Shareholder Proposals and obtaining TRC Shareholders’ Approval and such other matters as may be mutually agreed by Plum and TRC. TRC shall use its commercially reasonable efforts to (A) solicit from TRC Shareholders proxies in favor of the approval and adoption of the Business Combination Agreement and TRC Shareholder Proposals and (B) obtain the vote or consent of TRC Shareholders required by and in compliance with all applicable Laws, CSA rules and TRC Governing Documents; provided, that none of TRC or any of its Affiliates shall be required to pay any additional consideration to any TRC Shareholder in order to obtain TRC Shareholders’ Approval.
TRC Information Circular shall include a statement to the effect that TRC Board has unanimously recommended that TRC Shareholders vote in favor of TRC Shareholder Proposals at TRC Shareholders Meeting (such statement, the “TRC Board Recommendation”), and, except as provided in the Business Combination Agreement, TRC Board shall not withhold, withdraw, qualify, amend or modify, or publicly propose or resolve to withhold, withdraw, qualify, amend or modify, TRC Board Recommendation (a “TRC Modification in Recommendation”).
TRC Board may, at any time prior to, but not after, obtaining TRC Shareholders’ Approval, make a TRC Modification in Recommendation (a “TRC Change in Recommendation”) in response to (A) an Acquisition Proposal, if TRC Board determines in good faith, after consultation with outside legal counsel, that (1) the failure to take such action would be a breach of the fiduciary duties of TRC Board under applicable Law and (2) such Acquisition Proposal constitutes a TRC Superior Proposal, or (B) a TRC Intervening Event if TRC Board determines in good faith, after consultation with outside legal counsel, that the failure to take such action would be a breach of the fiduciary duties of TRC Board under applicable Law; provided, that, in the case of each of clauses (A) and (B), (x) TRC shall have delivered written notice to Plum of TRC Board’s intention to make a TRC Change in Recommendation at least five Business Days prior to the taking of such action by TRC Board (the “TRC Change in Recommendation Notice Period”) (y) during TRC Change in Recommendation Notice Period and prior to making a TRC Change in Recommendation, if requested by Plum, TRC and its Representatives shall have negotiated in good faith with Plum and its Representatives regarding any revisions or adjustments proposed by Plum to the terms and conditions of the Business Combination Agreement as would enable TRC Board to proceed with TRC Board Recommendation and not make such TRC Change in Recommendation and (z) if Plum requested negotiations in accordance with clause (y), TRC Board may make a TRC Change in Recommendation only if TRC Board, after considering in good faith any revisions or adjustments to the terms and conditions of the Business Combination Agreement that Plum shall have, prior to the expiration of TRC Change in Recommendation Notice Period, proposed
137
in writing, continues to determine in good faith, after consultation with outside legal counsel, and reaffirms in writing to Plum on the date on which TRC Change in Recommendation Notice Period expires, that such Acquisition Proposal continues to constitute a TRC Superior Proposal or that such TRC Intervening Event still exists.
A “TRC Superior Proposal” shall mean a bona fide Acquisition Proposal with respect to TRC that the TRC Board, after consultation with outside legal counsel, determines in good faith would result in a transaction that is more favorable to TRC and TRC Shareholders than the Transactions after taking into account all such factors and matters deemed relevant in good faith by TRC Board, including legal, financial (including the financing terms of any such Acquisition Proposal), regulatory, timing or other aspects of such Acquisition Proposal and the Transactions and after taking into account any changes to the terms of the Business Combination Agreement irrevocably offered in writing by Plum in response to such TRC Superior Proposal.
A “TRC Intervening Event” shall mean any Event (A) materially effecting the business, assets, operations or condition (financial or otherwise) of TRC that (B) was not known and was not reasonably foreseeable to TRC Board as of the date of the Business Combination Agreement and that becomes known to TRC Board prior to obtaining TRC Shareholders’ Approval and (C) does not relate to and excludes, whether alone or in combination, (1) any Acquisition Proposal (solely with respect to TRC), (2) any change in the price or trading volume of TRC Common Shares, (3) any Action filed or threatened against TRC or any member of TRC Board arising out of or related to the Transactions by a Person other than a Governmental Authority that was not known by, or the consequences of which were not reasonably foreseeable to, TRC Board as of the date of the Business Combination Agreement and that becomes known to TRC Board prior to obtaining TRC Shareholders’ Approval, (4) any action expressly required by, or required to be taken by a Party in order to comply with its obligations under the Business Combination Agreement, any Ancillary Agreement or the Plan of Arrangement or (5) the timing of any approval or clearance of any Governmental Authority required for the consummation of the Transactions, including any of the Regulatory Approvals.
Support of Transactions.
Each of the parties shall promptly notify the other parties in writing of any material filings, actions, suits, claims, investigations or proceedings commenced or threated against, related to or involving such party that relate to the Business Combination Agreement or the Transactions. Each of Plum and TRC shall use its reasonable best efforts to take or cause to be taken all actions and to do or cause to be done all things necessary, proper or advisable under applicable Law to consummate and make effective the Transactions as soon as reasonably practicable.
During the Interim Period, Plum shall use its commercially reasonable efforts to cause Plum Shareholders not to elect to effect a Plum Share Redemption or to unwind any such elections.
Tax Matters.
The Business Combination Agreement and the Plan of Arrangement are intended to constitute, and the Parties hereto hereby adopt the Business Combination Agreement and the Plan of Arrangement as, a “plan of reorganization” within the meaning of Treasury Regulations Sections 1.368-2(g) and 1.368-3(a). Each of the Parties shall use its reasonable best efforts to: (a) cause the Transactions to qualify for the Intended Tax Treatment; (b) not take or fail to take any action, or become obligated to take or fail to take any action, which action or failure could reasonably be expected to prevent or impede the Transactions from qualifying for the Intended Tax Treatment; and (c) report and file all relevant Tax Returns consistent with the Intended Tax Treatment and take no position inconsistent with the Intended Tax Treatment, unless required to do so pursuant to applicable Law.
Acquisition Proposals.
During the Interim Period, each of TRC and Plum shall not, and shall cause its respective Representatives not to, directly or indirectly, except to the extent necessary to consummate the PIPE Investment or any Permitted Financing, (i) solicit any negotiations or discussions with any Person with respect to an Acquisition Proposal, (ii) enter into any acquisition agreement, merger agreement or similar definitive agreement in each case relating to an Acquisition Proposal, (iii) grant any waiver, amendment or release under any confidentiality or standstill agreement or the anti-takeover Laws of any state relating to an Acquisition Proposal, (iv) approve, endorse or recommend in writing, or publicly propose to approve, endorse or recommend, any Acquisition Proposal or (v) otherwise knowingly facilitate or knowingly encourage any inquiries, proposals, discussions or negotiations or any effort or attempt by any Person to make an Acquisition Proposal.
138
Notwithstanding anything to the contrary in the Business Combination Agreement, prior to the receipt of TRC Shareholders’ Approval, TRC Board, directly or indirectly through any Representative, may (i) participate in negotiations or discussions with any third party that has made (and not withdrawn) an Acquisition Proposal with respect to TRC that TRC Board believes in good faith, after consultation with outside legal counsel, constitutes or would reasonably be expected to result in a TRC Superior Proposal, and (ii) thereafter furnish to such third party non-public information relating to TRC pursuant to a customary confidentiality agreement.
TRC shall notify Plum promptly after receipt by TRC of any Acquisition Proposal or any request for information regarding TRC or any of its Subsidiaries or for access to the business, properties, assets, books, records, work papers or other documents of TRC by any third party that has definitively indicated that it is intending to make or will be making, or has made, an Acquisition Proposal.
D&O Indemnification and Insurance.
From and after the Closing, PubCo shall indemnify and hold harmless each present and former officer, director, manager, employee and agent of PubCo, TRC, Plum and Amalco (the “D&O Indemnified Parties”) against any costs or expenses (including reasonable attorneys’ fees), judgments, fines, losses, claims, damages or liabilities incurred in connection with any Action, whether civil, criminal, administrative or investigative, arising out of or pertaining to matters existing or occurring at or prior to the Closing, to the fullest extent that PubCo, TRC, Plum or Amalco, respectively, would have been permitted under applicable Law.
For a period of six years from and after the Closing, PubCo shall maintain in effect directors’ and officers’ liability insurance covering the D&O Indemnified Parties who are covered by PubCo’s, TRC’s, Plum’s or Amalco’s, as applicable, directors’ and officers’ liability insurance policies in effect as of the date of the Business Combination Agreement (the “Pre-Closing D&O Liability Insurance Policies”) with coverage amounts, terms and conditions not less favorable to any D&O Indemnified Parties than those of the applicable Pre-Closing D&O Liability Insurance Policies.
Incentive Plan.
Prior to the Plum Amalgamation Effective Time, subject to approval by the Plum Shareholders and TRC Shareholders and conditioned upon the occurrence of, and effective as of, the Closing Date, PubCo shall approve and adopt an equity incentive plan, in form and substance reasonably acceptable to TRC, that provides for grants of awards to employees and other service providers of PubCo and its Subsidiaries in the form of options, restricted stock, restricted stock units or other equity-based awards based on PubCo Common Shares, with the number of PubCo Common Shares initially reserved for issuance under the Incentive Plan equal to the sum of (a) 1,000,000 and (b) 10% of the total number of PubCo Common Shares outstanding immediately following the Closing (on a fully-diluted basis assuming the conversion of all securities convertible into or exercisable for PubCo Common Shares, other than the PubCo Common Shares issuable pursuant to the Share Award Agreement) (the “Incentive Plan”), which Incentive Plan shall have an annual “evergreen” increase of not more than 3% of the number of PubCo Common Shares outstanding as of the day prior to such increase.
Delisting and Deregistration
Each of the Parties shall use its commercially reasonable efforts to cause (a) the TRC Common Shares to be delisted from OTC Markets and TSX-V, and to terminate the registration of TRC with the CSA, as of the TRC Amalgamation Effective Time or as soon as practicable thereafter, and (b) the Plum Units, the Plum Class A Shares and the Plum Public Warrants to be no longer traded on Nasdaq or OTC Pink, as applicable (or be succeeded by the applicable Equity Securities of PubCo), and to terminate the registration of Plum with the SEC pursuant to Sections 12(g) and 15(d) of the Exchange Act (or be succeeded by PubCo), as of the TRC Amalgamation Effective Time or as soon as practicable thereafter.
Nasdaq Listing
During the Interim Period, each of the Parties shall use its commercially reasonable efforts to have the PubCo Common Shares and the PubCo Warrants listed on Nasdaq, effective as of the Plum Amalgamation Effective Time.
139
PubCo Conduct of Business
During the Interim Period, PubCo shall not engage in any activities other than (i) the execution of any Ancillary Agreements to which it is to be a party and (ii) the performance of its obligations under the Business Combination Agreement or the Ancillary Agreements to which it is a party in furtherance of the Transactions.
Amalco Conduct of Business
During the Interim Period, Amalco shall not engage in any activities other than (i) the execution of any Ancillary Agreements to which it is to be a party and (ii) the performance of its obligations under the Business Combination Agreement or the Ancillary Agreements to which it is a party in furtherance of the Transactions.
PubCo and Amalco Shareholder Approvals
Promptly following the execution of the Business Combination Agreement (and in any event within 24 hours therefrom), the PubCo Sole Shareholder and Plum, the sole shareholder of Amalco, shall deliver to TRC evidence, in form and substance reasonably acceptable to TRC, of the PubCo Sole Shareholder Approval and the Amalco Sole Shareholder Approval, respectively.
PIPE Investment
During the Interim Period, each of Plum and PubCo shall use their respective commercially reasonable efforts to take, or cause to be taken, and TRC shall cooperate with each of Plum and PubCo in the taking of, all actions and do, or cause to be done, all things necessary, proper or advisable to consummate the PIPE Investment concurrently with the Closing, including: (i) entering into PIPE Subscription Agreements and maintaining such PIPE Subscription Agreements in full force and effect; (ii) providing the other Parties with such information and assistance as is reasonably requested in connection with the negotiation, preparation and execution of the PIPE Subscription Agreements and the consummation of the PIPE Investment; (iii) satisfying on a timely basis all conditions and covenants applicable to such Party in the PIPE Subscription Agreements; (iv) consummating the PIPE Investment concurrently with the Closing on the terms and subject to the conditions set forth in the PIPE Subscription Agreements; and (v) causing each PIPE Investor to pay to (or as directed by) PubCo its applicable portion of the PIPE Investment Amount as set forth in the applicable PIPE Subscription Agreement. PubCo shall take all actions required under the PIPE Subscription Agreements with respect to the timely issuance and delivery of the PubCo Common Shares issuable in connection with the PIPE Investment, whether in certificate or book-entry form, as and when required under any such PIPE Subscription Agreements.
Share Award Agreements.
At the Closing, PubCo shall enter into share award agreements in substantially the form attached hereto as Annex G with each of the service providers of TRC set forth in the Business Combination Agreement (collectively, the “Share Award Agreements”) pursuant to which, among other things, PubCo shall issue to each such service provider, as consideration for providing services to TRC, an award representing the right to receive the number of PubCo Common Shares set forth opposite such service provider’s name (constituting an aggregate of 1,000,000 PubCo Common Shares) on the terms and subject to the conditions set forth in the applicable Share Award Agreement.
Post-Closing PubCo Independent Director Agreements
During the Interim Period, each of TRC and PubCo shall use their respective commercially reasonable efforts to negotiate with each of the individuals set forth in the TRC Disclosure Schedules who shall become an independent director of the PubCo Board at the Closing (each such individual, a “Post-Closing PubCo Independent Director”) an agreement, in form and substance acceptable to each of TRC, PubCo and such Post-Closing PubCo Independent Director, each acting reasonably, in respect of such Post-Closing PubCo Independent Director’s service on the PubCo Board from and after the Closing, which agreement shall be entered into by and between PubCo and such Post-Closing PubCo Independent Director at the Closing.
140
TRC RSU Vesting Acceleration.
During the Interim Period, TRC Board shall take all such actions as are reasonably required to consummate TRC RSU Vesting Acceleration.
Termination
The Business Combination Agreement may be terminated and the Transactions abandoned at any time prior to the Closing as follows:
• by mutual written consent of TRC and Plum;
• by written notice from TRC or Plum if the Closing shall not have occurred by July 30, 2025 (the “Agreement End Date”);
• by written notice from TRC or Plum if any Governmental Authority shall have enacted any Governmental Order that has the effect of making consummation of the Transactions illegal;
• by written notice from TRC to Plum if, prior to obtaining the Plum Shareholders’ Approval, there has been a Plum Modification in Recommendation;
• by written notice from Plum to TRC if, prior to obtaining TRC Shareholders’ Approval, there has been a TRC Modification in Recommendation;
• by written notice from TRC or Plum if the Plum Shareholders’ Approval is not obtained at the Plum Shareholders Meeting;
• by written notice from TRC to Plum at any time prior to receipt of TRC Shareholders’ Approval in connection with a TRC Superior Proposal or a TRC Intervening Event;
• by written notice from TRC or Plum if the TRC Shareholders’ Approval shall not have been obtained at TRC Shareholders Meeting;
• by written notice from Plum to TRC if (i) there is any breach of any representation, warranty or covenant of TRC such that any condition to closing would not be satisfied at the Closing, subject to a 30-day period to cure and (ii) Plum is not in material breach of its representations, warranties or covenants under the Business Combination Agreement; or
• by written notice from TRC to Plum if (i) there is any breach of any representation, warranty or covenant of Plum set forth in the Business Combination Agreement such that any condition to closing would not be satisfied at the Closing, subject to a 30-day period to cure and (ii) TRC is not in material breach of its representations, warranties or covenants under the Business Combination Agreement.
In the event of the valid termination of the Business Combination Agreement, the Business Combination Agreement shall forthwith become void and have no effect, without any liability on the part of either Party or its respective Affiliates, officers, directors, employees, shareholders or other Representatives, other than liability of any Party for any willful and material breach of the Business Combination Agreement occurring prior to such termination, and other than liability for payment of the expenses set forth below.
Expenses.
Each Party shall be responsible for and pay its own expenses incurred in connection with the Business Combination Agreement, including all fees and expenses of its legal counsel, financial advisors, investment bankers, accountants and other advisors; provided, that, if the Closing shall occur, PubCo shall pay the outstanding TRC Transaction Expenses and the outstanding Plum Transaction Expenses. Notwithstanding the foregoing:
• If the Business Combination Agreement is validly terminated by Plum following a TRC Modification in Recommendation or by TRC following a TRC Superior Proposal, then TRC shall pay to Plum within two Business Day after any such termination, a fee equal to the sum of (i) $2,000,000 and (ii) the lesser of $2,500,000 and the reasonable and documented third-party, out-of-pocket fees and expenses incurred and payable by or on behalf of Plum, PubCo or Amalco in connection with the Business Combination
141
Agreement. This fee shall constitute liquidated damages under the Business Combination Agreement and, if paid, shall be the sole and exclusive remedy of Plum, PubCo and Amalco against TRC arising out of termination of the Business Combination Agreement.
• If the Business Combination Agreement is validly terminated by TRC following a Plum Recommendation Modification, then Plum shall pay to TRC the sum of (i) $2,000,000 and (ii) the lesser of $2,500,000 and the reasonable and documented third-party, out-of-pocket fees and expenses incurred and payable by or on behalf of TRC in connection with the Business Combination Agreement. This termination fee shall constitute liquidated damages under the Business Combination Agreement shall be the sole and exclusive remedy of TRC against Plum, PubCo and Amalco arising out of termination of the Business Combination Agreement.
Governing Law
The Business Combination Agreement shall be governed by, and construed in accordance with, the Laws of the State of New York without giving effect to principles or rules of conflict of Laws to the extent such principles or rules would require or permit the application of Laws of another jurisdiction; provided, however, that (a) the fiduciary duties of the TRC Board and the TRC Special Committee shall be governed by the Laws of the Province of British Columbia, and (b) prior to the Domestication, the fiduciary duties of the Plum Board shall be governed by the Laws of the Cayman Islands.
Amendments
The Business Combination Agreement may be amended or modified at any time, in whole or in part, only by a duly authorized agreement in writing executed by Plum and TRC.
Related Agreements
Sponsor Support Agreement
PubCo, Plum, TRC, Mercury Capital, LLC (“Sponsor”), Alpha Partners Technology Merger Sponsor LLC (“Former Sponsor”), and certain other Plum Shareholders set forth therein (together with Sponsor and Former Sponsor, the “Sponsor Parties”) entered into a voting and support agreement on August 22, 2024 (the “Sponsor Support Agreement”) pursuant to which, among other things, each of the Sponsor Parties agreed to (i) refrain from transferring any of his, her or its Plum Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (ii) vote his, her or its Plum Shares and any additional Plum Shares he, she or it acquires prior to the Plum Shareholders’ Meeting in favor of each of the Plum Shareholder Proposals at the Plum Shareholders’ Meeting, (iii) waive, and not exercise, any rights he, she or it may have to elect to effect a Plum Share Redemption in connection with the Plum Shareholders’ Approval or the Transactions and (iv) waive, and not enforce, any anti-dilution rights he, she or it may have under the Plum Governing Documents in connection with the Transactions. The Sponsor Parties did not receive any consideration for agreeing to waive, and not exercise, any rights he, she or it may have to elect to effect a Plum Share Redemption.
A number of affiliated and unaffiliated investors (the “Former Sponsor Anchors”) are entitled to receive from Sponsor up to 2,030,860 Plum Class B Units (each consisting of one Plum Class B Shares and one-third of a warrant to acquire one Plum Class B Share (collectively, the “Sponsor Incentive Units”)) if they hold a certain number (their “Required Number”) of Plum Class A Shares on the closing date of the Business Combination. If Sponsor transfers any of the Sponsor Incentive Units to parties other than the Former Sponsor Anchors and any of the Former Sponsor Anchors are or become entitled to Plum Class B Units because they hold or held their Required Number at the closing of a business combination, Sponsor shall transfer such number of Plum Class B Units to such Former Sponsor Anchor from its own account. Prior to the Closing, Sponsor shall use its commercially reasonable efforts to consummate the PIPE Investment, including entering into agreements pursuant to which Sponsor shall agree to transfer Sponsor Incentive Units to the counterparties in connection with the concurrent execution by such Persons of PIPE Subscription Agreements. Prior to the Closing, Sponsor may to transfer Sponsor Incentive Units to Plum Public Shareholders in connection with (i) the concurrent execution by such Plum Public Shareholders of agreements not to elect to effect a Plum Share Redemption, or (ii) in the event such Plum Public Shareholders have already elected to effect a Plum Share Redemption, to incentivize such Plum Public Shareholders to unwind or facilitate the unwinding
142
of their respective elections to effect a Plum Share Redemption. At the Closing, Sponsor shall irrevocably forfeit to PubCo for cancellation for no consideration any Sponsor Incentive Units which have not been transferred to the Former Sponsor Anchors, PIPE Investors or Plum Public Shareholders in the circumstanced described above.
TRC Securityholder Support Agreements
PubCo, Plum, TRC and the Key TRC Securityholders have entered into a voting and support agreement on August 22, 2024 (the “TRC Securityholder Support Agreement”) pursuant to which, among other things, each of the Key TRC Securityholders agreed to (a) refrain from transferring any of his, her or its TRC Common Shares prior to the Closing, other than in connection with certain permitted transfers described therein, (b) vote his, her or its TRC Common Shares and any additional TRC Common Shares he, she or it acquires prior to the TRC Shareholders Meeting in favor of each of the TRC Shareholder Proposals, including the TRC Arrangement Resolution, at the TRC Shareholders Meeting and (c) waive, and not exercise, any Dissent Rights he, she or it may have with respect to the Transactions.
Registration Rights Agreement
Plum and the Sponsor Parties are parties to a registration rights agreement, dated as of July 27, 2021 (the “Original Registration Rights Agreement”), and, at the Closing, PubCo and the Sponsor Parties shall enter into a registration rights agreement (the “Registration Rights Agreement”) pursuant to which, among other things, (a) PubCo (as successor-in-interest to Plum) and the Sponsor Parties shall terminate the Original Registration Rights Agreement and (b) PubCo shall provide the Sponsor Parties with certain demand and piggyback registration rights with respect to the PubCo Common Shares (and any securities convertible into or exercisable for PubCo Common Shares) to be held by such Persons immediately following the Closing.
Sponsor Parties Lock-up Agreement
PubCo, Plum and the Sponsor Parties have entered into a lock-up agreement (the “Sponsor Parties Lock-Up Agreement”) pursuant to which, among other things, each Sponsor Party agreed that he, she or it shall not transfer any of his, her or its Plum Class B Shares (or any Plum Class A Shares issuable upon conversion thereof, or any securities into which Plum Class B Shares or Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) (“Lock-Up Shares”) until the date that is the day immediately following the six-month anniversary of the completion of the Business Combination (the “Lock-Up Restriction”); provided, however, that following the consummation of the Business Combination, (i) if a Stock Price Level equal to or greater than $15.00 is achieved, the Lock-Up Restriction shall expire with respect to one-third of the Lock-Up Shares held by each such person, (ii) if a Stock Price Level equal to or greater than $20.00 is achieved, the Lock-Up Restriction shall expire with respect to an additional one-third of the Lock-Up Shares held by each such person, and (iii) if a Stock Price Level equal to or greater than $25.00 is achieved, the Lock-Up Restriction shall expire with respect to the last one-third of the Lock-Up Shares held by each such person. For purposes hereof: (x) “Stock Price Level” means the daily volume weighted average closing sale price per share of the Plum Class A Shares as quoted on NASDAQ for any 20 Trading Days within any 30 consecutive Trading Day period and (y) “Trading Day” means any day on which the Plum Class A Shares (or any securities into which Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) are actually traded on the principal securities exchange or securities market on which the Plum Class A Shares (or any securities into which Plum Class A Shares are converted or exchangeable pursuant to the Business Combination) are then traded.
Each Sponsor Party also agreed that he, she or it will not transfer any of his, her or its Private Placement Units, private placement shares, private placement warrants, Founder Units, founder warrants or Plum Class A Shares issued upon conversion or exercise thereof (or any securities into which any of the foregoing are converted or exchangeable pursuant to the Business Combination) until 30 days after the completion of the Business Combination.
Background of the Business Combination
Plum is a blank check company, incorporated on February 5, 2021 under its original name “Alpha Partners Technology Merger Corp.,” and formed for the purpose of effecting a merger, capital stock exchange, asset acquisition, stock purchase, reorganization or similar business combination with one or more businesses. The Business Combination with TRC is a result of an active search for a potential initial business combination by the
143
Plum Board and the Plum management team. The terms of the Business Combination are the result of extensive negotiations between representatives of Plum and TRC. The following is a description of the background of these negotiations and the resulting terms of the Business Combination.
Prior to the consummation of Plum’s Initial Public Offering on July 30, 2021, neither Plum, nor anyone on its behalf, engaged in any substantive discussions, directly or indirectly, with any potential business combination target with respect to an initial business combination with Plum.
The Initial Public Offering and the Former Sponsor
In January 2021, the Alpha Partners Technology Merger Sponsor LLC (the “Former Sponsor”) purchased 7,187,500 founder units for an aggregate purchase price of $25,000, or approximately $0.003 per unit, 125,000 of which were forfeited on September 11, 2021.
On July 30, 2021, Plum consummated its Initial Public Offering of 25,000,000 Units, at $10.00 per Unit, generating gross proceeds to Plum of $250,000,000 (before underwriting discounts, commissions and offering expenses), and on August 3, 2021, Plum issued an additional 3,250,000 Units at $10.00 per Unit upon the partial exercise by the underwriter of its over-allotment option, generating additional gross proceeds to Plum of $32,500,000 (before underwriting discounts, commissions and offering expenses). Simultaneously with the consummation of the Initial Public Offering, Plum issued 800,000 private placement units at $10.00 per unit to the Former Sponsor and certain anchor investors, generating additional gross proceeds to Plum of $8,000,000. Simultaneously with the issuance and sale of the units sold in the over-allotment, Plum issued an additional 65,000 units to the Former Sponsor, generating gross proceeds of $650,000.
After completion of the Initial Public Offering, the Former Sponsor conducted a search for prospective businesses or assets to acquire in an initial business combination. The search continued for more than 24 months. During that time, at an extraordinary general meeting held on July 27, 2023, the shareholders of Plum approved an amendment to Plum’s amended and restated memorandum and articles of association (the “Articles”) in order to extend the date by which the Plum must consummate its initial business combination from July 30, 2023 to July 30, 2024, in connection with which the holders of 13,532,591 Plum Class A Shares properly exercised their right to redeem their shares for cash at a redemption price of approximately $10.41 per share, for an aggregate redemption amount of approximately $140,838,808.
On December 11, 2023, Plum issued a press release announcing that the Plum Board had determined that it was in the best interest of its shareholders to liquidate and redeem all Plum Class A Shares because of the termination of a previously announced letter of intent for a business combination with Glowforge, Inc., a creator of 3D laser printers.
Sponsor Purchases Plum from the Former Sponsor
On December 26, 2023, the Plum Board announced that it was postponing the previously announced liquidation due to a number of groups seeking to acquire interests of the Former Sponsor that would continue funding Plum until it was able to complete a business combination. On December 27, 2023, the Former Sponsor and Mercury Capital LLC (the “Sponsor”) entered into a purchase agreement (the “Purchase Agreement”), pursuant to which Sponsor purchased 3,902,648 founder units from Former Sponsor and became entitled to 70% of 2,030,860 founder units that Former Sponsor had placed into escrow, to the extent such founder units were not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of the initial business combination, for an aggregate purchase price of $1.
In connection with the closing of the Purchase Agreement, the Sponsor and Plum’s officers and directors entered into the Registration and Shareholder Rights Agreement and Letter Agreement with Plum. The Registration and Shareholder Rights Agreement provides for, among other things, customary demand and piggy-back registration rights. The Letter Agreement with Plum provides that the Sponsor and Plum’s officers and directors agree to waive their redemption rights with respect to any founder shares and public shares acquired during or after the public offering by them in connection with (i) the consummation of a business combination, including, without limitation, any such rights available in the context of a shareholder vote to approve such business combination, (ii) a shareholder vote to approve an amendment to the Articles (A) to modify the substance or timing of Plum’s obligation to allow redemption in connection with our initial business combination or to redeem 100% of the Offering Shares if Plum has not consummated a business combination within the time period set forth in the Articles or (B) with
144
respect to any other material provisions relating to shareholders’ rights or pre-initial business combination activity or in the context of a tender offer made by Plum to purchase Offering Shares (although the Sponsor, the Insiders and their respective affiliates shall be entitled to redemption and liquidation rights with respect to any Plum Class A Shares sold as part of the Units in the initial public offering (“Offering Shares”) it or they hold if Plum fails to consummate a business combination within the time period set forth in the Articles), (iii) waive their rights, title, interest or claim of any kind in or to any monies held in the Trust Account or any other asset of Plum as a result of any liquidation of Plum with respect to the founder shares held by it, him or her and (iv) vote their founder shares and Public Shares in favor of a initial business combination.
After the closing of the Purchase Agreement, Plum’s officers, directors, and advisors commenced an active and thorough search for prospective businesses or assets to acquire in an initial business combination, drawing upon, among other things, the extensive network and investing and operating experience of Plum’s management, board, and advisors. Consistent with its investment principles, Plum sought business combination targets with one or more of the following core attributes: a large addressable market, an experienced management team, robust growth prospects, a strong business model and a barrier to entry. Representatives of Plum were contacted by, and representatives of Plum contacted, numerous individuals, financial advisors, business owners and other entities who offered to present ideas for business combination opportunities. Plum’s officers and directors and their affiliates actively searched for and brought business combination targets to Plum’s attention across several business sectors, including, without limitation, software, fintech, healthcare, e-commerce, digital media, cleantech additive manufacturing, tech-enabled services, automotive technologies and mining. These entities were based in the United States and internationally. As part of its process, Plum compiled and maintained a list of potential targets, prioritized, updated and supplemented such list from time to time as it was introduced to additional targets and as it acquired additional data through discussions with representatives.
From January 2024 through May 2024, Plum and its representatives:
• participated in in-person, telephonic or videoconference discussions with representatives of more than 20 potential acquisition targets;
• signed non-disclosure agreements with eight potential targets (other than TRC); and
• submitted initial non-binding indications of interest (orally and in writing) to representatives of three potential acquisition targets (other than TRC), as further described below.
Plum evaluated potential acquisition targets based on criteria that were the same or similar to the criteria the Plum Board used in evaluating the business combination with TRC (as discussed below), which included, among other criteria, such potential acquisition targets’ public-company readiness and Plum management’s assessment regarding their potential to become a long-term leader among public companies in their industries, including, but not limited to, their growth prospects, competitive position, financials, leadership and management teams’ capabilities, valuation expectations and certainty of deal execution.
Working Capital Financing
In support of its search for prospective businesses or assets to acquire in an initial business combination, Plum entered into several agreements with investors to provide working capital to fund Plum’s ordinary course operations.
On January 3, 2024, Plum entered into a subscription agreement with Palmeira Investment Limited (“Palmeira”) and the Sponsor; the purpose of which was for the Sponsor to raise up to $1,500,000 from Palmeira to fund extension payments and to provide working capital to Plum. In consideration of the funds, Sponsor agreed to forfeit 0.85 Class B ordinary shares for each dollar funded by Palmeira pursuant to the subscription agreement, and Plum would issue an equal number of shares of its common stock to Palmeira. If Plum’s initial business combination does not occur, the Sponsor will not forfeit any shares.
During July and August, 2024, the Sponsor entered into letter agreements with a number of investors providing for the sale by Sponsor of a certain number of Class B ordinary shares to such investors. The purpose of these letter agreements is to enable Sponsor to raise funds necessary to fund working capital requirements for Plum. The funds were transferred to the Sponsor shortly after signing, in consideration for which the Sponsor has undertaken to transfer the shares to the investor the immediately prior to the closing of a business combination. If Plum’s initial business combination does not occur, the Sponsor will not transfer any shares.
145
Approval of the Extension of the Termination Date, Name Change
On January 29, 2024, Plum held an extraordinary general meeting of its Shareholders (the “First Extension Shareholders Meeting”) to amend Plum’s Articles to (1) extend the date by which Plum has to consummate a business combination from July 30, 2024 to January 30, 2025, or such earlier date as shall be determined by the Plum Board in its sole discretion (the “First Extension Amendment Proposal”) and (2) change the name of Plum from “Alpha Partners Technology Merger Corp.” to “Plum Acquisition Corp. III” (the “Name Change Proposal”). The shareholders of Plum approved the First Extension Amendment Proposal and the Name Change Proposal at the First Extension Shareholders Meeting and on February 1, 2024, Plum filed the amendment to the Articles with the Registrar of Companies of the Cayman Islands. In connection with the First Extension Shareholders Meeting, Plum and the Sponsor entered into non-redemption agreements with certain shareholders pursuant to which, if such shareholders did not redeem (or validly rescind any redemption requests on) their Plum Class A Shares in connection with the First Extension Shareholders Meeting, Sponsor would agree to transfer to such investors ordinary shares of Plum held by Sponsor immediately following the consummation of an initial business combination if they continued to hold such non-redeemed shares through the First Extension Shareholders Meeting. The non-redemption agreements were not expected to increase the likelihood that the First Extension Amendment Proposal was approved by shareholders but were expected to increase the amount of funds that remain in Plum’s trust account following the First Extension Shareholders Meeting.
In connection with the vote to approve the First Extension Amendment Proposal and the Name Change Proposal, the holders of 12,433,210 Plum Class A Shares properly exercised their right to redeem their shares for cash at a redemption price of $10.78 per share, for an aggregate redemption amount of $134,059,215.
On January 16, 2025, Plum held an extraordinary general meeting of its Shareholders (the “Second Extension Shareholders Meeting”) to amend Plum’s Articles to (1) extend the date by which Plum has to consummate a business combination from January 30, 2025 to July 30, 2025, or such earlier date as shall be determined by the Plum Board in its sole discretion (the “Second Extension Amendment Proposal”) and (2) to eliminate the limitation that Plum shall not consummate a business combination if it would not have net tangible assets of at least $5,000,001 immediately prior to, or upon such consummation of, such business combination (the “NTA Amendment Proposal”). The shareholders of Plum approved the Second Extension Amendment Proposal and the NTA Amendment Proposal at the Second Extension Shareholders Meeting and on January 17, 2025, Plum filed the amendment to the Articles with the Registrar of Companies of the Cayman Islands.
In connection with the vote to approve the Second Extension Amendment Proposal and the NTA Amendment Proposal, holders of 2,132,366 Plum Class A Shares properly exercised their right to redeem their shares for cash at a Redemption price of $11.24 per share, for an aggregate Redemption amount of $23,975,464.
Description of Plum’s discussions with candidates other than TRC
Other than TRC, the potential targets that Plum considered in greater detail and with which Plum entered into formal negotiations included: (i) Glowforge Inc., a creator of 3D laser printers (“Glowforge”); (ii) a software analytics company (“Company A”); (iii) a gold and copper mining company (“Company B”); and (iv) a pharmaceutical company (“Company C”).
On July 26, 2023, Plum (then known as Alpha Partners Technology Merger Corp.) signed a non-binding letter of intent for a business combination with Glowforge, a manufacturer of 3D laser printers. Under the terms of the letter of intent, Plum would become a combined entity with Glowforge, with Glowforge’s existing equity holders rolling 100% of their equity into the combined public company. After working on a potential transaction over a number of months, Glowforge and Plum mutually agreed that it was in both parties’ best interests for Glowforge to focus on its new product launches instead of allocating time and resources to a business combination. The letter of intent was terminated on December 8, 2023.
On October 16, 2023, a representative of the Sponsor was introduced to Company A by a mutual connection with Company A’s CEO. Over the following months, representatives of Sponsor and Company A met via videoconference on several occasions and met in person on two occasions to discuss strategic advisory and investment opportunities. The parties introduced their respective teams and discussed long-term goals to determine whether there was potential for a partnership. These meetings also included discussions of Company A’s business operations, strategic plan and potential to raise additional investment capital. On January 17, 2024, after Sponsor had acquired control of Plum, Plum management reached out to Company A to discuss the potential for a business
146
combination. After signing a non-disclosure agreement, Plum formally began its due diligence process with Company A. On February 8, 2024, Plum submitted a verbal, non-binding indication of interest to Company A. After deliberations and negotiations over the next month, Plum determined that Company A would be unable to meet Plum’s proposed timeline for the contemplated transaction due to, among other things, the need for PCAOB audits. On March 22, 2024, Plum and Company A mutually decided to terminate discussions and pursue other transactions.
On April 11, 2024, a representative of Plum was introduced to Company B by an investment bank representing Company B. After signing a non-disclosure agreement, Company B provided Plum with information about its business and strategic plans. Over the following weeks, representatives of Plum and Company B met via videoconference on several occasions to further learn about the business and discuss a potential business combination. On April 28, 2024, Company B provided Plum with access to its data room, which contained additional information on Company’s B mining operations and financial information. On May 1, 2024, Plum submitted a written, non-binding indication of interest to Company B. On May 8, 2024, after further discussions between Plum and Company B, Plum updated and resubmitted its written, non-binding indication of interest to Company B. After deliberations and negotiations over the following weeks, Company B informed Plum that it was moving forward with an alternative transaction.
On March 26, 2024, a representative of Plum was introduced to Company C through an existing investor in Company C. After signing a non-disclosure agreement, on March 26, 2024, representatives of Plum and Company C met via videoconference and Company C provided Plum with information about its business and strategic plans. After the meeting, Company C provided Plum with access to its data room, which contained additional information about its drug portfolio and commercialization plans. Over the following days, Plum continued its due diligence through discussions with representatives of Company C and the existing investor who made the introduction. On April 3, 2024, Plum submitted a verbal, non-binding indication of interest to Company C. Plum spent the following week continuing diligence on Company C, and also speaking with investors on a no-name basis, to determine if raising capital as part of the contemplated transaction was probable. When it became apparent that the likelihood of a capital raise for Company C was low, Plum and Company C mutually decided to terminate discussions and pursue other transactions.
Description of negotiation process with TRC
On March 13, 2024, Mr. Brandon Sun of Cohen and Company Capital Markets, a division of J.V.B. Financial Group LLC (“Cohen”), reached out to Mr. Kanishka Roy, the President, Chief Executive Officer and Chairman of Plum, and Mr. Steven Handwerker, the Chief Financial Officer of Plum, to gauge their interest in an introduction to TRC, who was exploring a potential business combination with a special purpose acquisition company. Cohen was made aware of the opportunity by Jett Capital Advisors, LLC (“Jett”), who, as TRC’s exclusive financial advisor for the potential transaction, had reached out to Cohen to discuss before Cohen brought the idea to Plum. After Plum expressed interest, Cohen scheduled an introductory call for March 22, 2024 between Mr. Roy and Mr. Handwerker, representing Plum, Mr. Ranjeet Sundher, the Chief Executive Officer of TRC, Mr. Kuljit Basi, the Executive Chairman of TRC, Mr. Sean Bromley, a consultant to TRC, and, at the invitation of TRC, Mr. Justus Parmar, representing Fortuna Investments Corp (“Fortuna”), an investor in TRC. Thereafter, Plum management reviewed publicly available information about TRC and its business and industry. Plum’s management determined that TRC may be a strong target business due to TRC’s ability to quickly commercialize their mining project and produce rare earth elements well before their America-based competitors. TRC also showed a strong demand for their product in the market, demonstrated that geopolitical sentiment could help garner investor interest, and benefitted from an experienced management team who could execute on their strategic plans. These factors aligned with Plum’s investment principles. See the section of this proxy statement/prospectus entitled “Business Combination Proposal — The Plum Board’s Reasons for the Business Combination” for a further discussion of the Plum Board’s considerations.
The following chronology summarizes the key meetings and events that led to the execution of the Term Sheet (as defined below) and Business Combination Agreement and other ancillary agreements with TRC, but it does not purport to catalogue every conversation among representatives of Plum, TRC and their respective advisors.
On March 22, 2024, Mr. Roy, Mr. Handwerker, Mr. Sundher, Mr. Basi, Mr. Bromley, Mr. Scott McLeod, as counsel to TRC, Mr. Parmar and, representing Jett, Mr. Matt Jurjevich, Mr. Elan Oumarov, Mr. Kedar Patel and Mr. James Yates, and, representing Cohen, Mr. Sun and Mr. Badis Friaa, met via videoconference for introductions and to discuss their respective companies and the possibility of engaging in discussions regarding a potential business combination transaction.
147
On March 25, 2024, Plum, and TRC entered into a confidentiality letter agreement to allow Plum to learn more information about TRC’s business operations, historical financial information, and mineral resources.
On April 5, 2024, TRC invited Plum to its virtual data room. Over the next week, Plum continued to review the virtual data room, perform diligence on TRC’s operations, resources, and customers.
On April 10, 2024, Mr. Roy, Mr. Handwerker, Mr. Basi, Mr. Bromley, Mr. Sun of Cohen and Mr. Jurjevich of Jett met in Cohen’s offices and via videoconference to discuss TRC’s strategy, business operations, historical financial information, general corporate matters and the plan for further diligence. Topics included the buildout of a multi-phase go-to-market plan, financing for such a plan and the timeline for a merger transaction between TRC and Plum. Those in attendance also discussed high-level constructs for valuation and comparable transactions that would be relevant in determining valuation.
On April 11, 2024, Plum delivered to TRC an initial draft term sheet (the “April 11 Draft Proposal”), which provided for, among other things, the following non-binding material terms for a proposed business combination of Plum and TRC: (i) a tax-free reorganization in which Plum would form a merger subsidiary that would merge with and into TRC in a reverse triangular merger, as advised by Plum’s and TRC’s respective tax advisors and based on a review of SPAC transactions consummated by similarly-situated businesses, (ii) a pre-money equity value of $500 million payable in the form of Plum Class A Shares and, to incentivize TRC management towards stock-price appreciation, a target earn-out equal to 1,000,000 shares which would be payable in three tranches upon achievement of the post-combination company of trading prices of $12.50, $15.00 and $17.50, respectively, for any 20 trading-days within any 30 trading-day period prior to the fifth anniversary of the closing of the potential business combination; (iii) a six month lock-up of the Sponsor Shares subject to early releases of 1/3 of such shares if the trading prices of $12.50, $15.00, and $17.50 were achieved, for any 20 trading-days within any 30 trading-day period prior to the expiration of the lock-up; (iv) Sponsor’s intention to help TRC raise $30 million in new financing to fund the initial development phase of the plan to commercialize and process rare earth elements, including Sponsor’s intention that $10 million of such amount would be raised by Sponsor and/or its direct or indirect investors, and (v) Sponsor’s right to appoint one director to the board of directors of the post-combination company and have one additional director mutually agreed upon by the parties. The pre-money equity valuation was determined after considering valuations of comparable publicly-listed mining companies such as Lynas Rare Earths, Iluka, WA Resources Ltd, Brazilian Rare Earths and Arafura Rare Earths Limited, as well as MP Materials, which was publicly listed after a de-SPAC transaction. The April 11 Draft Proposal also included a binding exclusivity period of 30-days for each party following the execution of the letter of intent, subject to an automatic 15-day extension if Plum and TRC continued to work in good faith towards the signing of a business combination agreement, during which period Plum and TRC would be prohibited from soliciting or negotiating any competing transaction.
On April 12, 2024, Plum signed a Non-Disclosure Agreement with WSP USA Inc. (“WSP”), an engineering and professional services firm with expertise in mine engineering, to facilitate discussions regarding the engagement of WSP to conduct technical due diligence of TRC in connection with the proposed transaction.
On April 15, 2024, Representatives of Plum and WSP met via videoconference for introductions and to outline the scope of the necessary technical diligence.
Between April 12, 2024, and May 6, 2024, discussions between Plum and TRC temporarily ceased while TRC considered a potential alternative transaction with another party. Plum continued its diligence on TRC during this period, including diligence relating to operational aspects of the business and potential financing sources.
On May 7, 2024, Mr. Jurjevich of Jett contacted Mr. Sun of Cohen to resume negotiations on a potential transaction. Mr. Roy and Mr. Handwerker of Plum and Mr. Sundher, Mr. Basi and Mr. Bromley of TRC, together with Mr. Sun, Mr. Jurjevich and Mr. Oumarov, then continued to have conversations about the terms of the April 11 Draft Proposal and further negotiate the terms of a potential transaction, including committed funding that could be brought by the Sponsor, valuation and a management earn-out.
On May 9 and May 15, 2024, Plum received comments from TRC on the April 11 Draft Proposal. The comments provided for, among other changes, (i) a twelve-month lock-up of the Sponsor Shares subject to early releases of 1/3 of such shares if the trading prices of $15.00, $20.00, and $25.00 were achieved, (ii) subjecting the earn-out shares to the same lock-up provisions as the Sponsor Shares, (iii) a commitment by Sponsor to raise $10 million of the proposed $30 million in new financing, and (iv) an acknowledgement of Sponsor’s interest in appointing one director to the board of directors of the post-combination company.
148
On May 13, 2024, Mr. Alan Black, Mr. David Sable and Mr. Mike Dinsdale, each a member of the Plum Board at the time, met via videoconference with Mr. Roy and Mr. Handwerker, representing Plum management. Plum management updated the Plum Board of its evaluation of TRC as a potential acquisition target, including an update on Plum’s operational, legal and financial due diligence of TRC conducted to date, the key terms of the April 11 Draft Proposal and the comments received from TRC, including aspects of valuation and the management earn-out, financing of the transaction and expenses. The Plum Board resolved unanimously to direct management to finalize and enter into the Term Sheet (as defined below) with TRC.
On May 16, 2024, Plum delivered to TRC a revised draft term sheet (the “May 16 Draft Proposal”), which responded to TRC’s comments on the April 11 Draft Proposal by proposing (i) a target earn-out equal to 1,000,000 shares which would be payable in three tranches upon achievement of the post-combination company of trading prices of $15.00, $20.00 and $25.00, respectively, (ii) a six-month lock-up of the Sponsor Shares and the earn-out shares, subject to early releases of 1/3 of such shares if the trading prices of $15.00, $20.00, and $25.00 were achieved, and (iii) a commitment by the Sponsor to raise $10 million of the proposed $30 million in new financing through the use of the Sponsor’s incentive shares or other means.
On May 21, 2024, Plum received comments from TRC (the “May 21 Draft Proposal”) on the May 16 Draft Proposal. The May 21 Draft Proposal provided for, among other things, the following non-binding material terms for a proposed business combination of Plum and TRC: (i) a pre-money equity value of $500 million payable in the form of Plum Class A Shares and a target earn-out equal to 1,000,000 shares which would be payable in three tranches upon achievement of the post-combination company of trading prices of $12.50, $15.00 and $17.50, respectively, for any 20 trading-days within any 30 trading-day period prior to the fifth anniversary of the closing of the potential business combination; (ii) a six month lock-up of the earn-out shares and Sponsor Shares subject to early releases of 1/3 of the such shares if the trading prices of $15.00, $20.00, and $25.00 were achieved, for any 20 trading-days within any 30 trading-day period prior to the expiration of the lock-up; (iii) Sponsor’s intention to help TRC raise $30 million in new financing, including Sponsor’s commitment that $10 million of such amount would be funded through the use of the Sponsor’s incentive shares or other means, and (iv) TRC’s acknowledgement of Sponsor’s interest to appoint one director to the board of directors of the post-combination company. The May 21 Draft Proposal also included a binding exclusivity period of 30-days for each party following the execution of the letter of intent, subject to an automatic 15-day extension if Plum and TRC continued to work in good faith towards the signing of a business combination agreement, during which period Plum and TRC would be prohibited from soliciting or negotiating any competing transaction.
Also on May 21, 2024, Mr. Roy, Mr. Handwerker, Mr. Basi, Mr. Bromley, Mr. McLoed, Mr. Parmar of Fortuna, Mr. Sun, Mr. Friaa and Ms. Vera Xing of Cohen, and Mr. Jurjevich and Mr. Oumarov of Jett, met via videoconference to discuss the financing strategy for the transaction, during which Cohen and Jett delivered a presentation outlining the transaction timeline and fundraising strategies.
On May 23, 2024, Plum and TRC executed the May 21 Draft Proposal (hereafter, the “Term Sheet”), entering the parties into exclusivity. Later that day, representatives of Plum, TRC, Fortuna, Cohen, Jett, Hogan Lovells US LLP (“Hogan Lovells”), serving as U.S. counsel to Plum for the transaction, and A&O Shearman & Sterling (“AOS”), serving as U.S. counsel to TRC for the transaction, met via videoconference for introductions and to align on next steps in progressing the transaction.
On May 27, 2024, representatives of Hogan Lovells were granted access to TRC’s virtual data room, and Hogan Lovells commenced legal due diligence. The virtual data room was organized into various specific folders and subfolders housing documents related to corporate records, personnel information, financial statements, technical materials and project-related information.
On May 28, 2024, Plum formally engaged WSP to conduct the agreed-upon technical review and to provide expert opinions relating to TRC’s geology, mining, engineering, and radiation-related occupational hazards matters and documents, including their 2022 National Instrument 43-101 Technical Report.
Also on May 28, 2024, Mr. Roy and Mr. Handwerker of Plum and Mr. Basi, Mr. Bromley, Mr. McLeod, Mr. Matthew Chatterton, Mr. Austin Thornberry and Mr. Patrick Whibley, each of TRC, Mr. Parmar of Fortuna and representatives of Hogan Lovells and AOS met via videoconference to discuss the process for incorporating the provisions contained in the Term Sheet into a binding Business Combination Agreement and the ongoing due diligence process.
149
On May 30, 2024, representatives of Plum and ICR, LLC (“ICR”), an investor and press relations consultancy, met via videoconference to discuss the potential engagement of ICR to provide investor and public relations services in connection with the transaction.
On June 4, 2024, Plum submitted a list of diligence and meeting requests to TRC. Over the following weeks, representatives of Plum and its advisors continued to conduct business and financial due diligence of TRC and held in-person and telephonic meetings and videoconferences with representatives of TRC and its advisors regarding, among other things, TRC’s leadership team, existing business and operational/financial model, historical and current financial information, operational performance, corporate governance structures, mineral resources and mineral resource estimates, strategic business plan and path to commercialization. In addition, beginning on June 4, 2024, representatives of Plum, TRC, Cohen, Jett, Hogan Lovells and AOS attended regular weekly meetings to report on the progress of the transaction, with Canadian counsel later joining after having been appointed.
On June 11, 2024, representatives of Plum and WSP met via videoconference to discuss WSP’s preliminary assessment of TRC’s rare earth elements project.
On June 13, 2024, Mr. Roy and Mr. Handwerker of Plum, Mr. Sundher, Mr. Basi, Mr. Bromley and Ms. Anna Hicken of TRC, Mr. Jurjevich, Mr. Oumarov, Mr. Patel and Mr. Yates of Jett, Mr. Sun, Mr. Friaa and Ms. Xing of Cohen, and, representing WSP, Mr. James Hahn, Ms. Carolyn Osborn, Mr. David Marston and Ms. Jennifer Simper met via videoconference to conduct technical due diligence on TRC’s rare earth elements project. Following the technical due diligence videoconference, Mr. Roy, Mr. Handwerker, Mr. Sundher and Mr. Alnesh Mohan, Chief Financial Officer of TRC, met separately via videoconference to conduct due diligence relating to certain management and financial diligence items, including verification of certain claims made by TRC, review of certain technical reports, and the provision of an independent third-party assessment of TRC’s technical progress.
On June 17, 2024, representatives of Plum and WSP met via videoconference, during which WSP delivered a presentation of its final technical due diligence findings.
Also on June 17, 2024, representatives of Plum and Aird & Berlis LLP (“Aird Berlis”) met via videoconference to discuss the potential engagement of Aird Berlis as Canadian counsel to Plum with respect to the transaction. Aird Berlis was formally engaged on July 11, 2024.
On June 18, 2024, Mr. Roy, Mr. Handwerker, Mr. Basi, Mr. Mohan, Mr. Bromley, Mr. McLeod, Mr. Chatterton, Mr. Thornberry, Mr. Whibley, Mr. Parmar of Fortuna, Mr. Jurjevich, Mr. Oumarov, Mr. Patel and Mr. Yates of Jett and Mr. Sun, Mr. Friaa, Ms. Xing and Mr. Dan Nash of Cohen, and representatives of Hogan Lovells and AOS, including tax experts of both law firms, met via videoconference to discuss how to efficiently structure the transaction as it relates to tax liabilities and future operations.
On June 19, 2024, AOS delivered to Hogan Lovells the initial draft of the Business Combination Agreement (the “AOS June 19 Draft BCA”) setting forth transaction terms, representations and warranties, covenants, termination provisions and closing conditions substantially consistent with the Term Sheet. Over the following weeks, representatives of Plum, TRC, Fortuna, Hogan Lovells, Aird Berlis, AOS and McMillan LLP (“McMillan”), serving as Canadian counsel to TRC for the transaction, met telephonically and via videoconference and negotiated and exchanged drafts of the Business Combination Agreement, as well as exhibits and schedules to the Business Combination Agreement and various ancillary documentation related to the potential business combination and related transactions including, but not limited to, a Company Securityholder Support Agreement, Sponsor Support Agreement, Registration Rights Agreement, Plan of Arrangement, Share Award Agreement and the Sponsor Parties Lock-up Agreement, and negotiated and resolved open items for consideration. During the course of negotiations on the Business Combination Agreement, the parties focused on (i) the lock-up provisions applicable to TRC’s shareholders, (ii) the covenants of TRC and Plum, including interim operating covenants such as TRC’s ability to engage in any financings during the pre-closing period, (iii) closing conditions, (iv) details of Plum’s nominee to the post-closing company’s board of directors, and (v) the fee payable by TRC in the event of TRC’s termination of the Business Combination Agreement. The points of contention between Plum and TRC in this regard resolved through iterations of drafts of the Business Combination Agreement and discussions between Plum, TRC, and their respective representatives, as further described below.
On June 21, 2024, representatives of Plum, TRC, Fortuna and ICR met via videoconference to discuss ICR’s investor and public relations strategy for the transaction.
150
On June 24, 2024, the Plum Board met via videoconference, with Mr. Handwerker and representatives of Hogan Lovells, Plum’s auditing firm and Plum’s SEC reporting consultants in attendance, to discuss the filing of Plum’s annual report. After those in attendance left the meeting, the Plum Board and Mr. Handwerker continued the meeting in executive session, during which Mr. Handwerker updated the Plum Board on management’s evaluation of TRC as a potential acquisition target, including an update on the status of the documentation and related matters.
On June 25, 2024, Mr. Roy, Mr. Handwerker, Mr. Basi, Mr. Mohan, Mr. Bromley, Mr. McLeod, Mr. Chatterton, Mr. Thornberry, Mr. Whibley, Mr. Parmar of Fortuna, Mr. Jurjevich, Mr. Oumarov, Mr. Patel and Mr. Yates of Jett and Mr. Sun, Mr. Friaa, Ms. Xing and Mr. Nash of Cohen, and representatives Hogan Lovells and AOS, met via videoconference to discuss valuation and fundraising strategy. Jett and Cohen discussed the valuations of publicly traded comparable companies, key valuation metrics considered by investors, and their strategy for raising a PIPE Investment that investors would view favorably. They also discussed other transactions by comparable companies that had been considered by the market recently, and their success at raising capital at comparable valuations. These discussions did not result in any material changes in the parties’ existing agreement as to valuation, including structure, comparables and precedent transactions.
From June 25, 2024 to July 17, 2024 regular weekly videoconferences among representatives of Plum, TRC, Fortuna and their respective legal counsel and financial advisors continued to be held to report on the status of the transaction.
On July 2, 2024, Hogan Lovells delivered to AOS a revised draft of the Business Combination Agreement (the “HL July 2 Draft BCA”), which included, among other things, (i) changes to the scope and breadth of the representations and warranties of TRC relating to, for example, capitalization, material contracts, title, real estate, environmental, compliance, insurance, related parties, employment and labor, benefit plans, and tax matters, and removal of certain materiality and knowledge qualifications, (ii) changes to respective interim operating covenants of TRC and Plum, such as the inclusion of additional actions generally prohibited during the pre-closing period, and changes to other covenants relating to tax, permitting, dispute resolution and insurance matters and the addition of caps to certain of such proscribed actions, and (iii) the inclusion of a TRC termination fee. Aside from the foregoing substantive differences between the HL July 2 Draft BCA and the AOS June 19 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On July 12, 2024, AOS delivered to Hogan Lovells a revised draft of the Business Combination Agreement (the “AOS July 12 Draft BCA”), which included, among other things, (i) the restoration of certain materiality and knowledge qualifiers that had been added to certain representations and warranties of TRC in the HL July 2 Draft BCA, (ii) the deletion of certain proscribed actions and carveouts to such actions in the interim operating covenants of Plum and TRC added to the HL July 2 Draft BCA and the inclusion of new, or modification of existing, caps to such actions, (iii) changes in the amount of the TRC termination fee, and (iv) the inclusion of a Plum termination fee. Aside from the foregoing substantive differences between the AOS July 12 Draft BCA and the HL July 2 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On July 17, 2024, Mr. Roy, Mr. Handwerker, Mr. Basi, Mr. Bromley and Mr. Jurjevich of Jett met via videoconference to discuss the progress of the Business Combination Agreement and outstanding items that needed to be completed before signing.
Also on July 17, 2024, AOS delivered to Hogan Lovells the initial draft of the Registration Rights Agreement and Insider Letter Amendment. Through discussions among representatives of Hogan Lovells and AOS, the Registration Rights Agreement was finalized after several turns, and it was decided that the substantive terms of the Insider Letter Amendment would instead be contained in the Sponsor Parties Lock-up Agreement.
On July 19, 2024, AOS delivered to Hogan Lovells the initial drafts of the Company Shareholders Support Agreement and the Sponsor Support Agreement. Through discussion among representatives of Hogan Lovells and AOS, the Company Shareholders Support Agreement was revised and renamed as a Company Securityholders Support Agreement, which was finalized after several turns. Through further discussions among representatives of Hogan Lovells and AOS, the Sponsor Support Agreement was finalized after several turns.
151
On July 22, 2024, AOS delivered to Aird Berlis the initial draft of TRC’s disclosure schedules. AOS and Aird Berlis began negotiations relating to the disclosure schedules, focusing on matters such as the key TRC securityholders and the post-closing PubCo directors.
On July 24, 2024, Hogan Lovells delivered to AOS a revised draft of the Business Combination Agreement (the “HL July 24 Draft BCA”), which included, among other things, (i) the restoration of certain representations and warranties of TRC, such as those related to the permits of TRC and data privacy and security, and the removal of certain materiality qualifiers in the representations and warranties of TRC which appeared in the AOS July 12 Draft BCA, (ii) changes to the extent of the respective interim operating covenants of Plum and TRC in response to the revisions appearing in the AOS July 12 Draft BCA, such as the inclusion of positive obligations of TRC during the pre-closing period, (iii) changes to certain of the closing conditions, including the deletion of a warrant assignment, assumption and amendment agreement as a closing deliverable, and (iv) changes to the amount of the TRC termination fee. Aside from the foregoing substantive differences between the HL July 24 Draft BCA and the AOS July 12 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On July 29, 2024, Mr. Roy, Mr. Handwerker, Mr. Bromley of Jett and Mr. Parmar of Fortuna met via videoconference to discuss Fortuna’s views and potential support for the transaction. Those in attendance agreed that the terms of the proposed transaction were likely to attract substantial outside investment as part of the SPAC transaction.
On July 30, 2024, representatives of Hogan Lovells, Aird Berlis and AOS met via videoconference to discuss Hogan Lovells’ latest revisions to the Business Combination Agreement, focusing on finalizing the parties’ key representations and warranties.
On July 31, 2024, AOS delivered to Hogan Lovells a revised draft of the Business Combination Agreement (the “AOS July 31 Draft BCA”), which included, among other things, (i) the inclusion of lock-up provisions with respect to the TRC shareholders, (ii) changes to the interim operating covenants of TRC and Plum in response to the revisions reflected in the HL July 24 Draft BCA, such as modifications to certain of the caps to actions generally prohibited during the pre-closing period and the distillation of TRC’s positive obligations during the pre-closing period to comply with TRC’s governing documents and material contracts, and (iii) changes to certain of the closing conditions in response to the revisions reflected in the HL July 24 Draft BCA, such as the delivery of a SPAC amalgamation certificate of effectiveness. Aside from the foregoing substantive differences between the AOS July 31 Draft BCA and the HL July 24 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On August 3, 2024, Hogan Lovells delivered to AOS the initial draft of Plum’s disclosure schedules. Through discussions among representatives of Hogan Lovells and AOS, the disclosure schedules were finalized after several turns.
On August 3, 2024, Hogan Lovells delivered to AOS a revised draft of the Business Combination Agreement (the “HL August 3 Draft BCA”), which included, among other things, changes to (i) the interim operating covenants of TRC and Plum in response to the revisions reflected in the AOS July 31 Draft BCA (e.g., modifications to or deletion of caps), (ii) certain of the closing conditions in response to the revisions reflected in the AOS July 31 Draft BCA (e.g., replacement of an amalgamation certificate of effectiveness with a certificate of amalgamation), and (iii) the circumstances triggering the termination fee of each of TRC and Plum. Notwithstanding the foregoing substantive differences between the HL August 3 Draft BCA and the AOS July 31 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On August 4, 2024, the Plum Board met via videoconference, with Mr. Roy, Mr. Handwerker and a representative of Hogan Lovells in attendance, to discuss the Business Combination Agreement, the ancillary agreements and certain matters between signing and closing the transaction. Plum management provided updates to the Plum Board with respect to the final terms of the Business Combination Agreement and ancillary agreements based on the negotiations that had taken place over the course of the prior weeks. This included confirmations of the proposed valuation, the commitment from the Sponsor, the lock-up agreements and the plan to bring in additional debt and equity financing. Following discussions, the Plum Board approved the Business Combination, the Business
152
Combination Agreement and the transactions contemplated thereby, determined to recommend the adoption of the Business Combination Agreement and the transactions contemplated thereby to its shareholders, and directed management to finalize and enter into the Business Combination Agreement with TRC. Following the meeting, the Plum Board executed a unanimous written consent approving the business combination, the Business Combination Agreement, the ancillary agreements and the transactions contemplated thereby.
On August 7, 2024, Mr. Roy, Mr. Handwerker and Mr. Bromley met via videoconference to discuss Fortuna’s support of the transaction and views on fundraising, including the categories of investors — both private and public — that would be targeted, and structures to incentivize such investors.
On August 9, 2024, AOS delivered to Hogan Lovells a revised draft of the Business Combination Agreement (the “AOS August 9 Draft BCA”), which included, among other things, (i) changes to the lock-up provisions agreed upon by TRC and Plum, (ii) modifications to the caps in the interim operating covenants of TRC and Plum appearing in the HL August 3 Draft BCA, and (iii) the inclusion of vesting acceleration of outstanding TRC restricted stock units and a related closing condition. Aside from the foregoing substantive differences between the AOS August 9 Draft BCA and the HL August 3 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet
On August 14, 2024, Hogan Lovells delivered to AOS a revised draft of the Business Combination Agreement (the “HL August 14 Draft BCA”), which included, among other things, the conditions precedent to triggering the termination fee of TRC. Aside from the foregoing substantive difference between the HL August 14 Draft BCA and the AOS August 9 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On August 16, 2024, Mr. Roy, Mr. Handwerker, Mr. Sundher, Mr. Basi, Mr. Bromley, Mr. McLeod, Mr. Parmar of Fortuna, Mr. Jurjevich, Mr. Oumarov, Mr. Patel and Mr. Yates of Jett, Mr. Sun, Mr. Friaa, Ms. Xing and Mr. Nash of Cohen, and representatives of Hogan Lovells and AOS met via videoconference to discuss the progress of the transaction and legal documents that were being prepared in connection with the business combination.
Also on August 16, 2024, AOS delivered to Hogan Lovells a revised draft of the Business Combination Agreement (the “AOS August 16 Draft BCA”), which included, among other things, (i) changes to provisions relating to the conversion and exchange of Plum’s securities and TRC’s securities and (ii) changes to the circumstances triggering the termination fee of TRC. Aside from the foregoing substantive differences between the AOS August 16 Draft BCA and the HL August 14 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
Also on August 16, 2024, AOS delivered to Aird Berlis the initial draft of the Share Award Agreement. Through discussions among representatives of Aird Berlis and AOS, the Share Award Agreement was finalized.
On August 19, 2024, Mr. Roy, Mr. Handwerker, Mr. Sundher, Mr. Basi and Mr. Bromley met via videoconference to discuss the remaining open items in the Business Combination Agreement, which at this stage represented only minor differences between the parties.
On August 20, 2024, Hogan Lovells delivered to AOS a revised draft of the Business Combination Agreement (the “HL August 20 Draft BCA”), which included, among other things, the removal of the lock-up provisions in favor of separate lock-up agreements with TRC shareholders. Aside from the foregoing substantive difference between the HL August 20 Draft BCA and the AOS August 16 Draft BCA, there were little to no material differences at this stage of the negotiations of the Business Combination Agreement with respect to the terms as agreed upon by Plum and TRC in the Term Sheet.
On August 21, 2024, Hogan Lovells delivered to AOS the initial draft of the Sponsor Parties Lock-up Agreement, incorporating substantive provisions from the Insider Letter Amendment previously negotiated between Hogan Lovells and AOS. After further discussions between Hogan Lovells and AOS, the Sponsor Parties Lock-up Agreement was finalized.
153
Also on August 21, 2024, Plum formally engaged Cohen as its financial advisor to represent and advise Plum on the transaction. Cohen was chosen for the direct experience and expertise within the special purpose acquisition company space. Cohen was not engaged by Plum to provide any report, opinion or appraisal in connection with the transaction, and did not deliver a report, opinion or appraisal to Plum. Cohen did not conduct any diligence on TRC on Plum’s behalf. Cohen’s support included providing market trading data on specific comparables and precedent transactions and advice on matters relating to Plum’s diligence investigation, in each case at the request of Plum management.
On August 22, 2024, Mr. Roy, Mr. Handwerker, Mr. Sundher, Mr. Basi, Mr. Bromley, Mr. McLeod, Mr. Thornberry, Mr. Whibley, Mr. Parmar of Fortuna, Mr. Jurjevich, Mr. Oumarov, Mr. Patel and Mr. Yates of Jett and Mr. Sun, Mr. Friaa, Ms. Xing and Mr. Nash of Cohen, and representatives of Hogan Lovells, AOS, Aird Berlis and McMillan met via videoconference to discuss the remaining minor open points and finalize the Business Combination Agreement. Such points included revisions to the representations and warranties relating to Plum’s capitalization, minor revisions to the interim operating covenants of TRC, and finalization of the lock-up arrangement as agreed upon by Plum and TRC. AOS then delivered to Hogan Lovells the final revised draft of the Business Combination Agreement, reflecting final revisions as agreed by the parties thereto. Representatives of Hogan Lovells and AOS then met via videoconference to confirm the finalization of the documents to signed and to discuss the logistics of the signing process. Thereafter, Plum and TRC entered into the Business Combination Agreement and certain ancillary agreements.
On August 23, 2024, Plum and TRC issued a joint press release announcing the business combination. Subsequently, Plum filed a Current Report on Form 8-K that included the joint press release announcing the Business Combination, along with the investor presentation, the Business Combination Agreement (and related exhibits) and the other material agreements entered into by Plum in connection with the Business Combination.
On December 10, 2024, Plum and TRC entered into an amendment (the “Amendment”) to the Business Combination Agreement. The Amendment provides that, among other things, upon a delisting from The Nasdaq Stock Market, the Company will use commercially reasonable efforts to list its securities on the OTC Markets Group. As a condition to closing the Business Combination, the Company must relist its securities on The Nasdaq Stock Market.
The TRC Board’s Reasons for Approval of the Business Combination
The TRC Board, in evaluating the Business Combination, consulted with TRC’s management and legal, financial and mineral expert advisors. The TRC Board also received presentations from, and discussed with, TRC’s third-party legal and financial advisors regarding the transaction structure, material terms of the Business Combination and various aspects of the due diligence. In reaching its unanimous decision to (i) determine that the Business Combination is in the best interests of TRC and its shareholders, (ii) approve and declare advisable the Business Combination Agreement and the transactions contemplated thereby and (iii) recommend that the TRC shareholders adopt the Business Combination Agreement, and the transactions contemplated thereby, including the Business Combination, the TRC Board considered a range of factors, including, but not limited to, the factors discussed below. The TRC Board did not consider it practicable to, and did not attempt to, quantify or otherwise assign relative weights to the specific factors that it considered in reaching its determination and supporting its decision. The TRC Board viewed its decision as being based on all of the information available and the factors presented to and considered by it. In addition, individual directors may have given different weight to different factors. These factors included:
• Larger, More Relevant Market. TRC’s common shares have been listed on a Canadian stock exchange, the TSX, since March 2022 and at the time of listing, it also held interests in two additional mining assets in Canada. Subsequent to listing, TRC’s management made the decision to dispose of its interests in the Canadian assets in order to focus its available resources on the Peak Project in Texas. TRC’s ability to raise capital is currently restricted by its lack of coverage and limited float, as well as by its limited access to institutional investors in Canada. The TRC Board believes that the domestic REE opportunity presented by the Peak Project will resonate well with investors in the larger United States market. Subject to Nasdaq listing approval, the Business Combination would represent an uplisting from the TSX-V to Nasdaq for TRC. The Business Combination represents an opportunity for TRC to raise capital, receive additional coverage and gain higher visibility among retail investors and large institutional investors.
154
• Ability to Execute on Business Plan. TRC has not yet generated any revenue from the production and sale of REEs and requires additional capital to build a processing facility at its flagship Peak Project prior to commencing commercial production. Until such time as TRC is able to generate sufficient revenue to fund its ongoing operations, it must rely on other sources of capital including the sale of new debt and equity securities. TRC’s Board believes the Business Combination, the PIPE Investment and the ability to conduct additional public and private offerings in the United States while listed on the Nasdaq will provide access to new sources of capital and allow it to continue to execute on its business plan.
• Retention of Control. TRC management will retain full operational and managerial control of PubCo, and existing TRC shareholders will retain majority voting control of PubCo. Each of the TRC Board members are nominees for the PubCo Board, which will provide for continuity in the company’s ability to execute on its business plan. In addition, the TRC Shareholders are expected to hold approximately 79.6% of the PubCo Shares following the Business Combination (not including any PubCo Shares issued in the PIPE Investment and assuming the maximum redemption scenario — see the section entitled “Unaudited Pro Forma Condensed Consolidated Financial Information” for more information).
• TRC Considered Multiple Proposals. TRC evaluated numerous different opportunities to raise growth capital and continue to fund and expand its business operations. The TRC Board determined, based on the terms of the Business Combination, its review of letters of intent from numerous other potential business combination partners, the advice of its professional advisors, and a thorough canvassing of other financing opportunities reasonably available to TRC, that the proposed Business Combination represents the best potential option fund the short and long term growth of the company.
• Increased Liquidity for Long Term Holders. TRC was founded in June 2018 and has been listed on a Canadian stock exchange since March 2022. Despite the company’s public listing, TRC’s long term shareholders have realized limited liquidity opportunities on their investments as a result of the low trading volume in Canada. The TRC Board believes a potential listing on the Nasdaq will provide its long term equity holders with increased liquidity and additional opportunities, subject to the expiration of any applicable lockup periods, to realize a return on their investment and diversify their holdings by selling some or all of their equity interests.
The TRC Board also gave consideration to certain negative factors (which are more fully described in the “Risk Factors” section of this proxy statement/prospectus).
The Plum Board’s Reasons for the Business Combination
The Plum Board, in evaluating the Business Combination, consulted with Plum’s management and legal, financial and mineral expert advisors. The Plum Board did not retain an unaffiliated representative to act solely on behalf of the Plum Public Shareholders for negotiating the terms of the Business Combination Agreement on their behalf and/or preparing a report concerning the approval of the Business Combination. The Plum Board reviewed the results of Plum management’s due diligence investigation, and the due diligence investigations of Plum’s third-party legal and financial advisors, and of Plum’s third party consultant on mineral resources and mining, and discussed the due diligence findings with Plum’s third-party legal and financial advisors, and with Plum’s third party consultant on mineral resources and mining. The Plum Board also received presentations from, and discussed with, Plum’s third-party legal, financial and mineral expert advisors regarding the transaction structure, material terms of the Business Combination and various aspects of the due diligence. In reaching its unanimous decision to (i) determine that the Business Combination is in the best interests of Plum and its shareholders, (ii) approve and declare advisable the Business Combination Agreement and the transactions contemplated thereby, including the Business Combination and the issuance of Plum Shares in connection therewith, and (iii) recommend that the Plum shareholders adopt the Business Combination Agreement, and the transactions contemplated thereby, including the Business Combination and the issuance of Plum Shares, the Plum Board considered a range of factors, including, but not limited to, the factors discussed below. In light of the number and wide variety of factors considered in connection with its evaluation of the Business Combination, the Plum Board did not consider it practicable to, and did not attempt to, quantify or otherwise assign relative weights to the specific factors that it considered in reaching its determination and supporting its decision. The Plum Board viewed its decision as being based on all of the information available and the factors presented to and considered by it. In addition, individual directors may have given different weight to different factors. This explanation of Plum’s reasons for approval of the Business Combination and all other information presented in this section is forward-looking in nature and, therefore, should be read in light of the factors discussed under “Forward-Looking Statements.”
155
Plum identified the following general criteria and guidelines that Plum believed would be important in evaluating prospective target businesses:
• Large Addressable Market: Plum would seek to invest in companies that offer room for compelling, long-term growth in their key markets. Large addressable markets have been a hallmark of Plum’s management previous successful investments. Plum believes green field or rapidly growing markets often create the largest absolute returns.
• Experienced Management Team: Seasoned and visionary management teams are necessary for success in Plum’s model. Plum intended to acquire a company with forward-thinking leaders with a demonstrated history of success, and whose interests and vision are aligned with those of our team and shareholders.
• Robust Growth Prospects: While many things must fall in place for an investment to succeed, Plum believed that growth is the primary driver of returns. Plum believed that revenue growth, not cost cutting, leverage, or other strategies, is the most important driver of long-term value.
• Strong Business Model: Plum believes business models that enable reinvestment win in the long-haul. As such, the most investable companies must show both the ability to deliver impressive cash flows and productively reinvest over the long term.
• Barriers to Entry: Real, sustainable accumulating advantages enable companies to compound value. Plum favors businesses with strong structural advantages, including various forms of network effects, aggregator dynamics, and brand, which makes it challenging for competitors to emerge.
Plum believed that TRC met and exceeded all of these criteria and guidelines, considering its large and growing market, experienced management team which had executed against multiple such opportunities and created a plan and business model that represented not only high growth, but also potential profitability in the near term. Lastly, Plum took comfort in the fact that the advanced stage and operational status of TRC’s mine represented significant barriers to other such projects from delivering similar value in the near term.
Before reaching its decision, the Plum Board also reviewed the material aspects of Plum management’s due diligence, which included:
• research on the industry, related technology, industry trends, competitive landscape and other industry factors;
• extensive meetings and calls with TRC’s management team and representatives regarding operations, business model, growth potential, competitive positioning, historical and current financials and mineral resource estimates, among other topics;
• other due diligence activities relating to accounting, legal, tax, operations and other matters;
• research on comparable public companies; and
• financial and valuation analyses, including estimates of the costs and capital expenditures for the development of TRC’s Peak Project and related cash flows.
In approving the Business Combination, the Plum Board determined not to obtain a fairness opinion or any other third party report, opinion or appraisal of the transaction. In the course of Cohen’s engagement as Plum’s financial advisor for the proposed transaction, at the request of Plum management, Cohen shared its views on key valuation metrics considered by investors, fundraising strategies, capital markets trends and conditions and other customary capital markets advice, including its views on the valuations of publicly traded comparable companies based on publicly available information. Cohen, as Plum’s financial advisor, was not engaged by Plum to provide any report, opinion or appraisal, and did not deliver a report, opinion or appraisal to Plum. Cohen did not conduct any diligence on TRC on behalf of Plum. Cohen’s support included providing market trading data on specific comparables and precedent transactions and advice on matters relating to Plum’s diligence investigation, in each case at the request of Plum management.
156
The officers and directors of Plum have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries and concluded that their collective experience, together with the experience and sector expertise of Plum’s financial advisor, enabled them to make the necessary analyses and determinations regarding the merits of the transaction.
The Plum Board considered a few factors pertaining to the Business Combination as generally supporting its decision to enter into the Business Combination Agreement and the transactions contemplated thereby, including, but not limited to, the following material factors:
• Benefits from Public Market Entry and Plum Expertise. The Plum Board considered the fact that, given the expected capital raise from private and public investments as part of the Business Combination, among other things, the cash that post-combination TRC is expected to have will allow it to be well-positioned to scale and fund its business plan.
• Shareholder Liquidity. The Plum Board considered the fact that, pursuant to the Business Combination Agreement, the Plum Shares issued as merger consideration will be listed on the Nasdaq, a major U.S. stock exchange, which the Plum Board believes has the potential to offer shareholders enhanced liquidity.
• Other Alternatives. The Plum Board has determined that, after a thorough review of other business combination opportunities reasonably available to Plum, the proposed Business Combination represents the best potential business combination for Plum and the most attractive opportunity for Plum based upon the process utilized to evaluate and assess other potential acquisition targets. The Plum Board has also determined that such process has not presented a better alternative.
• Negotiated Transaction. The Plum Board has determined that the financial and other terms of the Business Combination Agreement are reasonable and were the product of arm’s-length negotiations between Plum and TRC.
The Plum Board also considered various uncertainties and risks and other potentially negative factors concerning the Business Combination, including, but not limited to, the following:
• Exclusivity. The fact that the Business Combination Agreement includes an exclusivity provision that prohibits Plum from soliciting other business combination proposals, which restricts Plum’s ability, so long as the Business Combination Agreement is in effect, to consider other potential business combinations.
• Macroeconomic Risks. Macroeconomic uncertainty, including the impacts of changing interest rates and inflation, regulatory policy, supply chain issues and the continuing impact of the COVID-19 pandemic and the effects any of the foregoing could have on TRC’s revenues and the trading price of New Plum Common Stock.
• Business Plan May Not Be Achieved. The risk that TRC may not be able to execute on its business plan.
• Risks Associated with TRC’s Business. Risks relating to TRC’s business, including the demand, emerging use cases, market prices, and uncertainties in TRC’s estimates of rare earth elements, TRC’s ability to extract rare earth elements, and the other risk factors related to TRC set forth in this proxy statement/prospectus under the headings “Risk Factors — Risks Related to Our Business, Industry and Technology.”
• Redemption Risk. The risk that a significant number of Plum’s Public Shareholders may redeem their Public Shares for cash prior to the consummation of the Business Combination, thereby reducing the amount of cash available to TRC following the consummation of the Business Combination and making the Business Combination more difficult to complete.
• Evolving Regulatory Regime Governing Special Purpose Acquisition Companies. The risk that regulation of special purpose acquisition companies continues to evolve and the SEC, Nasdaq and other regulators may revisit and update their laws, regulations and policies.
157
• Shareholder Vote. The risk that Plum’s shareholders may object to the Business Combination and take action that may prevent or delay the consummation of the Business Combination, including failing to provide the requisite votes necessary to effect the Business Combination.
• Closing Conditions. The fact that the completion of the Business Combination is conditioned on the satisfaction of certain closing conditions that are not within Plum’s control.
• Litigation. The possibility of litigation challenging the Business Combination or an adverse judgment granting permanent injunctive relief that could indefinitely delay or enjoin consummation of the Business Combination.
• Benefits May Not Be Achieved. The risks that the potential benefits of the Business Combination may not be fully achieved or may not be achieved within the expected timeframe.
• Liquidation of Plum. The risks and costs to Plum if the Business Combination is not completed, including the risk of diverting Plum management’s focus and resources from other business combination opportunities, which could result in Plum being unable to effect a business combination and force Plum to liquidate.
• Growth Initiatives May Not be Achieved. The risk that TRC’s growth initiatives may not be fully achieved or may not be achieved within the expected timeframe.
• Plum Shareholders Receiving a Minority Position. The fact that Plum shareholders will own a minority of the voting and economic rights of New Plum following the consummation of the Business Combination.
• No Third Party Valuation. The risk that Plum did not obtain any third party report, opinion or appraisal in determining the valuation of TRC, or obtain a fairness opinion in determining whether or not to proceed with the Business Combination, because it relied on the financial skills and background of its officers and directors, and the possibility that the Plum Board may have been incorrect in its assessment of the Business Combination, including because it did not obtain any third party report, opinion or appraisal in establishing a valuation for TRC. However, as discussed above, the Plum Board believed that the officers and directors of Plum have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries and concluded that their experience and background, together with the experience and sector expertise of Plum’s financial advisor, enabled them to make the necessary analyses and determinations regarding the Business Combination.
• Fees and Expenses. The fees and expenses associated with completing the Business Combination.
• Other Risk Factors. Various other risk factors associated with the business of TRC and the Business Combination as described in the section entitled “Risk Factors” appearing elsewhere in this proxy statement/prospectus.
The Plum Board concluded that TRC met Plum’s investment criteria and that the potential benefits that it expects Plum and its shareholders to achieve as a result of the Business Combination outweigh the potentially negative factors associated with the Business Combination. Accordingly, the Plum Board unanimously determined that the Business Combination and the transactions contemplated by the Business Combination Agreement are advisable and in the best interests of Plum and its shareholders.
Satisfaction of 80% Test
It is a requirement under the Plum Articles and the Nasdaq listing requirements that the business or assets acquired in an Initial Business Combination have a fair market value equal to at least 80% of the balance of the funds in the Trust Account (excluding the deferred underwriting discounts and commissions and taxes payable on the income earned on the Trust Account) at the time of the execution of a definitive agreement for an Initial Business Combination. In connection with its evaluation and approval of the Business Combination, the Plum Board determined that the fair market value of TRC represents at least 80% of the net assets of Plum held in the Trust Account.
158
Material Effects of the Business Combination and the PIPE Investment
The following material benefits and detriments from the Business Combination and PIPE Investment are expected to affect (i) Plum and its affiliates, (ii) Sponsor and its affiliates, (iii) TRC and its affiliates, and (iv) the Public Shareholders.
Plum and its affiliates. For Plum, the Business Combination represents the opportunity to complete the purpose for which it was formed. The only potential detriment to Plum of the Business Combination is the opportunity cost — that by consummating the Business Combination, Plum is foregoing the opportunity to consummate a business combination transaction with another entity that theoretically could be of greater value to Plum than TRC. However, Plum’s board considered the benefits of the transaction with TRC and determined such transaction was the best transaction available to it at such time. The potential PIPE Investment benefits PubCo by providing it with additional capital that could fund operations and growth following the Business Combination.
Sponsors and its affiliates. For the Sponsor and Former Sponsor, the principal material benefit represented by the Business Combination is that unless the Business Combination (or another initial business combination transaction) is consummated by Plum prior to the July 30, 2025 deadline, the Sponsor and Former Sponsor will lose its entire $[•] investment in Plum (including $25,000 for the 7,062,500 Plum Founder Units and approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units). The potential PIPE Financing benefits PubCo by providing it with additional capital that could fund operations and growth, and thereby potentially further increasing the value of the Sponsor’s PubCo holdings and its return on investment following the Business Combination. The potential detriment of the PIPE Investment to the Sponsor and its affiliates is that [the up to [•]] PubCo Common Shares that may be issued to the investors in the PIPE Investment would dilute the ownership percentage of the Sponsor by between approximately [•]% (assuming no redemptions) and approximately [•]% (assuming maximum redemptions scenario).
TRC and its affiliates. For TRC and its affiliates, the Business Combination represents the opportunity to become a publicly traded company, with all the attendant benefits thereof including increased access to capital from the public markets. For TRC’s affiliates, the tradability of their PubCo Common Shares is expected to make their holdings more liquid. The potential detriments to TRC and its affiliates are the increased costs and difficulty of operating as a public company and the dilution of their ownership stake in TRC’s business of between approximately [•]% (assuming no redemptions) and approximately [•]% (assuming maximum redemptions scenario), from 100% of TRC prior to the Business Combination. The potential PIPE Investment benefits TRC by providing it with additional capital that could fund TRC’s operations and growth following the Business Combination, and thereby increase the value of TRC’s and its affiliates’ holdings and their return on investment in TRC. The potential detriment of the PIPE Investment to TRC and its affiliates is that [the up to [•]] PubCo Common Shares that may be issued to the investors in the PIPE Investment would dilute the ownership percentage of the current TRC shareholders following the Business Combination. The diluted ownership percentages referenced above include the dilution from the PIPE Investment.
Public Shareholders. For the Public Shareholders of Plum, the Business Combination represents the opportunity to share in the growth of a company such as TRC that was chosen by the management of Plum as an acquisition target in an initial business combination (which was Plum’s original purpose). Unlike the Sponsor and each of the directors and officers of Plum, if an initial business combination was not consummated by Plum within the required time period, the Public Shareholders would receive a pro-rata portion of the trust account, equivalent to their initial investment plus interest. The primary potential detriment to the Public Shareholders of the Business Combination is the dilution of their ownership stake in the combined business of between approximately [•]% (assuming no redemptions) and approximately [•]% (assuming maximum redemptions scenario), from approximately [•]% of Plum prior to the Business Combination to between approximately [•]% (assuming no redemptions) and approximately [•]% (assuming maximum redemptions scenario), not including any PubCo Common Shares that could be issued pursuant to the potential PIPE Investment. The potential PIPE Investment benefits PubCo by providing it with additional capital that could fund PubCo’s operations and growth following the Business Combination, and thereby increase the value of PubCo and the Public Shareholders’ holdings and their return on investment in Plum. The potential detriment of the PIPE Investment to the Public Shareholders is that [the up to [•] PubCo Common Shares that may be issued to the investors in the PIPE Investment would dilute the ownership percentage of the current Public Shareholders following the Business Combination by between approximately [•]% (assuming no redemptions) and approximately [•]% (assuming maximum redemptions scenario).
159
Interests of Certain Persons in the Business Combination
In considering the unanimous recommendation of the Plum Board to vote in favor of the Business Combination, Plum Public Shareholders should be aware that, aside from their interests as shareholders, Sponsor and certain members of Plum management have interests in the Business Combination that are different from, or in addition to, those of other Plum Public Shareholders generally. Plum’s directors were aware of and considered these interests, among other matters, in evaluating the Business Combination, and in recommending to Plum Shareholders that they approve the Business Combination. Plum Shareholders should take these interests into account in deciding whether to approve the Business Combination. These interests include, among other things:
• Pursuant to the Plum Articles, the Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares and have agreed to waive redemption rights with respect to any Plum Public Shares held by them in connection with the consummation of the Initial Business Combination. Additionally, Plum Founder Shareholders are not entitled to redemption rights with respect to any Plum Founder Shares held by them if Plum fails to consummate the Initial Business Combination by July 30, 2025, or such later date as approved by Plum’s shareholders. If Plum does not complete the Initial Business Combination within such applicable time period, the proceeds of the sale of the Plum Private Placement Warrants held in the Trust Account will be used to fund the redemption of the Plum Public Shares, and the Plum Private Placement Warrants will expire without the receipt of value by the holders of such warrants. Since Sponsor and Plum management directly or indirectly own Plum Common Shares and Plum Private Placement Warrants, Plum management may have a conflict of interest in determining whether a particular target business is an appropriate business with which to effectuate the Initial Business Combination;
• The fact that Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•];
• The fact that given the differential in the purchase price that Sponsor paid for the Plum Founder Shares as compared to the price of the Plum Units sold in the Plum IPO and the 3,902,648 PubCo Common Shares that Sponsor will receive upon conversion of the Plum Founder Shares in connection with the Business Combination, Sponsor and its affiliates may earn a positive rate of return on their investment even if the PubCo Common Shares trade below the price initially paid for the Plum Units in the Plum IPO and the Plum Public Shareholders experience a negative rate of return following the completion of the Business Combination;
• The fact that Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting;
• The fact that certain members of Plum management collectively own, directly or indirectly, a material interest in Sponsor;
• Sponsor and Plum management may have a conflict of interest with respect to evaluating a business combination and financing arrangements as Plum may obtain loans from Sponsor or an affiliate of Sponsor or any of Plum management to finance transaction costs in connection with the Initial Business Combination;
• The Plum Articles provide that Plum renounces any interest or expectancy in, or in being offered an opportunity to participate in, any potential transaction or matter which may be a corporate opportunity for any member of Plum management on the one hand, and Plum, on the other hand, or the participation of which would breach any existing legal obligation, under applicable law or otherwise, of a member of Plum management to any other entity. Plum is not aware of any such corporate opportunities not being offered to Plum and does not believe that waiver of the corporate opportunities doctrine has materially affected Plum’s search for an acquisition target or will materially affect Plum’s ability to complete an Initial Business Combination;
160
• If the Trust Account is liquidated, including in the event Plum is unable to complete an Initial Business Combination within the required time period, Sponsor has agreed to indemnify Plum to ensure that the proceeds in the Trust Account are not reduced below $10.00 per Plum Public Share, or such lesser amount per Plum Public Share as is in the Trust Account on the liquidation date, by the claims of (a) any third party (other than Plum’s independent public accountants) for services rendered or products sold to Plum or (b) a prospective target business with which Plum has entered into a letter of intent, confidentiality or other similar agreement or business combination agreement, but only if such a third party or target business has not executed a waiver of all rights to seek access to the Trust Account;
• The fact that Plum has borrowed certain amounts from the Sponsor pursuant to (i) the Working Capital Note which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the Sponsor Warrants for Working Capital Note at a price of $1.50 per warrant, to be issued at Closing, and (ii) a promissory note, as amended, which provides for up to $100,000 in working capital loans, which shall be repaid in cash on the earlier of (i) consummation of the Plum’s initial merger, share exchange, asset acquisition, share purchase, recapitalization, reorganization or similar business combination with one or more businesses or entities, (ii) the date of the liquidation of Plum or (iii) 270 calendar days.
• The fact that Sponsor will benefit from the completion of an Initial Business Combination and may be incentivized to complete an acquisition of a less favorable target company or on terms less favorable to Plum Shareholders rather than liquidate;
• The fact that PubCo will indemnify Sponsor and its affiliates and their respective present and former directors and officers for a period of six years from the Closing, in connection with any claim, action, suit, proceeding or investigation arising out of or pertaining to the Business Combination and Sponsor’s ownership of Plum Securities or its control or ability to influence Plum; and
• The terms and provisions of the Related Agreements as set forth in detail under the subsection entitled “The Business Combination — Related Agreements.”
In addition, members of TRC’s board of directors, management and various service providers of TRC have numerous contractual relationships with TRC of which the TRC board of directors was aware when it approved TRC entering into the Business Combination Agreement. Therefore, these individuals may have conflicts of interest in entering into and negotiating the terms of the Business Combination Agreement. For a complete description of these relationships, see “Certain Relationships and Related Transactions — TRC Relationships and Related Party Transactions”.
The table set forth below summarizes the existing interests in Plum private placement securities and the anticipated interests of Former Sponsor, Sponsor, Plum management, and the lender under a subscription agreement in PubCo as of Closing along with the value of such interests based on (i) in the case of Sponsor’s and Plum management’s interests, the closing price of the Plum Public Warrants and Plum Class A Shares as of [•], 2025, which would be lost if an Initial Business Combination is not completed by Plum by the Deadline Date, and (ii) the transaction value:
|
Name of Holder |
Type of |
Total |
Number of |
Number of |
Value of |
Number of |
Number of |
Value of |
|||||||||
|
Mercury Capital, LLC(1) |
Sponsor |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Alpha Partners Technology Merger Sponsor, LLC(2) |
Former Sponsor |
$ |
6,675,000 |
665,000 |
221,667 |
1,128,992 |
376,331 |
||||||||||
|
Palmeira Investment Limited(3) |
Lender to Sponsor |
$ |
750,000 |
0 |
0 |
637,500 |
0 |
||||||||||
|
Kanishka Roy(4) |
CEO & Chairman |
$ |
1 |
0 |
0 |
4,964,828 |
1,867,443 |
||||||||||
|
Steven Handwerker |
CFO |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Hume Ky le |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
Alan Black |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
|
David Sable |
Director |
$ |
0 |
0 |
0 |
0 |
0 |
||||||||||
__________
(1) On December 27, 2023, Plum, Alpha Partners Technology Merger Sponsor, LLC, and Mercury Capital, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which Mercury Capital, LLC the Sponsor (i) purchased 3,902,648 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to
161
acquire one Class B share, and (ii) became entitled to 70% of the 2,030,860 Founder Units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such Founder Units are not allocated to investors who hold and do not redeem their Class A Shares of Plum at the time of Plum’s initial business combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(2) Alpha Partners Technology Merger Sponsor, LLC paid an aggregate of $25,000 for 7,187,500 Founder Units, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B share, 125,000 of which were forfeited due to only a partial exercise of the over-allotment option. Additionally, Alpha Partners Technology Merger Sponsor, LLC purchased 665,000 private placement units at an aggregate price of $6,650,000. On December 27, 2023, Alpha Partners Technology Merger Sponsor, LLC entered into a purchase agreement (“Purchase Agreement”), pursuant to which they sold 3,902,648 Founder Units to Mercury Capital, LLC, and put 2,030,860 Founder Units into escrow, of which they are entitled to 30% of the Founder Units in Escrow if they are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of the Company’s initial Business Combination. All the Founder Units in escrow are accounted for under Mercury Capital, LLC’s interests.
(3) Palmeira Investment Limited and Mercury Capital, LLC are party to a subscription agreement, dated January 3, 2024, pursuant to which Mercury Capital, LLC may raise funds to pay for extension payments and working capital on behalf of Plum Acquisition Corp. III. Pursuant to the terms of the subscription agreement, Mercury Capital, LLC will forfeit 0.85 Class B Shares for every $1.00 loaned under the agreement and cause Plum Acquisition Corp. III to issue such number of shares forfeited to Palmeira Investment Limited upon closing of the business combination. As of Mercury Capital LLC’s last drawdown under the subscription agreement, Palmeira Investment Limited had loaned $750,000 to Mercury Capital, LLC under the subscription agreement.
(4) Kanishka Roy serves as manager for Mercury Capital, LLC and may be deemed to beneficially own shares held by Mercury Capital, LLC by virtue of his control over Mercury Capital, LLC. Mr. Roy disclaims beneficial ownership of such shares other than to the extent of his pecuniary interest in such shares.
The Sponsor will not receive any direct compensation for services rendered in connection with the Business Combination. Sponsor beneficially owns an aggregate of 1,867,443 Plum Founder Warrants, after separating the Founder Units into shares and warrants, that would expire worthless if an Initial Business Combination is not consummated, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Public Warrants of $[•] per warrant on [•], 2025, the record date for the Plum Shareholders’ Meeting. Former Sponsor paid an aggregate of approximately $25,000 for the 7,062,500 Plum Founder Units and Sponsor paid approximately $1 to Former Sponsor for 3,902,648 Plum Founder Units. These securities will have a significantly higher value at the time of the Business Combination, which if unrestricted and freely tradable would be valued at approximately $[•], based on the closing price of the Plum Class A Shares of $[•] per share on [•], 2025, the record date for the Plum Shareholders’ Meeting, resulting in a theoretical gain of $[•]. Since all Founder Units have been issued, this compensation will not result in a material dilution to the equity interests of non-redeeming shareholders upon consummation of the Business Combination.
Plum has borrowed certain amounts from the Sponsor pursuant to (i) a promissory note (the “Working Capital Note”) which provides for up to $2,200,000 in working capital loans, and such borrowed amounts may be repaid, at the option of the Sponsor, in the form of PubCo Warrants (the “Sponsor Warrants for Working Capital Note”) at a price of $1.50 per warrant, to be issued at Closing, and (ii) a promissory note, as amended, which provides for up to $100,000 in working capital loans, which shall be repaid in cash on the earlier of (i) consummation of the Plum’s initial merger, share exchange, asset acquisition, share purchase, recapitalization, reorganization or similar business combination with one or more businesses or entities, (ii) the date of the liquidation of Plum or (iii) 270 calendar days. The warrants that may be issuable pursuant to the promissory note to the Sponsor at Closing as reimbursement, if exercised, would result in the issuance of up to 1,466,667 additional Plum Class A Ordinary Shares upon Closing. See “Notes to Unaudited Pro Forma Condensed Consolidated Financial Information” for further information on the dilution. Assuming that all Plum Public Warrants and Plum Private Placement Warrants are exercised, this compensation will not result in a material dilution of the equity interests of non-redeeming Plum Public Shareholders.
Potential Purchases of Public Shares
In connection with the Plum Shareholder vote to approve the Business Combination, Sponsor, Plum management, Plum’s advisors or any of their respective affiliates may privately negotiate transactions to purchase Plum Public Shares from Plum Shareholders who would have otherwise elected to have their shares redeemed in conjunction with the Business Combination for a per share pro rata portion of the Trust Account. There is no limit on the number of Plum Public Shares Sponsor, Plum management, Plum’s advisors or any of their respective affiliates may purchase in such transactions, subject to compliance with applicable law and the rules of the NASDAQ. Any such privately
162
negotiated purchases may be effected at purchase prices that are no higher than the per share pro rata portion of the Trust Account. However, Sponsor, Plum management, Plum’s advisors and their respective affiliates have no current commitments, plans or intentions to engage in such transactions and have not formulated any terms or conditions for any such transactions. None of the funds in the Trust Account will be used to purchase Plum Public Shares in such transactions. None of Sponsor, Plum management, Plum’s advisors or any of their respective affiliates will make any such purchases when they are in possession of any material non-public information not disclosed to the seller of such Plum Public Shares or during a restricted period under Regulation M under the Exchange Act or other federal securities laws. Such a purchase could include a contractual acknowledgement that such Plum Shareholder, although still the record holder of such Plum Public Shares, is no longer the beneficial owner thereof and therefore agrees not to exercise its redemption rights. Any Plum Public Shares purchased by Sponsor, Plum management, Plum’s advisors or any of their respective affiliates would not be voted in favor of approving the Business Combination.
In the event that Sponsor, Plum management, Plum’s advisors or any of their respective affiliates purchase Plum Public Shares in privately negotiated transactions from public Plum Shareholders who have already elected to exercise their redemption rights, such selling shareholders would be required to revoke their prior elections to redeem their shares. In addition, Sponsor, Plum management, Plum’s advisors or any of their respective affiliates would waive any redemption rights with respect to any Plum Public Shares that they purchase in any such privately negotiated transactions.
The purpose of any such purchases of Plum Public Shares could be to satisfy a closing condition in the Business Combination Agreement, where it appears that such requirement would otherwise not be met. Any such purchases of Plum Public Shares may result in the completion of the Business Combination that may not otherwise have been possible. Any such purchases will be reported pursuant to Section 13 and Section 16 of the Exchange Act to the extent the purchasers are subject to such reporting requirements. In addition, to the extent that Sponsor, Plum management, Plum’s advisors or any of their respective affiliates purchase any Plum Public Shares as contemplated above, Plum will file a Current Report on Form 8-K prior to the Plum Shareholders’ Meeting that will disclose:
• the amount of such Plum Public Shares purchased by Sponsor, Plum management, Plum’s advisors or any of their respective affiliates, along with the purchase price;
• the purpose of the purchases by Sponsor, Plum management, Plum’s advisors or any of their respective affiliates;
• the impact, if any, of the purchases by Sponsor, Plum management, Plum’s advisors or any of their respective affiliates on the likelihood that the Business Combination will be approved;
• the identities of Plum Shareholders who sold to Sponsor, Plum management, Plum’s advisors or any of their respective affiliates (if not purchased on the open market) or the nature of Plum Shareholders (e.g., 5% security holders) who sold to Sponsor, Plum management, Plum’s advisors or any of their respective affiliates; and
• the number of Plum Public Shares for which Plum has received redemption requests in connection with the Business Combination.
In addition, if such purchases are made, the public “float” of the Plum Class A Shares or PubCo Common Shares may be reduced and the number of beneficial holders of Plum’s or PubCo’s securities may be reduced, which may make it difficult to maintain or obtain the quotation, listing or trading of Plum’s or PubCo’s securities on a national securities exchange.
Sponsor, and Plum’s officers, directors, advisors or any of their respective affiliates anticipate that they may identify the shareholders with whom Sponsor, Plum’s officers, directors, advisors or any of their respective affiliates may pursue privately negotiated purchases by either the shareholders contacting Plum directly or by Plum’s receipt of redemption requests submitted by shareholders.
Any purchases by Sponsor, Plum’s officers, directors, advisors or any of their respective affiliates who are affiliated purchasers under Rule 10b-18 under the Exchange Act will only be made to the extent such purchases are able to be made in compliance with Rule 10b-18, which is a safe harbor from liability for manipulation under Section 9(a)(2) of and Rule 10b-5 under the Exchange Act. Rule 10b-18 has certain technical requirements that must be complied with in order for the safe harbor to be available to the purchaser. Sponsor, Plum’s officers, directors, advisors and any of their respective affiliates will not make purchases of Plum Class A Shares if the purchases would violate Section 9(a)(2) of or Rule 10b-5 under the Exchange Act.
163
Redemption Rights
Pursuant to the Plum Articles, a Plum Public Shareholder may request that Plum redeem all or a portion of its Plum Public Shares for cash if the Business Combination is consummated. As a Plum Public Shareholder, you will be entitled to exercise your redemption rights if you:
(a) hold Plum Public Shares, or if you hold Plum Units, you elect to separate your Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising your redemption rights;
(b) submit a written request to Continental Stock Transfer & Trust Company, the Transfer Agent, in which you (i) request the exercise of your redemption rights with respect to all or a portion of your Plum Public Shares for cash, and (ii) identify yourself as the beneficial holder of the Plum Public Shares and provide your legal name, phone number and address; and
(c) deliver your Plum Public Shares to the Transfer Agent, physically or electronically through DTC.
Holders must complete the procedures for electing to redeem their Plum Public Shares in the manner described above prior to 10:30 a.m., Eastern Time, on [•], 2025 (two business days before the Plum Shareholders’ Meeting) in order for their shares to be redeemed.
Holders of Plum Units must elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants prior to exercising their redemption rights with respect to the Plum Public Shares. If Plum Public Shareholders hold their Plum Units in an account at a brokerage firm or bank, such Plum Public Shareholders must notify their broker or bank that they elect to separate the Plum Units into the underlying Plum Public Shares and Plum Public Warrants, or if a holder holds Plum Units registered in its own name, the holder must contact the Transfer Agent directly and instruct it to do so. The redemption rights include the requirement that a holder must identify itself to Plum in order to validly exercise its redemption rights. Plum Public Shareholders may elect to exercise their redemption rights with respect to their Plum Public Shares even if they vote “FOR” the Business Combination Proposal. If the Business Combination is not consummated, the Plum Public Shares will be returned to the respective holder, broker or bank. If the Business Combination is consummated, and if a Plum Public Shareholder properly exercises its redemption rights with respect to all or a portion of the Plum Public Shares that it holds and timely delivers its shares to the Transfer Agent, PubCo will redeem the related PubCo Common Shares for a per share price, payable in cash, equal to the pro rata portion of the Trust Account, including interest earned on the funds held in the Trust Account and not previously released to Plum to fund regulatory withdrawals or to pay its taxes, calculated as of two business days prior to the consummation of the Business Combination. For illustrative purposes, as of [•], 2025, this would have amounted to approximately $[•] per issued and outstanding Plum Public Share. If a Plum Public Shareholder exercises its redemption rights in full, then it will not own Plum Public Shares or PubCo Common Shares following the redemption. The redemption will take place following the TRC Amalgamation, and, accordingly, it is PubCo Common Shares that will be redeemed as promptly as practical after the TRC Amalgamation Effective Time. Please see the subsection entitled “Extraordinary General Meeting of Plum Shareholders — Redemption Rights” elsewhere in this proxy statement/prospectus for a detailed description of the procedures to be followed if you wish to exercise your redemption rights with respect to your Plum Public Shares.
PIPE Investments
In connection with the Business Combination, we, TRC and PubCo have agreed to consummate an offering of PubCo Common Shares to certain PIPE Investors in a separate private placement transaction. The PIPE Investment will be consummated pursuant to one or more PIPE Subscription Agreements with PIPE Investors for the purchase of PubCo Common Shares in exchange for cash payable to PubCo concurrently with the Closing. The terms and conditions of the PIPE Investment have yet to be determined and are subject to negotiation between us, TRC, PubCo and the PIPE Investors. This proxy statement/prospectus does not constitute an offer to sell nor is soliciting an offer to buy any securities in connection with the PIPE Investment.
164
Total PubCo Common Shares to Be Issued in the Business Combination
The issuance of PubCo Common Shares in the Business Combination will dilute the equity interests of Plum Public Shareholders who do not exercise their redemption rights and may adversely affect prevailing market prices for PubCo Common Shares. Plum Public Shareholders who do not exercise their redemption rights may experience dilution to varying degrees in connection with and after the Business Combination, including:
• the issuance of PubCo Common Shares as part of the consideration in connection with the consummation of the Business Combination;
• the exercise of Plum Warrants;
• the exercise of TRC Options;
• the exercise of TRC Warrants;
• the conversion of TRC Convertible Debt;
• the issuance of PubCo Common Shares in the PIPE;
• the issuance of PubCo Common Shares to Investment Banks;
• the TRC RSUs; and
• the issuance of PubCo Common Shares under the Incentive Plan.
The issuance of PubCo Common Shares in connection with the Business Combination, including through any of the foregoing, could have the following effects for Plum Public Shareholders who elect not to redeem their Public Shares:
• their proportionate ownership interest in TRC will decrease;
• the amount of cash available per share, including for payment of dividends in the future, may decrease;
• the relative voting strength of each previously outstanding Plum Shares will be diminished; or
• the market price of PubCo Common Shares or TRC Warrants, as applicable, may decline.
The following table illustrates varying beneficial ownership levels in TRC, as well as possible sources and extents of dilution for non-redeeming Plum Public Shareholders, assuming no additional redemptions by Plum Public Shareholders and the Maximum Redemption by Plum Public Shareholders. The calculations are based upon an assumed TRC Exchange Ratio of 0.87084460.
Assumptions are as follows:
• Assuming no additional redemption scenario: This presentation assumes that no Public Shareholders exercise redemption rights with respect to their Public Shares in connection with the vote on the Business Combination.
165
• Assuming Maximum Redemption scenario: This presentation assumes that the Public Shareholders holding approximately 14.9% of the Public Shares exercise redemption rights with respect to their Public Shares. This scenario assumes that 151,833 Public Shares are redeemed for an aggregate redemption payment of approximately $1,711,089 plus a pro rata portion of interest accrued on the Trust Account (net of taxes payable).
|
No |
% |
Maximum |
% |
|||||||||
|
Plum Public Shareholders(1) |
|
1,016,833 |
1.3 |
% |
|
865,000 |
1.2 |
% |
||||
|
Sponsor and Former Sponsor(2)(3) |
|
6,731,320 |
8.3 |
% |
|
6,731,320 |
8.3 |
% |
||||
|
Parties to Non-redemption Agreements(3) |
|
331,180 |
0.4 |
% |
|
331,180 |
0.4 |
% |
||||
|
Plum Public Warrants(4) |
|
9,416,666 |
11.6 |
% |
|
9,416,666 |
11.6 |
% |
||||
|
Plum Founder Warrants and Private Placement Warrants(5) |
|
2,642,500 |
3.3 |
% |
|
2,642,500 |
3.3 |
% |
||||
|
Sponsor Warrants for Working Capital Note(6) |
|
969,911 |
1.2 |
% |
|
969,911 |
1.2 |
% |
||||
|
TRC public shareholders(7) |
|
35,073,456 |
43.2 |
% |
|
35,073,456 |
43.3 |
% |
||||
|
TRC option holders(8) |
|
2,085,673 |
2.6 |
% |
|
2,085,673 |
2.6 |
% |
||||
|
TRC RSUs(9) |
|
3,104,561 |
3.8 |
% |
|
3,104,561 |
3.8 |
% |
||||
|
TRC Warrantholders(10)(11) |
|
6,406,368 |
7.9 |
% |
|
6,406,368 |
7.9 |
% |
||||
|
TRC Convertible Debt(11) |
|
3,918,801 |
4.8 |
% |
|
3,918,801 |
4.8 |
% |
||||
|
Bank Shares(12) |
|
1,188,950 |
1.5 |
% |
|
1,188,950 |
1.5 |
% |
||||
|
TRC Incentive Plan(13) |
|
8,229,736 |
10.1 |
% |
|
8,214,553 |
10.1 |
% |
||||
|
Total |
|
81,115,955 |
|
|
80,948,939 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted(14) |
$ |
7.43 |
|
$ |
7.39 |
|
||||||
|
Implied Per Share Value issued, outstanding and fully diluted (excluding shares issued to redeemable shareholders)(15) |
$ |
7.44 |
|
$ |
7.40 |
|
||||||
____________
(1) Outstanding share numbers take into account the redemptions of 28,098,167 Plum Class A Shares that occurred in connection with extensions of Plum’s business combination deadline.
(2) On December 27, 2023, Plum, the Former Sponsor, and Sponsor entered into a purchase agreement (the “Purchase Agreement”), pursuant to which Sponsor (i) purchased 3,902,648 founder units of Plum from the Former Sponsor, each unit consisting of one Class B ordinary share and one-third of one redeemable warrant to acquire one Class B ordinary share, which founder units are subject to forfeiture in certain circumstances, and (ii) became entitled to 70% of the 2,030,860 founder units that Former Sponsor placed in escrow at the closing of the Purchase Agreement to the extent such founder units are not allocated to investors who hold and do not redeem their Plum Class A Shares at the time of Plum’s initial business combination. Pursuant to the Amended Purchase Agreement, the Former Sponsor shall retain 665,000 Class A private placement units and 1,128,992 Class B founder units. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(3) At Closing, 331,180 Ordinary Shares that would have otherwise been issued to the Sponsor in exchange for such number of shares Plum Class A Shares will instead to be issued to the parties to whom the Sponsor has agreed to transfer such shares. The agreement to transfer such shares was made in consideration of each of the transferees agreeing not to redeem their Plum Class A Shares on connection with the extension of Plum’s business combination deadline.
(4) The Plum Public Warrants are exercisable at $11.50 per share.
(5) The 2,354,166 Plum Founder Warrants and 288,334 Plum Private Warrants are exercisable at $11.50 per share. Pursuant to the Sponsor Support Agreement, up to 2,030,860 founder units are forfeitable upon the closing of the Business Combination.
(6) Assumes $1,454,867 is outstanding on the convertible note held by the Sponsor, convertible into PubCo Warrants at closing at $1.50 per Warrant.
(7) 35,674,480 TRC Common Shares are currently outstanding.
(8) 2,395,000 options to purchase TRC Common Shares are currently outstanding, exercisable at C$0.10 per share.
(9) 3,565,000 RSUs to acquire TRC Common Shares are currently outstanding, and will vest upon the closing of the Business Combination.
(10) 2,856,500 Warrants to purchase TRC Common Shares are currently outstanding, exercisable at C$2.50 per share.
(11) C$200,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,000,000 TRC Common Shares plus 2,000,000 warrants to purchase 2,000,000 TRC Common Shares at C$0.15 per share. C$500,000 in principal amount of TRC Convertible Debentures is currently outstanding, which is convertible into 2,500,000 TRC Common Shares plus 2,500,000 warrants to purchase 2,500,000 TRC Common Shares at C$0.20 per share.
166
Any accrued and unpaid interest may, in TRC’s sole discretion, be paid in cash or in units (consisting of one TRC Common Share and one warrant to purchase a TRC Common Share) at a conversion price equal to the last closing market price of TRC’s common shares on the TSX-V immediately prior to such conversion date, subject to the policies of the TSX-V.
(12) TRC will be obligated to issue 1,188,950 shares to its investment bankers in connection with the Transactions.
(13) TRC’s board of directors has approved the Incentive Plan providing for the issuance of ten percent of the outstanding PubCo Common Shares, on a fully diluted basis, immediately following the closing, plus 1,000,000 shares.
(14) Calculation of implied per share value assumes an enterprise value of $602.5 million of PubCo upon consummation of the Business Combination and a fully diluted share count with no redemptions of 81,115,955.
(15) Calculation of implied per share value assumes an enterprise value of $599.2 million of PubCo upon consummation of the Business Combination and a fully diluted share count with max redemptions of 80,948,939.
Assuming no further redemptions of the Plum Shares, the combined company would have a pro forma valuation of approximately $811,159,550 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
Assuming maximum redemptions of the Plum Shares issued in our IPO, the combined company would have a pro forma valuation of approximately $809,489,390 at an assumed price of $10.00 per share and the securities issued to TRC Public Shareholders would have a value of approximately $350,734,560 at an assumed price of $10.00 per share.
The calculations in the paragraphs above reflect certain qualifications and assumptions. See “Unaudited Pro Forma Condensed Combined Financial Information.”
Impact of Substantial Redemptions on the Business Combination
Plum Public Shareholders are not required to vote “Against” the Business Combination in order to exercise their redemption rights. Accordingly, the Business Combination may be consummated even though the funds available from the Trust Account and the number of Plum Public Shareholders are reduced as a result of redemptions by Plum Public Shareholders.
If a Plum Public Shareholder exercises its redemption rights, such exercise will not result in the loss of any Plum Warrants that it may hold. Assuming that 151,833 PubCo Common Shares held by Plum Public Shareholders were redeemed, the 9,416,666 retained outstanding PubCo Warrants would be valued at approximately $[•] based on the closing price of Plum Public Warrants of $[•] per warrant on [•], 2025. If a substantial number of, but not all, Plum Public Shareholders exercise their redemption rights, any non-redeeming Plum Shareholders would experience dilution to the extent such PubCo Warrants are exercised and additional PubCo Common Shares are issued.
Sources and Uses for the Business Combination
The following tables summarize the illustrative sources and uses for funding the Business Combination (i) assuming that no PubCo Common Shares are redeemed in connection with the Business Combination and (ii) assuming that 151,833 PubCo Common Shares are redeemed in connection with the Business Combination.
No Redemption
|
Sources |
USD |
||
|
Cash in Trust Account(1) |
$ |
1,711,089 |
|
|
Equity issued to current TRC Shareholders(2) |
$ |
500,000,000 |
|
|
Total Sources |
$ |
501,711,089 |
|
|
Uses |
USD |
|||
|
Equity issued to current TRC Shareholders(2) |
$ |
500,000,000 |
|
|
|
Estimated non-equity transaction costs(3) |
$ |
13,025,000 |
|
|
|
Liability added to company Balance Sheet(4) |
$ |
(11,313,911 |
) |
|
|
Total Uses |
$ |
501,711,089 |
|
|
167
Maximum Redemption
|
Sources |
USD |
||
|
Cash in Trust Account(5) |
$ |
0 |
|
|
Equity issued to current TRC Shareholders(2) |
$ |
500,000,000 |
|
|
Total Sources |
$ |
500,000,000 |
|
|
Uses |
USD |
|||
|
Equity issued to current TRC Shareholders(2) |
$ |
500,000,000 |
|
|
|
Estimated non-equity transaction costs(3) |
$ |
13,025,000 |
|
|
|
Liability added to company Balance Sheet(6) |
$ |
(13,025,000 |
) |
|
|
Total Uses |
$ |
500,000,000 |
|
|
____________
(1) Assuming no redemptions, the cash remaining in the Trust Account is $1,711,089.
(2) PubCo shares to be issued to TRC Shareholders of 50,000,000 at $10.00 per share.
(3) Estimated Transaction Costs of $13,025,000 is composed of Legal Fees of $6,300,000, Banker Fees of $4,000,000, Director & Officer Insurance Fees of $700,000, Regulatory and Miscellaneous Fees of $650,000, Audit & Accounting Fees of $900,000, and Investor Relations Fees of $475,000.
(4) Amount is derived from subtracting the cash remaining in the Trust Account assuming no redemptions of $1,711,089 from the Estimated Transaction Costs of $13,025,000. Given the amount is negative, the Company will accrue the resulting liability on its balance sheet.
(5) Assuming 100% redemptions, the cash remaining in the Trust Account is $nil.
(6) Amount is derived from subtracting the cash remaining in the Trust Account assuming 100% redemptions of $nil from the Estimated Transaction Costs of $13,025,000. Given the amount is negative, the Company will accrue the resulting liability on its balance sheet.
Certain Information Relating to PubCo
PubCo/PubCo Board Before the Business Combination
Prior to the consummation of the Plum Amalgamation, the PubCo Board consists of Kanishka Roy and Steven Handwerker. In connection with the TRC Amalgamation, Ranjeet Sundher, Kuljit Basi, Matthew Chatterton, Manavdeep Mukhija and J. Garry Clark will become the members of the PubCo Board
PubCo Board and Executive Officers Following the Business Combination
The executive officers and directors of PubCo following the TRC Amalgamation will be as follows:
|
Name |
Age |
Position |
||
|
Ranjeet Sunder |
58 |
Chief Executive Officer and Director |
||
|
Kuljit Basi |
41 |
Executive Chairman and Director |
||
|
Alnesh Mohan |
53 |
Chief Financial Officer |
||
|
Matthew Chatterton |
44 |
Director |
||
|
Manavdeep Mukhija |
38 |
Director |
||
|
J. Garry Clark |
64 |
Director |
It is anticipated that Matthew Chatterton, Manavdeep Mukhija and J. Garry Clark will be independent under the applicable rules of the SEC and the NASDAQ.
In connection with the TRC Amalgamation, it is expected that (i) each of the officers and directors listed above will hold the indicated offices and (ii) each of the director nominees listed above will become members of the PubCo Board. Please see the section entitled “Management of PubCo After the Business Combination” elsewhere in this proxy statement/prospectus for biographies and additional information.
Employment and Compensation Arrangements
PubCo expects that prior to the consummation of the Business Combination, TRC’s executive officers will continue to be employed by TRC. After consummation of the Business Combination and once PubCo’s compensation committee is formed, executive compensation decisions will be made by the PubCo Board based
168
on recommendations made by PubCo’s compensation committee. PubCo’s compensation committee will review executive compensation arrangements and recommend to the PubCo Board any adjustments that it believes are appropriate in structuring PubCo’s executive compensation arrangements.
Please see the section entitled “Executive Compensation” elsewhere in this proxy statement/prospectus for additional information.
Indemnification and Insurance Obligations of PubCo Following the Business Combination
Under Section 160 of the BCBCA, PubCo may indemnify an individual who (i) is or was a director or officer of PubCo, (ii) is or was a director or officer of another corporation at a time when the corporation is or was an affiliate of the copay or at the request of the company, or (iii) at the request of the company holds or held a position equivalent to that of a director or officer of a partnership, trust, joint venture or other unincorporated entity (collectively, “Indemnified Persons”) against judgments, penalties or fines awarded, or amounts paid in settlement of, proceedings in which such Indemnified Person is involved by reason of being or having been director or officer of PubCo, and all costs, charges, expenses reasonably incurred by such person in respect of such proceedings if (i) the indemnity or payment is made under an earlier agreement to indemnify and, at the time such agreement was made or at the time the indemnity or payment is made, PubCo was not prohibited from giving the indemnity or paying the expenses, (ii) the Indemnified Person acted honestly and in good faith with a view to the best interests of PubCo, and (iii) in the case of a criminal or administrative action or proceeding that is enforced by a monetary penalty, the Indemnified Person had reasonable grounds for believing that such Indemnified Person’s conduct was lawful (collectively, the “Indemnification Conditions”).
PubCo may pay, as they are incurred in advance to a final disposition of such a proceeding in which such Indemnified Person is involved by reason of being or having been a director or officer of PubCo, the costs, charges, and expenses actually and reasonably incurred by the Indemnified person in respect of such a proceeding; however, the Indemnified Person must repay the funds if the Indemnified Person does not fulfill the Indemnification Conditions.
Notwithstanding the foregoing, the BCBCA provides that on the application of PubCo or an Indemnified Party, the court may (i) order PubCo to indemnify the Indemnified Party against any liability incurred in respect of a proceeding, (ii) order PubCo to pay some of all of the costs, charges and expenses incurred in respect of a proceeding, (iii) order the enforcement of or payment under an indemnification agreement entered into by PubCo, (iv) order PubCo to pay some or all of the expenses actually and reasonably incurred in obtaining such an order and (v) make any other order the court considers appropriate.
As permitted by the BCBCA, PubCo’s articles will require that an indemnifiable person be entitled to indemnity from PubCo in respect of judgments, penalties or fines awarded or imposed in, or amounts paid in settlement of, proceedings in which the indemnifiable person is involved by reason of being or having been a director or officer of the corporation or body corporate, and all costs, charges, expenses reasonably incurred by such person in respect of such proceedings. Each indemnifiable party is deemed to have contracted with PubCo on the terms of the indemnity in PubCo’s articles.
In addition, PubCo’s articles will provide that PubCo may agree to indemnify and may indemnify any person against eligible penalties and pay expenses incurred in connection with the performance of services by that person for PubCo. PubCo’s articles will also specify that failure of an eligible party to comply with the provisions of the BCBCA or PubCo’s articles will not invalidate any indemnity to which he or she is entitled. Because PubCo’s articles will require that indemnification be subject to the BCBCA, any indemnification that PubCo provides is subject to the same restrictions set out in the BCBCA which are summarized, in part, above.
PubCo may also, pursuant to the PubCo articles and BCBCA, purchase and maintain insurance for each director and officer against any liability incurred by the director or officer as a result of their holding office in PubCo or a related body corporate.
Please see the subsection entitled “Management of PubCo After the Business Combination — PubCo Board — Indemnification and Insurance Obligations of PubCo Following the Business Combination” elsewhere in this proxy statement/prospectus for additional information.
169
Listing of PubCo Common Shares and PubCo Warrants on the NASDAQ
PubCo Common Shares and PubCo Warrants currently are not traded on a stock exchange. PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing the PubCo Common Shares and PubCo Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively. Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX-V, and TRC will apply to have TRC cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
Restrictions on Resales
All PubCo Common Shares and PubCo Warrants received by Plum Shareholders and warrantholders in the Business Combination are expected to be freely tradable, except that the PubCo Common Shares and PubCo Warrants received in the Business Combination by persons who become affiliates of PubCo for purposes of Rule 144 under the Securities Act may be resold by them only in transactions permitted by Rule 144, or as otherwise permitted under the Securities Act. Persons who may be deemed affiliates of PubCo generally include individuals or entities that control, are controlled by or are under common control with, PubCo and may include the directors and executive officers of PubCo as well as its principal shareholders.
All PubCo Common Shares and PubCo Warrants received by Plum Shareholders and warrantholders in the Business Combination will not be legended and may be resold in each of the provinces and territories of Canada, provided that: (i) PubCo is and has been a reporting issuer in a jurisdiction of Canada for the four months immediately preceding the trade (subject to the abridgment of such four month period upon PubCo becoming a reporting issuer by filing a non-offering prospectus in the Province of British Columbia); (ii) the trade is not a “control distribution” (as defined in National Instrument 45-102 — Resale of Securities of the Canadian Securities Administrators (“NI 45-102”)); (iii) no unusual effort is made to prepare the market or create a demand for those securities; (iv) no extraordinary commission or consideration is paid in respect of that trade; and (v) if the selling securityholder is an insider or officer of PubCo (as defined under applicable Canadian securities legislation), the insider or officer has no reasonable grounds to believe that PubCo is in default of applicable Canadian securities legislation. Each holder of PubCo Common Shares is urged to consult the holder’s professional advisors with respect to applicable restrictions.
Delisting of Plum Common Shares and Deregistration of Plum
Plum, TRC and PubCo anticipate that, following consummation of the Business Combination, the Plum Class A Shares, Plum Units and Plum Warrants will be no longer qualified on the OTC Pink, and Plum will be deregistered under the Exchange Act.
Comparison of Corporate Governance and Shareholder Rights
Until the Domestication, Cayman Islands law and the Plum Articles will continue to govern the rights of Plum Shareholders. After the Domestication, but before the Plum Amalgamation, British Columbia law and the Domestication Articles will govern the rights of Plum Shareholders. After the consummation of the Plum Amalgamation, Plum Shareholders will become PubCo Shareholders and British Columbia law and the PubCo Articles will govern the rights of the PubCo Shareholders. After the consummation of the TRC Amalgamation, British Columbia law and the PubCo Closing Articles will govern the rights of PubCo Shareholders.
There are certain differences in the rights of Plum Shareholders prior to the Business Combination and the rights of PubCo Shareholders after the Business Combination. Please see the section entitled “Comparison of Corporate Governance and Shareholder Rights” elsewhere in this proxy statement/prospectus for additional information.
Regulatory Matters
Please see the section entitled “Regulatory Approvals Related to the Business Combination” elsewhere in this proxy statement/prospectus.
170
Material Tax Considerations with Respect to the Business Combination and Ownership of PubCo Securities
Please see the sections entitled “Material U.S. Federal Income Tax Considerations for U.S. Holders” and “Material Canadian Tax Considerations” elsewhere in this proxy statement/prospectus.
Anticipated Accounting Treatment of the Business Combination
The Business Combination will be accounted for as a “reverse recapitalization” in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). Under this method of accounting, PubCo will be treated as the “acquired” company for financial reporting purposes. This determination is primarily based on TRC expecting to have a majority of the voting power of the combined company, TRC conducting the ongoing operations of the combined entity, TRC comprising a majority of the governing body of the combined company, and TRC’s senior management comprising the senior management of the combined company. Accordingly, for accounting purposes, the Business Combination will be treated as the equivalent of TRC issuing stock for the net assets of Plum, accompanied by a recapitalization. The net assets of Plum will be stated at historical cost, with no goodwill or other intangible assets will be recorded. Operations prior to the Business Combination will be those of TRC. As it is expected the fair value of Plum Public Warrants and Plum Private Placement Warrants will have similar fair value as those of PubCo Public Warrants as of the Closing, no material impact into profit or loss is expected.
171
MATERIAL U.S. FEDERAL INCOME TAX CONSIDERATIONS FOR U.S. HOLDERS
Subject to the qualifications, assumptions and limitations in the opinion attached as Exhibit 8.2 to the registration statement of which this proxy statement/prospectus is a part, the statements of law and legal conclusions set forth below represent the opinion of Hogan Lovells US LLP.
The following discussion is a summary of certain U.S. federal income tax considerations (i) for U.S. Holders and Non-U.S. Holders (each as defined below, and together, “Holders”) of the Plum Units, the Plum Shares, the Plum Warrants (each, a “Plum Security”) of the Domestication and the Plum Amalgamation, (ii) for Holders of Plum Class A Shares that elect to have the PubCo Common Shares they are entitled to receive redeemed for cash if the Business Combination is completed and (iii) for Holders of owning and disposing of PubCo Common Shares after the Domestication and the Plum Amalgamation. This section applies only to Holders that hold their Plum Securities or PubCo Common Shares as “capital assets” for U.S. federal income tax purposes (generally, property held for investment). For purposes of this discussion, because the components of a Plum Unit are generally separable at the option of the Holder, the Holder of a Plum Unit generally should be treated, for U.S. federal income tax purposes, as the owner of the underlying Plum Share and Plum Warrant components of the Plum Unit, and the discussion below with respect to actual Holders of Plum Shares and Plum Warrants also should apply to holders of Plum Units (as the deemed owners of the underlying Plum Shares and Plum Warrants that constitute the Plum Units). This position is not free from doubt, and no assurance can be given that the IRS would not assert, or that a court would not sustain, a contrary position. Holders of Plum Units are urged to consult their tax advisors concerning the U.S. federal, state, local and any non-U.S. tax consequences of the transactions contemplated by the Domestication, the Plum Amalgamation and the Business Combination (including any redemption of PubCo Common Shares) and any alternative characterizations of Plum Units.
This discussion is based on provisions of the Code, its legislative history, final, temporary and proposed U.S. treasury regulations promulgated thereunder (“Treasury Regulations”), published rulings and court decisions, all as currently in effect. These authorities are subject to change or differing interpretations, possibly on a retroactive basis, which may affect the U.S. federal income tax consequences described herein.
This discussion is general in nature and does not address all aspects of U.S. federal income taxation that may be relevant to any particular holder based on such holder’s individual circumstances or status. In particular, this discussion considers only holders that hold Plum Shares, or PubCo Common Shares or Plum Warrants as capital assets within the meaning of Section 1221 of the Code (generally, property held for investment). In addition, this discussion does not address the alternative minimum tax, the Medicare tax on net investment income, or the U.S. federal income tax consequences to holders that are subject to special treatment under U.S. federal income tax law, such as:
• financial institutions or financial services entities;
• broker-dealers;
• persons that are subject to the mark-to-market accounting rules under Section 475 of the Code;
• tax-exempt entities;
• governments or agencies or instrumentalities thereof;
• insurance companies;
• regulated investment companies;
• real estate investment trusts;
• certain expatriates or former long-term residents of the United States;
• persons that acquired Plum Shares or Plum Warrants pursuant to an exercise of employee options, in connection with employee incentive plans or otherwise as compensation;
172
• persons that hold Plum Shares or Plum Warrants as part of a straddle, constructive sale, hedging, Redemption or other integrated transaction;
• persons whose functional currency is not the U.S. dollar;
• controlled foreign corporations;
• passive foreign investment companies;
• persons required to accelerate the recognition of any item of gross income with respect to Plum Shares or Plum Warrants as a result of such income being recognized on an applicable financial statement;
• persons who actually or constructively own 5% or more of the shares of Plum by vote or value (except as specifically provided below);
• foreign corporations with respect to which there are one or more United States shareholders within the meaning of Treasury Regulation Section 1.367(b)-3(b)(1)(ii); or
• the Sponsor or its affiliates.
This discussion does not address any tax laws other than the U.S. federal income tax law, such as gift or estate tax laws, state, local or non-U.S. tax laws or, except as discussed herein, any tax reporting obligations of a holder of Plum Shares or PubCo Common Shares or Plum Warrants. Additionally, this discussion does not address the tax treatment of partnerships or other pass-through entities or persons who hold Plum Shares or PubCo Common Shares or Plum Warrants through such entities. If a partnership (or other entity classified as a partnership for U.S. federal income tax purposes) is the beneficial owner of Plum Shares or PubCo Common Shares or Plum Warrants, the U.S. federal income tax treatment of a partner in the partnership will generally depend on the status of the partner and the activities of the partner and such partnership. Holders of Plum Shares or PubCo Common Shares or Plum Warrants are urged to consult with their tax advisors regarding the specific tax consequences to such holders. This discussion also assumes that any distribution made (or deemed made) on Plum Shares or PubCo Common Shares or Plum Warrants and any consideration received (or deemed received) by a holder in consideration for the sale or other disposition of Plum Shares or PubCo Common Shares or Plum Warrants will be in U.S. dollars. We have not sought, and do not intend to seek, a ruling from the IRS as to any U.S. federal income tax consequences described herein. There can be no assurance that the IRS will agree with the discussion herein, or that a court would not sustain any challenge by the IRS in the event of litigation. Moreover, there can be no assurance that future legislation, regulations, administrative rulings or court decisions will not adversely affect the accuracy of the statements in this discussion.
THIS DISCUSSION IS FOR GENERAL INFORMATION PURPOSES ONLY, AND IS NOT INTENDED TO BE, AND SHOULD NOT BE CONSTRUED AS, LEGAL OR TAX ADVICE TO ANY PARTICULAR HOLDER. THE U.S. FEDERAL INCOME TAX TREATMENT OF THE BENEFICIAL OWNERS OF PLUM SHARES, PUBCO COMMON SHARES AND PLUM WARRANTS MAY BE AFFECTED BY MATTERS NOT DISCUSSED HEREIN AND DEPENDS IN SOME INSTANCES ON DETERMINATIONS OF FACT AND INTERPRETATIONS OF COMPLEX PROVISIONS OF U.S. FEDERAL INCOME TAX LAW FOR WHICH NO CLEAR PRECEDENT OR AUTHORITY MAY BE AVAILABLE. WE URGE BENEFICIAL OWNERS OF PLUM SHARES, PUBCO COMMON SHARES AND PLUM WARRANTS TO CONSULT THEIR TAX ADVISORS REGARDING THE SPECIFIC TAX CONSEQUENCES TO SUCH HOLDER OF THE DOMESTICATION, THE PLUM AMALGAMATION, EXERCISING REDEMPTION RIGHTS, AND OWNING AND DISPOSING OF NEW PLUM SHARES AND WARRANTS AS A RESULT OF ITS PARTICULAR CIRCUMSTANCES, INCLUDING THE U.S. FEDERAL, STATE, LOCAL AND FOREIGN INCOME AND OTHER TAX CONSEQUENCES THEREOF.
For purposes of this discussion, a “U.S. Holder” means a beneficial owner of Plum Shares or PubCo Common Shares or Plum Warrants that is for U.S. federal income tax purposes:
• an individual citizen or resident of the United States;
• a corporation (or other entity treated as a corporation) that is created or organized (or treated as created or organized) in or under the laws of the United States, any state thereof or the District of Columbia;
173
• an estate whose income is subject to U.S. federal income taxation regardless of its source; or
• a trust if (i) a U.S. court can exercise primary supervision over the trust’s administration and one or more U.S. persons are authorized to control all substantial decisions of the trust or (ii) it has a valid election in effect under applicable Treasury Regulations to be treated as a U.S. person.
A “Non-U.S. Holder” means a beneficial owner of Plum Shares or PubCo Common Shares or Plum Warrants that, for U.S. federal income tax purposes, is an individual, corporation, estate or trust that is not a U.S. Holder.
U.S. Holders
Tax Consequences of the Domestication and the Plum Amalgamation
We intend to report the Domestication and the Plum Amalgamation as a tax-deferred “reorganization’’ within the meaning of Section 368(a)(1)(F) of the Code. However, we have not sought, nor do we intend to seek, nor is the closing of the Domestication and the Plum Amalgamation conditioned on the receipt of, any ruling from the IRS or any opinion of counsel with respect to the qualification of the Domestication and the Plum Amalgamation as an F Reorganization. Consequently, no assurance can be given that the IRS will not assert, or that a court would not sustain, a position contrary to any of those set forth below. Accordingly, each U.S. Holder of Plum Securities is urged to consult its tax advisor with respect to the particular tax consequence of the Domestication and the Plum Amalgamation to such U.S. Holder.
In the case of a transaction, such as the Domestication and the Plum Amalgamation, that qualifies as an F Reorganization, except as otherwise provided herein, including with respect to the PFIC rules, a U.S. Holder of Plum Securities should not recognize gain or loss upon the exchange of its Plum Securities solely for PubCo Common Shares or PubCo Assumed Plum Warrants pursuant to the Domestication and the Plum Amalgamation.
A U.S. Holder’s tax basis in a share or a warrant of PubCo received in connection with the Domestication and the Plum Amalgamation should generally be the same as its tax basis in the Plum Share and Plum Warrant surrendered in exchange therefor, and (ii) the holding period for a share or a warrant of PubCo received by a U.S. Holder should generally include such U.S. Holder’s holding period for the Plum Share or Plum Warrant surrendered in exchange therefor.
If the Domestication and the Plum Amalgamation fails to qualify as an F Reorganization under Section 368, a U.S. Holder of Plum Securities generally would recognize gain or loss with respect to its Plum Securities in an amount equal to the difference, if any, between the fair market value of the corresponding PubCo Common Shares or PubCo Assumed Plum Warrants received in the Domestication and the Plum Amalgamation and the U.S. Holder’s adjusted tax basis in its Plum Securities surrendered. The U.S. Holder’s basis in its PubCo Common Shares or PubCo Assumed Plum Warrants would be equal to the fair market value of that stock on the date of the Domestication and the date of the Plum Amalgamation and such U.S. Holder’s holding period for the PubCo Common Shares or PubCo Assumed Plum Warrants would begin on the day following the date of the Domestication and date of the Plum Amalgamation. U.S. Holders who hold different blocks of Plum Securities (generally, Plum Securities purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them, and the discussion above does not specifically address all of the consequences to U.S. Holders who hold different blocks of Plum Securities.
PFIC Considerations
Even if the Domestication and the Plum Amalgamation qualifies as an F Reorganization, the Domestication and the Plum Amalgamation may still be a taxable event to U.S. Holders of Plum Shares or Plum Warrants under the PFIC provisions of the Code, to the extent that Section 1291(f) of the Code applies, as described below. Because Plum is a blank check company with no current active operating business and because, following the TRC Amalgamation, TRC is an REE exploration and development company that has not begun (and is not expected to generate operating income in the taxable year of the TRC Amalgamation), based upon the composition of its income and assets, and upon a review of its financial statements, Plum believes that PubCo is (and will be in the taxable year of the TRC Amalgamation) a PFIC.
174
Effect of PFIC Rules on the Domestication and the Plum Amalgamation. Section 1291(f) of the Code requires that, to the extent provided in Treasury Regulations, a U.S. person that disposes of stock of a PFIC must recognize gain, notwithstanding any other provision of the Code. No final Treasury Regulations are in effect under Section 1291(f) of the Code. Proposed Treasury Regulations under Section 1291(f) of the Code were promulgated in 1992, with a retroactive effective date once they become finalized. If finalized in their present form, these Treasury Regulations may require taxable gain recognition by a Non-Electing Shareholder, as defined below, with respect to its exchange of Plum Shares for PubCo Common Shares and Plum Warrants for PubCo Assumed Plum Warrants in the Domestication and the Plum Amalgamation if Plum were classified as a PFIC at any time during such U.S. Holder’s holding period in respect thereof unless an exception applies. Any such gain would generally be treated as an “excess distribution” made in the year of the Domestication and the Plum Amalgamation and subject to the special tax and interest charge rules discussed below under “Definition and General Taxation of a PFIC.” The proposed Treasury Regulations do not, however, require gain recognition if a U.S. Holder exchanges stock in a PFIC for stock in another PFIC in a transaction treated as a reorganization under Section 368(a) of the Code, which is expected to be the case here. In addition, the proposed Treasury Regulations under Section 1291(f) of the Code should not apply to an Electing Shareholder, as defined below, with respect to its Plum Shares for which a timely qualified election fund (“QEF”) election, a QEF election with a purging election, or mark-to-market (“MTM”) election is made, as each such election is described below. It is not possible to determine at this time whether, in what form, and with what effective date, final Treasury Regulations under Section 1291(f) of the Code will be adopted.
Definition and General Taxation of a PFIC. A non-U.S. corporation will be a PFIC if either (a) at least seventy-five percent (75%) of its gross income in a taxable year, including its pro rata share of the gross income of any corporation in which it owns or is considered to own at least twenty-five percent (25%) of the shares by value, is passive income or (b) at least fifty percent (50%) of its assets in a taxable year, ordinarily determined based on fair market value and averaged quarterly over the year, including its pro rata share of the assets of any corporation in which it owns or is considered to own at least twenty-five percent (25%) of the shares by value, are held for the production of, or produce, passive income. Passive income generally includes dividends, interest, rents and royalties (other than certain rents or royalties derived from the active conduct of a trade or business) and gains from the disposition of passive assets. The determination of whether a foreign corporation is a PFIC is made annually. As discussed above, Plum believes that it is a PFIC and expects that PubCo will be a PFIC in the taxable year of the TRC Amalgamation.
If Plum or PubCo is determined to be a PFIC for any taxable year (or portion thereof) that is included in the holding period of a U.S. Holder of Plum Shares or PubCo Common Shares or Plum Warrants and, solely with respect to the Plum Shares or PubCo Shares, the U.S. Holder did not make either (a) a timely QEF election for Plum’s or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) Plum Shares or PubCo Common Shares, (b) a QEF election along with a “purging election,” or (c) a MTM election, all of which are discussed further below, such U.S. Holder generally will be subject to special rules with respect to any gain recognized by the U.S. Holder on the sale or other disposition of its Plum Shares or PubCo Common Shares and any “excess distribution” made to the U.S. Holder. Excess distributions are generally any distributions to such U.S. Holder during a taxable year of the U.S. Holder that are greater than 125% of the average annual distributions received by such U.S. Holder in respect of the Plum Shares or PubCo Common Shares during the three preceding taxable years of such U.S. Holder or, if shorter, such U.S. Holder’s holding period for the Plum Shares or PubCo Common Shares.
Under these rules, the U.S. Holder’s gain or excess distribution will be allocated ratably over the U.S. Holder’s holding period for the Plum Shares or PubCo Common Shares or Plum Warrants. The amount of gain allocated to the U.S. Holder’s taxable year in which the U.S. Holder recognized the gain or received the excess distribution, or to the period in the U.S. Holder’s holding period before the first day of Plum’s first taxable year in which it qualified as a PFIC, will be taxed as ordinary income. The amount of gain allocated to other taxable years (or portions thereof) of the U.S. Holder and included in its holding period will be taxed at the highest tax rate in effect for that year and applicable to the U.S. Holder. The interest charge generally applicable to underpayments of tax will be imposed on the U.S. Holder in respect of the tax attributable to each such other taxable year of the U.S. Holder.
175
In general, if Plum, PubCo or TRC is determined to be a PFIC, a U.S. Holder may mitigate the tax consequences described above with respect to its Plum Shares or PubCo Common Shares (but not Plum Warrants) by making a timely QEF election (or a QEF election along with a purging election), or a MTM election, all as described below.
Impact of PFIC Rules on Certain U.S. Holders. The impact of the PFIC rules on a U.S. Holder of Plum Shares or PubCo Common Shares will depend on whether the U.S. Holder has made a timely and effective election to treat Plum or PubCo as a QEF under Section 1295 of the Code, for Plum’s or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) Plum Shares or PubCo Common Shares, the U.S. Holder made a QEF election along with a “purging election,” or if the U.S. Holder made a MTM election, all as discussed below. Proposed Treasury Regulations provide that a QEF election made with respect to PFIC stock exchanged in a transaction treated as a reorganization under Section 368(a) of the Code does not carry over to any PFIC stock received in the reorganization. Accordingly, U.S. Holders that have made a QEF election with respect to Plum Shares should consider with their tax advisors whether to make a QEF election with respect to the PubCo Common Shares received in the Plum Amalgamation. A U.S. Holder of a PFIC that made either a timely and effective QEF election, a QEF election along with a purging election, or a MTM election is hereinafter referred to as an “Electing Shareholder.” A U.S. Holder of a PFIC that is not an Electing Shareholder is hereinafter referred to as a “Non-Electing Shareholder.”
The QEF election is made on a shareholder-by-shareholder basis and, once made, can be revoked only with the consent of the IRS. A U.S. Holder generally makes a QEF election by attaching a completed IRS Form 8621 (Return by a Shareholder of a Passive Foreign Investment Company or Qualified Electing Fund), including the information provided in a “PFIC Annual Information Statement,” to a timely filed U.S. federal income tax return for the tax year to which the election relates. Retroactive QEF elections generally may be made only by filing a protective statement with such return and if certain other conditions are met or with the consent of the IRS. U.S. Holders are urged to consult their tax advisors regarding the availability and tax consequences of a retroactive QEF election under their particular circumstances.
A U.S. Holder’s ability to make a QEF election with respect to its Plum Shares or PubCo Common Shares is contingent upon, among other things, the provision by Plum or PubCo of certain information that would enable the U.S. Holder to make and maintain a QEF election. Upon written request, Plum or PubCo will endeavor to provide to a U.S. Holder such information as the IRS may require, including a PFIC Annual Information Statement, in order to enable the U.S. Holder to make and maintain a QEF election, but there can be no assurance that Plum or PubCo will timely provide such information that is required to make and maintain the QEF election. A U.S. Holder is not able to make a QEF election with respect to Plum Warrants. An Electing Shareholder making a valid and timely QEF election generally would not be subject to the adverse PFIC rules discussed above with respect to their Plum Shares. As a result, such a U.S. Holder generally should not recognize gain or loss as a result of the Domestication and the Plum Amalgamation but rather would include annually in gross income its pro rata share of the ordinary earnings and net capital gain of Plum, whether or not such amounts are actually distributed.
As indicated above, if a U.S. Holder of Plum Shares or PubCo Common Shares has not made a timely and effective QEF election with respect to Plum’s or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) Plum Shares or PubCo Common Shares, such U.S. Holder generally may nonetheless qualify as an Electing Shareholder by filing on a timely filed U.S. income tax return (including extensions) a QEF election and a purging election to recognize under the rules of Section 1291 of the Code any gain that it would otherwise recognize if the U.S. Holder sold its Plum Shares or PubCo Common Shares for their fair market value on the “qualification date.” The qualification date is the first day of Plum’s or PubCo’s tax year in which Plum or PubCo qualifies as a QEF with respect to such U.S. Holder. The purging election can only be made if such U.S. Holder held Plum Shares or PubCo Common Shares on the qualification date. The gain recognized by the purging election will be subject to the special tax and interest charge rules treating the gain as an excess distribution, as described above. As a result of the purging election, the U.S. Holder will increase the adjusted tax basis in its Plum Shares or PubCo Common Shares by the amount of the gain recognized and will also have a new holding period in the Plum Shares or PubCo Common Shares for purposes of the PFIC rules.
Alternatively, if a U.S. Holder, at the close of its taxable year, owns shares in a PFIC that are treated as marketable shares, the U.S. Holder may make a MTM election with respect to such shares for such taxable year. If the U.S. Holder makes a valid MTM election for the first taxable year of the U.S. Holder in which the U.S. Holder holds (or is deemed to hold) Plum Shares or PubCo Common Shares and for which Plum or PubCo is determined to be a PFIC, such holder will not be subject to the PFIC rules described above in respect to its Plum Shares or
176
PubCo Common Shares. Instead, the U.S. Holder will include as ordinary income each year the excess, if any, of the fair market value of its Plum Shares or PubCo Common Shares at the end of its taxable year over the adjusted basis in its Plum Shares or PubCo Common Shares. The U.S. Holder also will be allowed to take an ordinary loss in respect of the excess, if any, of the adjusted basis of its Plum Shares or PubCo Common Shares over the fair market value of its Plum Shares or PubCo Common Shares at the end of its taxable year (but only to the extent of the net amount of previously included income as a result of the MTM election). The U.S. Holder’s basis in its Plum Shares or PubCo Common Shares will be adjusted to reflect any such income or loss amounts and any further gain recognized on a sale or other taxable disposition of the Plum Shares or PubCo Common Shares will be treated as ordinary income. Shareholders who hold different blocks of Plum Shares or PubCo Common Shares (generally, shares of Plum or PubCo purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them. The MTM election is available only for shares that are regularly traded on a national securities exchange that is registered with the SEC, including Nasdaq, or on a foreign exchange or market that the IRS determines has rules sufficient to ensure that the market price represents a legitimate and sound fair market value. No assurance can be given that the Plum Shares or PubCo Common Shares are considered to be regularly traded for purposes of the MTM election or whether the other requirements of this election are satisfied. If such an election is available and has been made, such U.S. Holders will generally not be subject to the special taxation rules of Section 1291 of the Code discussed herein with respect to their Plum Shares or PubCo Common Shares. However, if the MTM election is made by a Non-Electing Shareholder after the beginning of the holding period for the PFIC stock, then the Section 1291 rules will apply to certain dispositions of, distributions on and other amounts taxable with respect to Plum Shares or PubCo Common Shares. A MTM election is not available with respect to Plum Warrants. U.S. Holders are urged to consult their tax advisers regarding the availability and tax consequences of a MTM election in respect to Plum Shares or PubCo Common Shares under their particular circumstances. In addition, although a U.S. Holder may be eligible to make a MTM election with respect to the Plum Shares or PubCo Shares, no such election may be made with respect to the stock of any subsidiary PFIC of Plum or PubCo that a U.S. Holder is treated as owning because such stock is not marketable. Hence, the MTM election will not be effective to eliminate the interest charge and other income inclusion rules described above with respect to deemed dispositions of such subsidiary PFIC stock or distributions from such a subsidiary PFIC to its shareholder.
The rules dealing with PFICs and with the timely QEF election, the QEF election with a purging election, and the MTM election are very complex and are affected by various factors in addition to those described above. Accordingly, a U.S. Holder of Plum Shares or PubCo Shares is urged to consult its tax advisor concerning the application of the PFIC rules to such securities under such holder’s particular circumstances.
Tax Consequences to U.S. Holders That Elect to Exercise Redemption Rights
For purposes of this discussion, a “Converting U.S. Holder” is a U.S. Holder that elects to exercise Redemption rights in respect of all or a portion of its Plum Shares.
Because the Domestication and the Plum Amalgamation will occur prior to the redemption of U.S. Holders that exercise redemption rights, U.S. Holders exercising redemption rights, although not free from doubt, will likely be deemed to have exchanged their Plum Shares for PubCo Common Shares and therefore subject to the potential tax consequences the PFIC rules as a result of the Domestication and the Plum Amalgamation (discussed further above) and then to the tax consequences of the redemption discussed below.
The U.S. federal income tax consequences to a Converting U.S. Holder will depend on whether the Redemption qualifies as a sale of PubCo Common Shares deemed received in the Domestication and the Plum Amalgamation under Section 302 of the Code or is treated as a distribution under Section 301 of the Code with respect to the Converting U.S. Holder. If the Redemption qualifies as a sale of such U.S. Holder’s PubCo Common Shares deemed received, such U.S. Holder will generally recognize capital gain or capital loss equal to the difference, if any, between the amount of cash received and such U.S. Holder’s tax basis in the PubCo Common Shares deemed received and redeemed. A U.S. Holder’s adjusted tax basis in its PubCo Common Shares will generally be equal to the amount such U.S. Holder paid for such Plum Shares deemed exchanged for such PubCo Common Shares. This gain or loss should generally be long-term capital gain or loss if the holding period of such PubCo Common Shares is more than one year at the time of the Redemption, including the holding
177
period of such Plum Shares deemed exchanged for such PubCo Common Shares. However, it is possible that because of the Redemption rights associated with the Plum Shares and PubCo Common Shares, the holding period of such shares may not be considered to begin until the date of such Redemption (and, thus, it is possible that long-term capital gain or loss treatment may not apply). The deductibility of capital losses is subject to limitations. Shareholders who hold different blocks of Plum Shares (generally, Plum Shares purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them.
The Redemption of Plum Shares generally will qualify as a sale if such Redemption (i) is “substantially disproportionate,” (ii) results in a “complete termination” of such U.S. Holder’s interest in Plum or (iii) is “not essentially equivalent to a dividend” with respect to the Converting U.S. Holder. For purposes of such tests with respect to a Converting U.S. Holder, that Converting U.S. Holder may be deemed to own not only shares actually owned, but also constructively owned, which in some cases may include shares such Converting U.S. Holder may acquire pursuant to options and shares owned by certain family members, certain estates and trusts of which the Converting U.S. Holder is a beneficiary and certain corporations and partnerships.
Generally, the Redemption will be “substantially disproportionate” with respect to the Converting U.S. Holder if (i) the Converting U.S. Holder’s percentage ownership (including constructive ownership) of the outstanding voting shares (including all classes that carry voting rights) of Plum is reduced immediately after the Redemption to less than 80% of the Converting U.S. Holder’s percentage interest (including constructive ownership) in such shares immediately before the Redemption; (ii) the Converting U.S. Holder’s percentage ownership (including constructive ownership) of the outstanding Plum shares (both voting and nonvoting) immediately after the Redemption is reduced to less than 80% of such percentage ownership (including constructive ownership) immediately before the Redemption; and (iii) the Converting U.S. Holder owns (including constructive ownership), immediately after the Redemption, less than 50% of the total combined voting power of all classes of shares of Plum entitled to vote. There will be a “complete termination” of such Converting U.S. Holder’s interest if either (i) all of the Plum shares actually and constructively owned by such Converting U.S. Holder are redeemed or (ii) all of the Plum shares actually owned by such Converting U.S. Holder are redeemed and such Converting U.S. Holder is eligible to waive, and effectively waives in accordance with specific rules, the attribution of the Plum shares owned by certain family members and such Converting U.S. Holder does not constructively own any other Plum shares and otherwise complies with specific conditions. Whether the Redemption will be considered “not essentially equivalent to a dividend” with respect to a Converting U.S. Holder will depend upon the particular circumstances of that Converting U.S. Holder. However, the Redemption generally must result in a meaningful reduction in the Converting U.S. Holder’s actual or constructive percentage ownership of Plum. Whether the Redemption will result in a “meaningful reduction” in such Converting U.S. Holder’s proportionate interest will depend on the particular facts and circumstances applicable to it. If the Converting U.S. Holder’s relative interest in Plum is a small minority interest and the shareholder exercises no control over corporate affairs, taking into account the effect of Redemptions by other shareholders, and its percentage ownership (including constructive ownership) is reduced as a result of the Redemption, such Converting U.S. Holder may be regarded as having a meaningful reduction in its interest pursuant to a published ruling in which the IRS indicated that even a small reduction in the proportionate interest of a small minority shareholder in a closely held corporation who exercises no control over corporate affairs may constitute such a “meaningful reduction.” A U.S. Holder is urged to consult with its tax advisors as to the tax consequences to it of any Redemption of its Plum Shares.
If none of the tests described above applies, the consideration paid to the Converting U.S. Holder will generally be treated as dividend income for U.S. federal income tax purposes to the extent of Plum’s current or accumulated earnings and profits. Any distribution in excess of such earnings and profits will reduce the Converting U.S. Holder’s basis in the Plum Shares (but not below zero) and any remaining excess will be treated as capital gain realized on the sale or other disposition of the Plum Shares. After the application of those rules, any remaining tax basis of the Converting U.S. Holder in the Plum Shares redeemed will generally be added to the Converting U.S. Holder’s adjusted tax basis in its remaining Plum Shares, or, if it has none, to the Converting U.S. Holder’s adjusted tax basis in its Plum Warrants or possibly in other Plum shares constructively owned by
178
such U.S. Holder. U.S. Holders who hold different blocks of Plum Shares (generally, shares of Plum purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them.
ALL U.S. HOLDERS ARE URGED TO CONSULT THEIR TAX ADVISORS AS TO THE TAX CONSEQUENCES TO THEM OF A REDEMPTION OF ALL OR A PORTION OF THEIR PLUM SHARES PURSUANT TO AN EXERCISE OF REDEMPTION RIGHTS.
Tax Consequences for U.S. Holders of Owning and Disposing of PubCo Common Shares and PubCo Assumed Plum Warrants
Distributions on PubCo Common Shares. Subject to the PFIC rules described above, a U.S. Holder will generally be required to include in gross income as dividend income the amount of any distribution of cash or other property paid on PubCo Common Shares to the extent the distribution is paid out of PubCo’s current or accumulated earnings and profits (as determined under U.S. federal income tax principles). The source of such dividend income will generally be domestic unless less than 25 percent of the gross income from all sources of PubCo for the 3-year period ending with the close of its taxable year preceding the declaration of such dividends (or for such part of such period as the corporation has been in existence) was effectively connected (or treated as effectively connected other than income described in section 884(d)(2) of the Code) with the conduct of a trade or business within the United States; but only in an amount which bears the same ratio to such dividends as the gross income of the corporation for such period which was effectively connected (or treated as effectively connected other than income described in section 884(d)(2) of the Code). Distributions in excess of PubCo’s current and accumulated earnings and profits will constitute a return of capital that will be applied against and reduce (but not below zero) the U.S. Holder’s adjusted tax basis in its shares of PubCo Common Shares on a per-share basis. Any remaining excess will be treated as gain realized on the sale of PubCo Common Shares and will be treated as described below under the section entitled “Sale, Taxable Exchange or Other Taxable Disposition of PubCo Common Shares.”
With certain exceptions, and provided certain holding period requirements are met, dividends received on stock of a “qualified foreign corporation” by a non-corporate U.S. Holder will generally constitute “qualified dividends” that will be subject to U.S. federal income tax at preferential long-term capital gains rates. For this purpose, a “qualified foreign corporation” means any foreign corporation provided that: (i) the corporation was not, in the year prior to the year in which the dividend was paid, and is not, in the year in which the dividend is paid, a passive foreign investment company, (ii) certain holding period requirements are met and (iii) either (A) the corporation is eligible for the benefits of a comprehensive income tax treaty with the United States that the IRS has approved for the purposes of the qualified dividend rules or (B) the stock with respect to which such dividend was paid is readily tradable on an established securities market in the United States. While PubCo believes it will be a “qualified foreign corporation”, there can be no assurances that it does so qualify under the Code (among other reasons, there can be no assurance that the PubCo Common Shares will be treated as regularly traded on an established securities market) or that an applicable tax treaty will apply.
A U.S. Holder may be entitled, subject to a number of complex limitations and conditions (including a minimum holding period requirement), to claim a U.S. foreign tax credit in respect of Canadian income taxes, if any, withheld on the foreign source portion (as determined under U.S. federal income tax principles) of dividends received in respect of the PubCo Common Shares. A U.S. Holder who does not elect to claim a credit for any foreign income taxes paid during the taxable year may instead claim a deduction in respect of such income taxes provided the U.S. Holder elects to deduct (rather than credit) all foreign income taxes for that year. Further, U.S. Treasury regulations finalized in January 2022 have imposed additional requirements that must be met for a Canadian or other foreign tax to be creditable (including requirements that a “covered withholding tax” be imposed on nonresidents in lieu of a generally applicable tax that satisfies the regulatory definition of an “income tax,” which may be unclear or difficult to determine), and these requirements may further restrict a U.S. Holder’s ability to benefit from the foreign tax credit for Canadian withholding taxes. Recent IRS guidance provides temporary relief from some of these U.S. Treasury regulations, subject to certain requirements being met, until further notice is provided by the IRS. The rules relating to computing foreign tax credits or deducting foreign taxes are extremely complex, and U.S. Holders are encouraged to consult their own tax advisors regarding the availability of foreign tax credits under their particular circumstances.
179
Dividends paid in Canadian dollars (including the amount of any Canadian taxes withheld therefrom, if any) will be includible in a U.S. Holder’s gross income in a U.S. dollar amount calculated by reference to the spot rate of exchange in effect on the day the Canadian dollars are actually or constructively received by the U.S. Holder, regardless of whether the dividends are converted into U.S. dollars. If the Canadian dollars are converted to U.S. dollars on the date of such receipt, a U.S. Holder generally will not recognize any foreign currency gain or loss. However, if the U.S. Holder converts the Canadian dollars into U.S. dollars on a later date, the U.S. Holder must include in gross income any gain or loss resulting from any exchange rate fluctuations. The gain or loss will be equal to the difference between (i) the U.S. dollar value of the amount included in income when the dividend was received and (ii) the amount received on the conversion of the Canadian dollars into U.S. dollars. Generally, any gain or loss resulting from currency exchange fluctuations during the period from the date the dividend is includible in a U.S. Holder’s gross income to the date such payment is converted into U.S. dollars will be foreign currency gain or loss and will be treated as ordinary income or loss. Such gain or loss generally will be treated as income from sources within the United States. U.S. Holders are encouraged to consult their own independent tax advisors regarding the treatment of foreign currency gain or loss, if any, on any Canadian dollars received that are converted into U.S. dollars on a date subsequent to actual or constructive receipt by the U.S. Holder.
Sale, Taxable Exchange or Other Taxable Disposition of PubCo Common Shares. Subject to the PFIC rules described above, a U.S. Holder generally will recognize capital gain or loss in an amount equal to the difference between the amount of cash received in the disposition and the U.S. Holder’s adjusted tax basis in the PubCo Common Shares disposed of. Any such capital gain or loss generally will be long-term capital gain or loss if the U.S. holder’s holding period for the PubCo Common Shares so disposed of exceeds one year. As described above, the holding period for the PubCo Common Shares should include the holding period for the corresponding Plum Shares if the Domestication and the Plum Amalgamation qualifies as an F Reorganization. Long-term capital gains recognized by non-corporate U.S. holders generally will be eligible to be taxed at reduced rates. The deductibility of capital losses is subject to limitations. However, it is unclear whether the redemption rights included in the Plum shares suspends the running of the holding period while the U.S. Holder holds such Plum shares.
U.S. Holders who hold different blocks of PubCo Common Shares (including as a result of holding different blocks of Plum shares purchased or acquired on different dates or at different prices) should consult their tax advisors to determine how the above rules apply to them.
Additional Reporting Requirements. Certain U.S. Holders may be required to file an IRS Form 926 (Return by a U.S. Transferor of Property to a Foreign Corporation) to report a transfer of property (including cash) to Plum or PubCo. Substantial penalties may be imposed on a U.S. Holder that fails to comply with this reporting requirement, and the period of limitations on assessment and collection of U.S. federal income taxes will be extended in the event of a failure to comply. Furthermore, certain U.S. Holders who are individuals and certain entities will be required to report information with respect to such U.S. Holder’s investment in “specified foreign financial assets” on IRS Form 8938 (Statement of Specified Foreign Financial Assets), subject to certain exceptions. Specified foreign financial assets generally include any financial account maintained with a non-U.S. financial institution and should also include Plum Shares or PubCo Common Shares if they are not held in an account maintained with a financial institution. U.S. Holders are urged to consult their tax advisors regarding the foreign financial asset and other reporting obligations and their application to an investment in Plum Shares or PubCo Common Shares.
Treasury Regulations meant to require the reporting of certain tax shelter transactions could be interpreted to cover transactions generally not regarded as tax shelters, including certain foreign currency transactions. Under the applicable Treasury Regulations, certain transactions are required to be reported to the IRS including, in certain circumstances, a sale, exchange, retirement or other taxable disposition of foreign currency, to the extent that such sale, exchange, retirement or other taxable disposition results in a tax loss in excess of a threshold amount. You should consult your tax advisor to determine the tax return obligations, if any, with respect to Plum Shares or PubCo Common Shares and the receipt of Canadian dollars in respect thereof, including any requirement to file IRS Form 8886 (Reportable Transaction Disclosure Statement).
180
Non-U.S. Holders
Effects of the Domestication and the Plum Amalgamation to Non-U.S. Holders
The Domestication and the Plum Amalgamation is not expected to result in any U.S. federal income tax consequences to Non-U.S. Holders of Plum Shares.
Tax Effects to Non-U.S. Holders of Exercising Redemption Rights
The U.S. federal income tax consequences to a Non-U.S. Holder of Plum Shares that exercises its redemption rights in exchange for all or a portion of its PubCo Common Shares deemed received in the Domestication and the Plum Amalgamation will depend on whether the redemption qualifies as a sale of the PubCo Common Shares redeemed, as described above under “U.S. Holders — Tax Consequences to U.S. Holders That Elect to Exercise Redemption Rights.” If such a redemption qualifies as a sale of PubCo Common Shares, the U.S. federal income tax consequences to the Non-U.S. Holder will be as described below under “— Gain on Disposition of PubCo Common Shares.” If such a redemption does not qualify as a sale of PubCo Common Shares, the Non-U.S. Holder will be treated as receiving a corporate distribution, the U.S. federal income tax consequences of which are described below under “— Distributions on PubCo Common Shares.”
Because it may not be certain at the time a Non-U.S. Holder is redeemed whether such Non-U.S. Holder’s redemption will be treated as a sale of the PubCo Common Shares redeemed or a corporate distribution, and because such determination will depend in part on a Non-U.S. Holder’s particular circumstances, the applicable withholding agent may not be able to determine whether (or to what extent) a Non-U.S. Holder is treated as receiving a U.S. source dividend for U.S. federal income tax purposes. In addition, as the redemption will take place after the Domestication and the Plum Amalgamation, any dividend resulting from the redemption to the extent it is treated as U.S. source, may result in the applicable withholding agent deducting U.S. withholding tax at a rate of 30% (or such lower rate as may be specified by an applicable income tax treaty) on the gross amount of any consideration paid to a Non-U.S. Holder in redemption of such Non-U.S. Holder’s PubCo Common Shares, unless (i) the applicable withholding agent has established special procedures allowing Non-U.S. Holders to certify that they are exempt from such withholding tax or such withholding tax should be applied on a lesser amount (noting that in the absence of specific information, the withholding agent may treat the entire amount of the dividend as U.S. source) and (ii) such Non-U.S. Holders are able to certify that they meet the requirements of such exemption (e.g., because such Non-U.S. Holders are not treated as receiving a dividend under the Section 302 of the Code tests described above under the section entitled “U.S. Holders — Tax Consequences to U.S. Holders That Elect to Exercise Redemption Rights”), or such Non-U.S. Holder claims the benefit of an applicable treaty rate (a) by delivering to the withholding agent an applicable IRS Form W-8 certifying under penalty of perjury that such holder is not a United States person as defined under the Code and is eligible for treaty benefits or (b) if such Non-U.S. Holder’s PubCo Common Shares is held through certain foreign intermediaries, by satisfying the relevant certification requirements of applicable United States Treasury Regulations). Special certification and other requirements apply to certain Non-U.S. Holders that are pass-through entities rather than corporations or individuals. Note, however, there can be no assurance that any applicable withholding agent will establish such special certification procedures. If an applicable withholding agent withholds excess amounts from the amount payable to a Non-U.S. Holder, such Non-U.S. Holder generally may obtain a refund of any such excess amounts by timely filing an appropriate claim for refund with the IRS. Non-U.S. Holders should consult their own tax advisors regarding the application of the foregoing rules in light of their particular facts and circumstances and any applicable procedures or certification requirements.
Tax Consequences for Non-U. S. Holders of Owning and Disposing of PubCo Common Shares
Distributions on PubCo Common Shares. Distributions of cash or property to a Non-U.S. Holder in respect of PubCo Common Shares received in the Domestication and the Plum Amalgamation will generally constitute dividends for U.S. federal income tax purposes to the extent paid from PubCo’s current or accumulated earnings and
181
profits, as determined under U.S. federal income tax principles. While a portion of such dividends may be treated as derived from U.S. sources, as discussed above under, Tax Consequences for U.S. Holders of Owning and Disposing of PubCo Common Shares and PubCo Assumed Plum Warrants — Distributions on PubCo Common Shares), such U.S. source dividends should be exempt from U.S. federal withholding tax under Section 871(i)(2)(D) and Section 881(d) of the Code.
Dividends that are effectively connected with the conduct of a trade or business by the Non-U.S. Holder within the United States (and, if required by an applicable income tax treaty, are attributable to a U.S. permanent establishment or fixed base of the Non-U.S. Holder) are not subject to such withholding tax, provided certain certification and disclosure requirements are satisfied (generally by providing an IRS Form W-8ECI). Instead, such dividends are subject to United States federal income tax on a net income basis in the same manner as if the Non-U.S. Holder were a United States person as defined under the Code. Any such effectively connected dividends received by a foreign corporation may be subject to an additional “branch profits tax” at a 30% rate or such lower rate as may be specified by an applicable income tax treaty.
Gain on Disposition of PubCo Common Shares. Subject to the below discussion of backup withholding and the Foreign Account Tax Compliance Act (as defined below), any gain realized by a Non-U.S. Holder on the taxable disposition of PubCo Common Shares or PubCo Assumed Plum Warrants generally will not be subject to U.S. federal income tax unless:
• the gain is effectively connected with a trade or business of the Non-U.S. Holder in the United States (and, if required by an applicable income tax treaty, is attributable to a United States permanent establishment or fixed base of the Non-U.S. Holder); or
• the Non-U.S. Holder is an individual who is present in the United States for a period or periods aggregating 183 days or more in the taxable year of the disposition, and certain other conditions are met.
A non-corporate Non-U.S. Holder described in the first bullet point immediately above will be subject to tax on the net gain derived from the sale of PubCo Common Shares or PubCo Assumed Plum Warrants under regular U.S. federal income tax rates. An individual Non-U.S. Holder described in the second bullet point immediately above will be subject to a flat 30% tax on the gain derived from the sale of PubCo Common Shares or PubCo Assumed Plum Warrants, which may be offset by certain United States source capital losses, even though the individual is not considered a resident of the United States, provided that the individual has timely filed U.S. federal income tax returns with respect to such losses. If a Non-U.S. Holder that is a foreign corporation falls under the first bullet point immediately above, it will be subject to tax on its net gain in the same manner as if it were a United States person as defined under the Code and, in addition, may be subject to the “branch profits tax” equal to 30% (or such lower rate as may be specified by an applicable income tax treaty) of its effectively connected earnings and profits, subject to adjustments.
Information Reporting and Backup Withholding
PubCo generally must report annually to the IRS and to each Non-U.S. Holder the amount of dividends paid to such holder and the tax withheld with respect to such dividends, regardless of whether withholding was required. Copies of the information returns reporting such dividends and withholding may also be made available to the tax authorities in the country in which the Non-U.S. Holder resides under the provisions of an applicable income tax treaty.
A Non-U.S. Holder generally will be subject to backup withholding for dividends paid to such holder unless such holder certifies under penalty of perjury that it is a Non-U.S. Holder (and the payor does not have actual knowledge or reason to know that such holder is a United States person as defined under the Code), or such holder otherwise establishes an exemption. Information reporting and, depending on the circumstances, backup withholding generally will apply to the proceeds of a sale of PubCo Common Shares within the United States or conducted through certain United States-related financial intermediaries, unless the beneficial owner certifies under penalty of perjury that it is a Non-U.S. Holder (and the payor does not have actual knowledge or reason to know that the beneficial owner is a United States person as defined under the Code), or such owner otherwise establishes an exemption.
182
Any amounts withheld under the backup withholding rules may be allowed as a refund or a credit against a Non-U.S. Holder’s U.S. federal income tax liability provided the required information is timely furnished to the IRS.
Foreign Account Tax Compliance Act
Sections 1471 through 1474 of the Code and the Treasury Regulations and administrative guidance promulgated thereunder (commonly referred as the “Foreign Account Tax Compliance Act” or “FATCA”) generally impose withholding at a rate of 30% in certain circumstances on dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, securities (including PubCo Common Shares and PubCo Assumed Plum Warrants) which are held by or through certain foreign financial institutions (including investment funds), unless any such institution (i) enters into, and complies with, an agreement with the IRS to report, on an annual basis, information with respect to interests in, and accounts maintained by, the institution that are owned by certain U.S. persons and by certain non-U.S. entities that are wholly or partially owned by U.S. persons and to withhold on certain payments or (ii) if required under an intergovernmental agreement between the United States and an applicable foreign country, reports such information to its local tax authority, which will exchange such information with the U.S. authorities. An intergovernmental agreement between the United States and an applicable foreign country may modify these requirements. Accordingly, the entity through which PubCo Common Shares and PubCo Assumed Plum Warrants are held will affect the determination of whether such withholding is required. Similarly, dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, PubCo Common Shares and PubCo Assumed Plum Warrants held by an investor that is a non-financial non-U.S. entity that does not qualify under certain exceptions will generally be subject to withholding at a rate of 30%, unless such entity either (i) certifies to the applicable withholding agent that such entity does not have any “substantial United States owners” or (ii) provides certain information regarding the entity’s “substantial United States owners,” which will in turn be provided to the U.S. Department of Treasury.
Under the applicable Treasury Regulations and administrative guidance, withholding under FATCA generally applies to payments of dividends in respect of PubCo Common Shares. While withholding under FATCA generally would also apply to payments of gross proceeds from the sale or other disposition of securities (including PubCo Common Shares and PubCo Assumed Plum Warrants), proposed Treasury Regulations eliminate FATCA withholding on payments of gross proceeds entirely. Taxpayers generally may rely on these proposed Treasury Regulations until final Treasury Regulations are issued. All holders should consult their tax advisors regarding the possible implications of FATCA on their investment in PubCo Common Shares and PubCo Assumed Plum Warrants.
183
MATERIAL U.S. FEDERAL INCOME TAX CONSIDERATIONS FOR TRC U.S. HOLDERS
Subject to the qualifications, assumptions and limitations in the opinion attached as Exhibit 8.1 to the registration statement of which this proxy statement/prospectus is a part, the statements of law and legal conclusions set forth below represent the opinion of Allen Overy Shearman Sterling US LLP.
The following discussion is a summary of certain U.S. federal income tax considerations for U.S. Holders and Non-U.S. Holders (each as defined below, and together, “Holders”) of the TRC Shares of (i) the TRC Amalgamation and (ii) owning and disposing of PubCo Common Shares after the TRC Amalgamation. This section applies only to Holders that hold their TRC Shares as “capital assets” for U.S. federal income tax purposes (generally, property held for investment).
This discussion is based on provisions of the Code, its legislative history, final, temporary and proposed U.S. treasury regulations promulgated thereunder (“Treasury Regulations”), published rulings and court decisions, all as currently in effect. These authorities are subject to change or differing interpretations, possibly on a retroactive basis, which may affect the U.S. federal income tax consequences described herein.
This discussion is general in nature and does not address all aspects of U.S. federal income taxation that may be relevant to any particular holder based on such holder’s individual circumstances or status. In particular, this discussion considers only holders that hold TRC Shares and PubCo Common Shares as capital assets within the meaning of Section 1221 of the Code (generally, property held for investment). In addition, this discussion does not address the alternative minimum tax, the Medicare tax on net investment income, or the U.S. federal income tax consequences to holders that are subject to special treatment under U.S. federal income tax law, such as:
• financial institutions or financial services entities;
• broker-dealers;
• persons that are subject to the mark-to-market accounting rules under Section 475 of the Code;
• tax-exempt entities;
• governments or agencies or instrumentalities thereof;
• insurance companies;
• regulated investment companies;
• real estate investment trusts;
• certain expatriates or former long-term residents of the United States;
• persons that acquired TRC Shares pursuant to an exercise of employee options, in connection with employee incentive plans or otherwise as compensation;
• persons that hold TRC Shares as part of a straddle, constructive sale, hedging, or other integrated transaction;
• persons whose functional currency is not the U.S. dollar;
• controlled foreign corporations;
• passive foreign investment companies;
• persons required to accelerate the recognition of any item of gross income with respect to TRC Shares as a result of such income being recognized on an applicable financial statement;
• persons who actually or constructively own 5% or more of the shares of TRC by vote or value (except as specifically provided below); or
• the Sponsor or its affiliates.
184
This discussion does not address any tax laws other than the U.S. federal income tax law, such as gift or estate tax laws, state, local or non-U.S. tax laws or, except as discussed herein, any tax reporting obligations of a holder of TRC Shares or PubCo Common Shares. Additionally, this discussion does not address the tax treatment of partnerships or other pass-through entities or persons who hold TRC Shares or PubCo Common Shares through such entities. If a partnership (or other entity classified as a partnership for U.S. federal income tax purposes) is the beneficial owner of TRC Shares or PubCo Common Shares, the U.S. federal income tax treatment of a partner in the partnership will generally depend on the status of the partner and the activities of the partner and such partnership. Holders of TRC Shares and PubCo Common Shares are urged to consult with their tax advisors regarding the specific tax consequences to such holders. This discussion also assumes that any distribution made (or deemed made) on TRC Shares or PubCo Common Shares and any consideration received (or deemed received) by a holder in consideration for the sale or other disposition of TRC Shares or PubCo Common Shares will be in U.S. dollars. We have not sought, and do not intend to seek, a ruling from the IRS as to any U.S. federal income tax consequences described herein. There can be no assurance that the IRS will agree with the discussion herein, or that a court would not sustain any challenge by the IRS in the event of litigation. Moreover, there can be no assurance that future legislation, regulations, administrative rulings or court decisions will not adversely affect the accuracy of the statements in this discussion.
THIS DISCUSSION IS FOR GENERAL INFORMATION PURPOSES ONLY, AND IS NOT INTENDED TO BE, AND SHOULD NOT BE CONSTRUED AS, LEGAL OR TAX ADVICE TO ANY PARTICULAR HOLDER. THE U.S. FEDERAL INCOME TAX TREATMENT OF THE BENEFICIAL OWNERS OF TRC SHARES OR PUBCO COMMON SHARES MAY BE AFFECTED BY MATTERS NOT DISCUSSED HEREIN AND DEPENDS IN SOME INSTANCES ON DETERMINATIONS OF FACT AND INTERPRETATIONS OF COMPLEX PROVISIONS OF U.S. FEDERAL INCOME TAX LAW FOR WHICH NO CLEAR PRECEDENT OR AUTHORITY MAY BE AVAILABLE. WE URGE BENEFICIAL OWNERS OF TRC SHARES TO CONSULT THEIR TAX ADVISORS REGARDING THE SPECIFIC TAX CONSEQUENCES TO SUCH HOLDER OF THE TRC AMALGAMATION AND OWNING AND DISPOSING OF PUBCO COMMON SHARES AS A RESULT OF ITS PARTICULAR CIRCUMSTANCES, INCLUDING THE U.S. FEDERAL, STATE, LOCAL AND FOREIGN INCOME AND OTHER TAX CONSEQUENCES THEREOF.
For purposes of this discussion, a “U.S. Holder” means a beneficial owner of TRC Shares or PubCo Common Shares that is for U.S. federal income tax purposes:
• an individual citizen or resident of the United States;
• a corporation (or other entity treated as a corporation) that is created or organized (or treated as created or organized) in or under the laws of the United States, any state thereof or the District of Columbia;
• an estate whose income is subject to U.S. federal income taxation regardless of its source; or
• a trust if (i) a U.S. court can exercise primary supervision over the trust’s administration and one or more U.S. persons are authorized to control all substantial decisions of the trust or (ii) it has a valid election in effect under applicable Treasury Regulations to be treated as a U.S. person.
A “Non-U.S. Holder” means a beneficial owner of TRC Shares or PubCo Common Shares that, for U.S. federal income tax purposes, is an individual, corporation, estate or trust that is not a U.S. Holder.
U.S. Holders
Tax Consequences of the TRC Amalgamation
We intend to report TRC Amalgamation as a tax-deferred “reorganization” within the meaning of Section 368(a) of the Code. However, we have not sought, nor do we intend to seek, nor is the closing of the TRC Amalgamation conditioned on the receipt of, any ruling from the IRS or any opinion of counsel with respect to the qualification of the TRC Amalgamation as a reorganization. Consequently, no assurance can be given that the IRS
185
will not assert, or that a court would not sustain, a position contrary to any of those set forth below. Accordingly, each U.S. Holder of TRC Shares is urged to consult its tax advisor with respect to the particular tax consequence of the TRC Amalgamation to such U.S. Holder.
In the case of a transaction, such as the TRC Amalgamation, that qualifies as a reorganization, except as otherwise provided herein, including with respect to the PFIC rules (as discussed below), a U.S. Holder of TRC Shares should not recognize gain or loss upon the exchange of its TRC Shares solely for PubCo Common Shares pursuant to the TRC Amalgamation.
A U.S. Holder’s tax basis in a share of PubCo received in connection with the TRC Amalgamation should generally be the same as its tax basis in the TRC Share surrendered in exchange therefor and the holding period for a share of PubCo received by a U.S. Holder should generally include such U.S. Holder’s holding period for the TRC Share surrendered in exchange therefor.
If the TRC Amalgamation fails to qualify as a reorganization under Section 368(a) of the Code, a U.S. Holder of TRC Shares generally would recognize gain or loss with respect to its TRC Shares in an amount equal to the difference, if any, between the fair market value of the corresponding PubCo Common Shares received in the TRC Amalgamation and the U.S. Holder’s adjusted tax basis in its TRC Shares surrendered. The U.S. Holder’s basis in its PubCo Common Shares would be equal to the fair market value of that stock on the date of the TRC Amalgamation and such U.S. Holder’s holding period for the PubCo Common Shares would begin on the day following the date of the TRC Amalgamation. U.S. Holders who hold different blocks of TRC Shares (generally, TRC Shares purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them, and the discussion above does not specifically address all of the consequences to U.S. Holders who hold different blocks of TRC Shares.
PFIC Considerations
Even if the TRC Amalgamation qualifies as a reorganization, the TRC Amalgamation may still be a taxable event to U.S. Holders of TRC Shares under the PFIC provisions of the Code, to the extent that Section 1291(f) of the Code applies, as described below. In addition, the U.S. federal income tax consequences of holding PubCo Common Shares received in the TRC Amalgamation to a U.S. Holder generally will depend on whether PubCo is a PFIC during any taxable year in which a U.S. Holder holds PubCo Common Shares. Because TRC is an REE exploration and development company that has not begun generating operating income, based upon the composition of its income and assets, and upon a review of its financial statements, TRC believes that is a PFIC and that PubCo will be a PFIC.
Effect of PFIC Rules on the TRC Amalgamation. Section 1291(f) of the Code requires that, to the extent provided in Treasury Regulations, a U.S. person that disposes of stock of a PFIC must recognize gain, notwithstanding any other provision of the Code. No final Treasury Regulations are in effect under Section 1291(f) of the Code. Proposed Treasury Regulations under Section 1291(f) of the Code were promulgated in 1992, with a retroactive effective date once they become finalized. If finalized in their present form, these Treasury Regulations may require taxable gain recognition by a U.S. Holder with respect to its exchange of TRC Shares for PubCo Common Shares in the TRC Amalgamation if TRC were classified as a PFIC at any time during such U.S. Holder’s holding period in respect thereof unless an exception applies. Any such gain would generally be treated as an “excess distribution” made in the year of TRC Amalgamation and subject to the special tax and interest charge rules discussed below under “Definition and General Taxation of a PFIC.” The proposed Treasury Regulations do not, however, require gain recognition if a U.S. Holder exchanges stock in a PFIC for stock in another PFIC in a transaction treated as a reorganization under Section 368(a) of the Code, which is expected to be the case here. In addition, the proposed Treasury Regulations under Section 1291(f) of the Code should not apply to an Electing Shareholder, as defined below, with respect to its TRC Shares for which a timely qualified election fund (“QEF”) election, a QEF election with a purging election, or mark-to-market (“MTM”) election is made, as each such election is described below. It is not possible to determine at this time whether, in what form, and with what effective date, final Treasury Regulations under Section 1291(f) of the Code will be adopted.
186
Definition and General Taxation of a PFIC. A non-U.S. corporation will be a PFIC if either (a) at least seventy-five percent (75%) of its gross income in a taxable year, including its pro rata share of the gross income of any corporation in which it owns or is considered to own at least twenty-five percent (25%) of the shares by value, is passive income or (b) at least fifty percent (50%) of its assets in a taxable year, ordinarily determined based on fair market value and averaged quarterly over the year, including its pro rata share of the assets of any corporation in which it owns or is considered to own at least twenty-five percent (25%) of the shares by value, are held for the production of, or produce, passive income. Passive income generally includes dividends, interest, rents and royalties (other than certain rents or royalties derived from the active conduct of a trade or business) and gains from the disposition of passive assets. The determination of whether a foreign corporation is a PFIC is made annually. As discussed above, TRC believes that it is a PFIC and expects that PubCo will be a PFIC in the taxable year of TRC Amalgamation.
If TRC or PubCo is determined to be a PFIC for any taxable year (or portion thereof) that is included in the holding period of a U.S. Holder of TRC Shares or PubCo Common Shares and the U.S. Holder did not make either (a) a timely QEF election for TRC or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) TRC Shares or PubCo Common Shares, (b) a QEF election along with a “purging election,” or (c) a MTM election, all of which are discussed further below, such U.S. Holder generally will be subject to special rules with respect to any gain recognized by the U.S. Holder on the sale or other disposition of its TRC Shares or PubCo Common Shares and any “excess distribution” made to the U.S. Holder. Excess distributions are generally any distributions to such U.S. Holder during a taxable year of the U.S. Holder that are greater than 125% of the average annual distributions received by such U.S. Holder in respect of the TRC Shares or PubCo Common Shares during the three preceding taxable years of such U.S. Holder or, if shorter, such U.S. Holder’s holding period for the TRC Shares or PubCo Common Shares.
Under these rules, the U.S. Holder’s gain or excess distribution will be allocated ratably over the U.S. Holder’s holding period for the TRC Shares or PubCo Common Shares. The amount of gain allocated to the U.S. Holder’s taxable year in which the U.S. Holder recognized the gain or received the excess distribution, or to the period in the U.S. Holder’s holding period before the first day of TRC’s first taxable year in which it qualified as a PFIC, will be taxed as ordinary income. The amount of gain allocated to other taxable years (or portions thereof) of the U.S. Holder and included in its holding period will be taxed at the highest tax rate in effect for that year and applicable to the U.S. Holder. The interest charge generally applicable to underpayments of tax will be imposed on the U.S. Holder in respect of the tax attributable to each such other taxable year of the U.S. Holder.
In general, if TRC or PubCo is determined to be a PFIC, a U.S. Holder may mitigate the tax consequences described above with respect to its TRC Shares or PubCo Common Shares by making a timely QEF election (or a QEF election along with a purging election), or a MTM election, all as described below.
Impact of PFIC Rules on Certain U.S. Holders. The impact of the PFIC rules on a U.S. Holder of TRC Shares or PubCo Common Shares will depend on whether the U.S. Holder has made a timely and effective election to treat TRC or PubCo as a QEF under Section 1295 of the Code, for TRC or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) TRC Shares or PubCo Common Shares, the U.S. Holder made a QEF election along with a “purging election,” or if the U.S. Holder made a MTM election, all as discussed below. Proposed Treasury Regulations provide that a QEF election made with respect to PFIC stock exchanged in a transaction treated as a reorganization under Section 368(a) of the Code does not carry over to any PFIC stock received in the reorganization. Accordingly, U.S. Holders that have made a QEF election with respect to TRC Shares should consider with their tax advisors whether to make a QEF election with respect to the PubCo Common Shares received in the TRC Amalgamation. A U.S. Holder of a PFIC that made either a timely and effective QEF election, a QEF election along with a purging election, or a MTM election is hereinafter referred to as an “Electing Shareholder.” A U.S. Holder of a PFIC that is not an Electing Shareholder is hereinafter referred to as a “Non-Electing Shareholder.”
The QEF election is made on a shareholder-by-shareholder basis and, once made, can be revoked only with the consent of the IRS. A U.S. Holder generally makes a QEF election by attaching a completed IRS Form 8621 (Return by a Shareholder of a Passive Foreign Investment Company or Qualified Electing Fund), including the information provided in a “PFIC Annual Information Statement,” to a timely filed U.S. federal income tax return for the tax year to which the election relates. Retroactive QEF elections generally may be made only by filing a protective statement
187
with such return and if certain other conditions are met or with the consent of the IRS. U.S. Holders are urged to consult their tax advisors regarding the availability and tax consequences of a retroactive QEF election under their particular circumstances.
A U.S. Holder’s ability to make a QEF election with respect to its TRC Shares or PubCo Common Shares (as applicable) is contingent upon, among other things, the provision by TRC or PubCo of certain information that would enable the U.S. Holder to make and maintain a QEF election. Upon written request, TRC and PubCo will endeavor to provide to a U.S. Holder such information as the IRS may require, including a PFIC Annual Information Statement, in order to enable the U.S. Holder to make and maintain a QEF election, but there can be no assurance that TRC or PubCo will timely provide such information that is required to make and maintain the QEF election. An Electing Shareholder making a valid and timely QEF election generally would not be subject to the adverse PFIC rules discussed above with respect to their TRC Shares or PubCo Common Shares but rather would include annually in gross income its pro rata share of the ordinary earnings and net capital gain of TRC or PubCo, whether or not such amounts are actually distributed.
As indicated above, if a U.S. Holder of TRC Shares or PubCo Common Shares has not made a timely and effective QEF election with respect to TRC or PubCo’s first taxable year as a PFIC in which the U.S. Holder held (or was deemed to hold) TRC Shares or PubCo Common Shares, such U.S. Holder generally may nonetheless qualify as an Electing Shareholder by filing on a timely filed U.S. income tax return (including extensions) a QEF election and a purging election to recognize under the rules of Section 1291 of the Code any gain that it would otherwise recognize if the U.S. Holder sold its TRC Shares or PubCo Common for their fair market value on the “qualification date.” The qualification date is the first day of TRC or PubCo’s tax year in which TRC or PubCo qualifies as a QEF with respect to such U.S. Holder. The purging election can only be made if such U.S. Holder held TRC Shares or PubCo Common Shares on the qualification date. The gain recognized by the purging election will be subject to the special tax and interest charge rules treating the gain as an excess distribution, as described above. As a result of the purging election, the U.S. Holder will increase the adjusted tax basis in its TRC Shares or PubCo Common Shares by the amount of the gain recognized and will also have a new holding period in the TRC Shares or PubCo Common Shares for purposes of the PFIC rules.
Alternatively, if a U.S. Holder, at the close of its taxable year, owns shares in a PFIC that are treated as marketable shares, the U.S. Holder may make a MTM election with respect to such shares for such taxable year. If the U.S. Holder makes a valid MTM election for the first taxable year of the U.S. Holder in which the U.S. Holder holds (or is deemed to hold) TRC Shares or PubCo Common Shares and for which TRC or PubCo is determined to be a PFIC, such holder will not be subject to the PFIC rules described above in respect to its TRC Shares or PubCo Common Shares. Instead, the U.S. Holder will include as ordinary income each year the excess, if any, of the fair market value of its TRC Shares or PubCo Common Shares at the end of its taxable year over the adjusted basis in its TRC Shares or PubCo Common Shares. The U.S. Holder also will be allowed to take an ordinary loss in respect of the excess, if any, of the adjusted basis of its TRC Shares or PubCo Common Shares over the fair market value of its TRC Shares or PubCo Common Shares at the end of its taxable year (but only to the extent of the net amount of previously included income as a result of the MTM election). The U.S. Holder’s basis in its TRC Shares or PubCo Common Shares will be adjusted to reflect any such income or loss amounts and any further gain recognized on a sale or other taxable disposition of the TRC Shares or PubCo Common Shares will be treated as ordinary income. Shareholders who hold different blocks of TRC Shares or PubCo Common Shares (generally, shares of TRC or PubCo purchased or acquired on different dates or at different prices) are urged to consult their tax advisors to determine how the above rules apply to them. The MTM election is available only for shares that are regularly traded on a national securities exchange that is registered with the SEC, including Nasdaq, or on a foreign exchange or market that the IRS determines has rules sufficient to ensure that the market price represents a legitimate and sound fair market value. No assurance can be given that the TRC Shares or PubCo Shares are considered to be regularly traded for purposes of the MTM election or whether the other requirements of this election are satisfied. If such an election is available and has been made, such U.S. Holders will generally not be subject to the special taxation rules of Section 1291 of the Code discussed herein with respect to their TRC Shares or PubCo Common Shares. However, if the MTM election is made by a Non-Electing Shareholder after the beginning of the holding period for the PFIC stock, then the Section 1291 rules will apply to certain dispositions of, distributions on and other amounts taxable
188
with respect to TRC Shares or PubCo Shares. U.S. Holders are urged to consult their tax advisers regarding the availability and tax consequences of a MTM election in respect to TRC Shares or PubCo Shares under their particular circumstances. In addition, although a U.S. Holder may be eligible to make a MTM election with respect to the PubCo Shares, no such election may be made with respect to the stock of any subsidiary PFIC of PubCo that a U.S. Holder is treated as owning because such stock is not marketable. Hence, the MTM election will not be effective to eliminate the interest charge and other income inclusion rules described above with respect to deemed dispositions of such subsidiary PFIC stock or distributions from such a subsidiary PFIC to its shareholder.
The rules dealing with PFICs and with the timely QEF election, the QEF election with a purging election, and the MTM election are very complex and are affected by various factors in addition to those described above. Accordingly, a U.S. Holder of TRC Shares or PubCo Shares is urged to consult its tax advisor concerning the application of the PFIC rules to such securities under such holder’s particular circumstances.
Tax Consequences for U.S. Holders of Owning and Disposing of PubCo Common Shares
Distributions on PubCo Common Shares. Subject to the PFIC rules described above, a U.S. Holder will generally be required to include in gross income as dividend income the amount of any distribution of cash or other property paid on PubCo Common Shares to the extent the distribution is paid out of PubCo’s current or accumulated earnings and profits (as determined under U.S. federal income tax principles). The source of such dividend income will generally be domestic unless less than 25 percent of the gross income from all sources of PubCo for the 3-year period ending with the close of its taxable year preceding the declaration of such dividends (or for such part of such period as the corporation has been in existence) was effectively connected (or treated as effectively connected other than income described in section 884(d)(2) of the Code) with the conduct of a trade or business within the United States; but only in an amount which bears the same ratio to such dividends as the gross income of the corporation for such period which was effectively connected (or treated as effectively connected other than income described in section 884(d)(2) of the Code). Distributions in excess of PubCo’s current and accumulated earnings and profits will constitute a return of capital that will be applied against and reduce (but not below zero) the U.S. Holder’s adjusted tax basis in its shares of PubCo Common Shares on a per-share basis. Any remaining excess will be treated as gain realized on the sale of PubCo Common Shares and will be treated as described below under the section entitled “Sale, Taxable Exchange or Other Taxable Disposition of PubCo Common Shares.”
With certain exceptions, and provided certain holding period requirements are met, dividends received on stock of a “qualified foreign corporation” by a non-corporate U.S. Holder will generally constitute “qualified dividends” that will be subject to U.S. federal income tax at preferential long-term capital gains rates. For this purpose, a “qualified foreign corporation” means any foreign corporation provided that: (i) the corporation was not, in the year prior to the year in which the dividend was paid, and is not, in the year in which the dividend is paid, a passive foreign investment company, (ii) certain holding period requirements are met and (iii) either (A) the corporation is eligible for the benefits of a comprehensive income tax treaty with the United States that the IRS has approved for the purposes of the qualified dividend rules or (B) the stock with respect to which such dividend was paid is readily tradable on an established securities market in the United States. While PubCo believes it will be a “qualified foreign corporation”, there can be no assurances that it does so qualify under the Code (among other reasons, there can be no assurance that the PubCo Common Shares will be treated as regularly traded on an established securities market) or that an applicable tax treaty will apply.
A U.S. Holder may be entitled, subject to a number of complex limitations and conditions (including a minimum holding period requirement), to claim a U.S. foreign tax credit in respect of Canadian income taxes, if any, withheld on the foreign source portion (as determined under U.S. federal income tax principles) of dividends received in respect of the PubCo Common Shares. A U.S. Holder who does not elect to claim a credit for any foreign income taxes paid during the taxable year may instead claim a deduction in respect of such income taxes provided
189
the U.S. Holder elects to deduct (rather than credit) all foreign income taxes for that year. Further, U.S. Treasury regulations finalized in January 2022 have imposed additional requirements that must be met for a Canadian or other foreign tax to be creditable (including requirements that a “covered withholding tax” be imposed on nonresidents in lieu of a generally applicable tax that satisfies the regulatory definition of an “income tax,” which may be unclear or difficult to determine), and these requirements may further restrict a U.S. Holder’s ability to benefit from the foreign tax credit for Canadian withholding taxes. Recent IRS guidance provides temporary relief from some of these U.S. Treasury regulations, subject to certain requirements being met, until further notice is provided by the IRS. The rules relating to computing foreign tax credits or deducting foreign taxes are extremely complex, and U.S. Holders are encouraged to consult their own tax advisors regarding the availability of foreign tax credits under their particular circumstances.
Dividends paid in Canadian dollars (including the amount of any Canadian taxes withheld therefrom, if any) will be includible in a U.S. Holder’s gross income in a U.S. dollar amount calculated by reference to the spot rate of exchange in effect on the day the Canadian dollars are actually or constructively received by the U.S. Holder, regardless of whether the dividends are converted into U.S. dollars. If the Canadian dollars are converted to U.S. dollars on the date of such receipt, a U.S. Holder generally will not recognize any foreign currency gain or loss. However, if the U.S. Holder converts the Canadian dollars into U.S. dollars on a later date, the U.S. Holder must include in gross income any gain or loss resulting from any exchange rate fluctuations. The gain or loss will be equal to the difference between (i) the U.S. dollar value of the amount included in income when the dividend was received and (ii) the amount received on the conversion of the Canadian dollars into U.S. dollars. Generally, any gain or loss resulting from currency exchange fluctuations during the period from the date the dividend is includible in a U.S. Holder’s gross income to the date such payment is converted into U.S. dollars will be foreign currency gain or loss and will be treated as ordinary income or loss. Such gain or loss generally will be treated as income from sources within the United States. U.S. Holders are encouraged to consult their own independent tax advisors regarding the treatment of foreign currency gain or loss, if any, on any Canadian dollars received that are converted into U.S. dollars on a date subsequent to actual or constructive receipt by the U.S. Holder.
Sale, Taxable Exchange or Other Taxable Disposition of PubCo Common Shares. Subject to the PFIC rules described above, a U.S. Holder generally will recognize capital gain or loss in an amount equal to the difference between the amount of cash received in the redemption and the U.S. Holder’s adjusted tax basis in the PubCo Common Shares redeemed. Any such capital gain or loss generally will be long-term capital gain or loss if the U.S. holder’s holding period for the PubCo Common Shares so disposed of exceeds one year. As described above, the holding period for the PubCo Common Shares should include the holding period for the corresponding TRC Shares if the TRC Amalgamation qualifies as a reorganization under Section 368(a) of the Code. Long-term capital gains recognized by non-corporate U.S. holders generally will be eligible to be taxed at reduced rates. The deductibility of capital losses is subject to limitations.
U.S. Holders who hold different blocks of PubCo Common Shares (including as a result of holding different blocks of TRC shares purchased or acquired on different dates or at different prices) should consult their tax advisors to determine how the above rules apply to them.
Additional Reporting Requirements. Certain U.S. Holders may be required to file an IRS Form 926 (Return by a U.S. Transferor of Property to a Foreign Corporation) to report a transfer of property (including cash) to PubCo. Substantial penalties may be imposed on a U.S. Holder that fails to comply with this reporting requirement, and the period of limitations on assessment and collection of U.S. federal income taxes will be extended in the event of a failure to comply. Furthermore, certain U.S. Holders who are individuals and certain entities will be required to report information with respect to such U.S. Holder’s investment in “specified foreign financial assets” on IRS Form 8938 (Statement of Specified Foreign Financial Assets), subject to certain exceptions. Specified foreign financial assets generally include any financial account maintained with a non-U.S. financial institution and should also include PubCo Common Shares if they are not held in an account maintained with a financial institution. U.S. Holders are urged to consult their tax advisors regarding the foreign financial asset and other reporting obligations and their application to an investment in PubCo Common Shares.
190
Treasury Regulations meant to require the reporting of certain tax shelter transactions could be interpreted to cover transactions generally not regarded as tax shelters, including certain foreign currency transactions. Under the applicable Treasury Regulations, certain transactions are required to be reported to the IRS including, in certain circumstances, a sale, exchange, retirement or other taxable disposition of foreign currency, to the extent that such sale, exchange, retirement or other taxable disposition results in a tax loss in excess of a threshold amount. You should consult your tax advisor to determine the tax return obligations, if any, with respect to PubCo Common Shares and the receipt of Canadian dollars in respect thereof, including any requirement to file IRS Form 8886 (Reportable Transaction Disclosure Statement).
Non-U.S. Holders
Effects of the TRC Amalgamation to Non-U.S. Holders
The TRC Amalgamation is not expected to result in any U.S. federal income tax consequences to Non-U.S. Holders of TRC Shares.
Tax Consequences for Non-U.S. Holders of Owning and Disposing of PubCo Common Shares
Distributions on PubCo Common Shares. Distributions of cash or property to a Non-U.S. Holder in respect of PubCo Common Shares received in the TRC Amalgamation will generally constitute dividends for U.S. federal income tax purposes to the extent paid from PubCo’s current or accumulated earnings and profits, as determined under U.S. federal income tax principles. While a portion of such dividends may be treated as derived from U.S. sources, as discussed above under “Tax Consequences for U.S. Holders of Owning and Disposing of PubCo Common Shares — Distributions on PubCo Common Shares”, such U.S. source dividends should be exempt from U.S. federal withholding tax under Section 871(i)(2)(D) and Section 881(d) of the Code.
Dividends that are effectively connected with the conduct of a trade or business by the Non-U.S. Holder within the United States (and, if required by an applicable income tax treaty, are attributable to a U.S. permanent establishment or fixed base of the Non-U.S. Holder) are not subject to such withholding tax, provided certain certification and disclosure requirements are satisfied (generally by providing an IRS Form W-8ECI). Instead, such dividends are subject to United States federal income tax on a net income basis in the same manner as if the Non-U.S. Holder were a United States person as defined under the Code. Any such effectively connected dividends received by a foreign corporation may be subject to an additional “branch profits tax” at a 30% rate or such lower rate as may be specified by an applicable income tax treaty.
Gain on Disposition of PubCo Common Shares. Subject to the below discussion of backup withholding and the Foreign Account Tax Compliance Act (as defined below), any gain realized by a Non-U.S. Holder on the taxable disposition of PubCo Common Shares generally will not be subject to U.S. federal income tax unless:
• the gain is effectively connected with a trade or business of the Non-U.S. Holder in the United States (and, if required by an applicable income tax treaty, is attributable to a United States permanent establishment or fixed base of the Non-U.S. Holder); or
• the Non-U.S. Holder is an individual who is present in the United States for a period or periods aggregating 183 days or more in the taxable year of the disposition, and certain other conditions are met.
A non-corporate Non-U.S. Holder described in the first bullet point immediately above will be subject to tax on the net gain derived from the sale of PubCo Common Shares under regular U.S. federal income tax rates. An individual Non-U.S. Holder described in the second bullet point immediately above will be subject to a flat 30% tax on the gain derived from the sale of PubCo Common Shares, which may be offset by certain United States source capital losses, even though the individual is not considered a resident of the United States, provided that the individual has timely filed U.S. federal income tax returns with respect to such losses. If a Non-U.S. Holder that is a foreign corporation falls under the first bullet point immediately above, it will be subject to tax on its net gain in the same manner as if it were a United States person as defined under the Code and, in addition, may be subject to the “branch profits tax” equal to 30% (or such lower rate as may be specified by an applicable income tax treaty) of its effectively connected earnings and profits, subject to adjustments.
191
Information Reporting and Backup Withholding
PubCo generally must report annually to the IRS and to each Non-U.S. Holder the amount of dividends paid to such holder and the tax withheld with respect to such dividends, regardless of whether withholding was required. Copies of the information returns reporting such dividends and withholding may also be made available to the tax authorities in the country in which the Non-U.S. Holder resides under the provisions of an applicable income tax treaty.
A Non-U.S. Holder generally will be subject to backup withholding for dividends paid to such holder unless such holder certifies under penalty of perjury that it is a Non-U.S. Holder (and the payor does not have actual knowledge or reason to know that such holder is a United States person as defined under the Code), or such holder otherwise establishes an exemption. Information reporting and, depending on the circumstances, backup withholding generally will apply to the proceeds of a sale of PubCo Common Shares within the United States or conducted through certain United States-related financial intermediaries, unless the beneficial owner certifies under penalty of perjury that it is a Non-U.S. Holder (and the payor does not have actual knowledge or reason to know that the beneficial owner is a United States person as defined under the Code), or such owner otherwise establishes an exemption.
Any amounts withheld under the backup withholding rules may be allowed as a refund or a credit against a Non-U.S. Holder’s U.S. federal income tax liability provided the required information is timely furnished to the IRS.
Foreign Account Tax Compliance Act
Sections 1471 through 1474 of the Code and the Treasury Regulations and administrative guidance promulgated thereunder (commonly referred as the “Foreign Account Tax Compliance Act” or “FATCA”) generally impose withholding at a rate of 30% in certain circumstances on dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, securities (including PubCo Common Shares) which are held by or through certain foreign financial institutions (including investment funds), unless any such institution (i) enters into, and complies with, an agreement with the IRS to report, on an annual basis, information with respect to interests in, and accounts maintained by, the institution that are owned by certain U.S. persons and by certain non-U.S. entities that are wholly or partially owned by U.S. persons and to withhold on certain payments or (ii) if required under an intergovernmental agreement between the United States and an applicable foreign country, reports such information to its local tax authority, which will exchange such information with the U.S. authorities. An intergovernmental agreement between the United States and an applicable foreign country may modify these requirements. Accordingly, the entity through which PubCo Common Shares are held will affect the determination of whether such withholding is required. Similarly, dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, PubCo Common Shares held by an investor that is a non-financial non-U.S. entity that does not qualify under certain exceptions will generally be subject to withholding at a rate of 30%, unless such entity either (i) certifies to the applicable withholding agent that such entity does not have any “substantial United States owners” or (ii) provides certain information regarding the entity’s “substantial United States owners,” which will in turn be provided to the U.S. Department of Treasury.
Under the applicable Treasury Regulations and administrative guidance, withholding under FATCA generally applies to payments of dividends in respect of PubCo Common Shares. While withholding under FATCA generally would also apply to payments of gross proceeds from the sale or other disposition of securities (including PubCo Common Shares), proposed Treasury Regulations eliminate FATCA withholding on payments of gross proceeds entirely. Taxpayers generally may rely on these proposed Treasury Regulations until final Treasury Regulations are issued. All holders should consult their tax advisors regarding the possible implications of FATCA on their investment in PubCo Common Shares.
192
MATERIAL CANADIAN TAX CONSIDERATIONS
Plum Shareholders
The following is, as of the date hereof, a summary of the principal Canadian federal income tax considerations pursuant to the Income Tax Act (Canada) (the “Tax Act”) generally applicable to a Plum Shareholder that participates in the Business Combination, including the Domestication, Plum Amalgamation, TRC Amalgamation, and that will thereby acquire and hold PubCo Common Shares, and who, for purposes of the Tax Act and at all relevant times, (i) holds any Plum Class A Shares or Plum Class B Shares as the beneficial owner thereof and as capital property, (ii) will hold PubCo Common Shares as the beneficial owner thereof and as capital property, and (iii) deal at arm’s length with Plum and is not affiliated with Plum or PubCo (a “Plum Holder”). Generally, Plum Class A Shares, Plum Class B Shares and PubCo Common Shares will be considered to be capital property to a Plum Holder provided the Plum Holder does not hold such security in the course of carrying on a business of trading or dealing in securities and has not acquired such security in one or more transactions considered to be an adventure or concern in the nature of trade.
This summary is not applicable to a Plum Holder that is resident in Canada. Such Plum Holders, if any, should consult their own tax advisors with respect to participating in the Business Combination.
This summary is based upon the current provisions of the Tax Act, taking into account all proposed amendments to the Tax Act publicly announced by or on behalf of the Minister of Finance (Canada) prior to the date hereof (the “Tax Proposals”), and an understanding of the current administrative practices and assessing policies of the Canada Revenue Agency (the “CRA”) published in writing by it and made publicly available prior to the date hereof. This summary assumes the Tax Proposals will be enacted in the form proposed; however, no assurance can be given that the Tax Proposals will be enacted in the form proposed, or at all.
This summary is not exhaustive of all possible Canadian federal income tax considerations and, except for the Tax Proposals, does not otherwise take into account or anticipate any changes in the law, whether by way of legislative, governmental or judicial decision or action, or in the administrative practices or assessing policies of the CRA, nor does it take into account other federal or any provincial, territorial or foreign tax laws or considerations, which may differ significantly from the tax considerations described herein.
This summary is of a general nature only and is not intended to be, nor should it be construed to be, legal or tax advice to any particular Plum Holder or prospective Plum Holder, and no representations with respect to the income tax consequences to any Plum Holder or prospective Plum Holder are made. Consequently, Plum Holders and prospective Plum Holders should consult their own tax advisors for advice with respect to the tax consequences to them of acquiring Common Shares pursuant to this Offering, having regard to their particular circumstances.
Non-Residents of Canada
This summary is generally applicable to a Plum Holder who, for purposes of the Tax Act and any applicable tax treaty or convention and at all relevant times, is neither resident nor deemed to be resident in Canada and does not use or hold, and is not deemed to use or hold, Plum Class A Shares, Plum Class B Shares and PubCo Common Shares in connection with a business carried on in Canada (each, a “Non-Resident Plum Holder”).
Special considerations, which are not discussed in this summary, may apply to a Non-Resident Plum Holder that is an insurer that carries on an insurance business in Canada and elsewhere or is an “authorized foreign bank” (as defined in the Tax Act). Such Non-Resident Plum Holders should consult their own advisors.
Domestication
A Non-Resident Plum Holder will not be considered to have disposed of such Non-Resident Plum Holder’s Plum Class A Shares or Plum Class B Shares, as applicable, as a consequence of the Domestication. Accordingly, a Non-Resident Plum Holder will not be subject to tax under the Tax Act in connection with the Domestication.
193
Plum Amalgamation
The automatic division of a Plum Unit into one Plum Class A Share and one-third of one Plum Warrant pursuant to the Plum Amalgamation and after the Domestication and on the Closing Date will not result in a disposition of such Plum Unit. Accordingly, a Non-Resident Plum Holder will not be subject to tax under the Tax Act in connection with such automatic division.
The exchange by a Non-Resident Plum Holder of Plum Class A Shares or Plum Class B Shares, as applicable, for PubCo Common Shares will constitute a disposition of such Plum Class A Share or Plum Class B Share, as applicable, for purposes of the Tax Act, for proceeds of disposition equal to the adjusted cost base to the Non-Resident Plum Holder of the exchanged Plum Class A Shares or Plum Class B Shares. Accordingly, a Non-Resident Plum Holder will realize neither a gain nor a loss in connection with the exchange of Plum Class A Shares or Plum Class B Shares, as applicable, for PubCo Common Shares. The cost to a Non-Resident Plum Holder of PubCo Common Shares so acquired will be equal to the adjusted cost base of the Plum Class A Shares or Plum Class B Shares so exchanged. The adjusted cost base to a Non-Resident Plum Holder of a particular PubCo Common Share will be determined by averaging the aggregate cost to a Non-Resident Plum Holder of all PubCo Common Shares.
TRC Amalgamation
The TRC Amalgamation will not result in a disposition of PubCo Common Shares held by any particular Non-Resident Plum Holder. Accordingly, a Non-Resident Plum Holder will not be subject to tax under the Tax Act in connection with the TRC Amalgamation.
Disposition of PubCo Common Shares
A Non-Resident Plum Holder generally will not be subject to tax under the Tax Act in respect of any capital gain realized by such Non-Resident Plum Holder on a disposition or deemed disposition of PubCo Common Shares, unless the PubCo Common Shares constitute or are deemed to constitute “taxable Canadian property” (as defined in the Tax Act) of the Non-Resident Plum Holder at the time of the disposition and the Non-Resident Plum Holder is not entitled to relief under an applicable income tax convention between Canada and the country in which the Non-Resident Plum Holder is resident at the time of the disposition.
Generally, as long as the Common Shares are listed on a “designated stock exchange” as defined in the Tax Act (which currently includes the NASDAQ) at the time of disposition, the PubCo Common Shares will not constitute taxable Canadian property of a Non-Resident Plum Holder at that time, unless at any time during the 60-month period immediately preceding the disposition the following two conditions are met concurrently: (a) the Non-Resident Plum Holder, persons with which the Non-Resident Plum Holder does not deal at arm’s length, partnerships whose members include, either directly or indirectly through one or more partnerships, the Non-Resident Plum Holder and/or persons which do not deal at arm’s length with the Non-Resident Plum Holder, or any combination of the foregoing, owned 25% or more of the issued shares of any class or series of shares of the capital stock of PubCo, and (b) more than 50% of the fair market value of the PubCo Common Shares was derived directly or indirectly, from one or any combination of real or immovable property situated in Canada, “Canadian resource properties” or “timber resource properties” (each as defined in the Tax Act), and options in respect of or interests in, or for civil law rights in, any such property (whether or not such property exists). Notwithstanding the foregoing, a PubCo Common Share may also be deemed to be taxable Canadian property to a Non-Resident Plum Holder in certain other circumstances under the Tax Act.
If PubCo Common Shares are taxable Canadian property of a Non-Resident Plum Holder and any capital gain that would be realized on the disposition thereof is not exempt from tax under the Tax Act or pursuant to an applicable income tax treaty or convention, then on the disposition or deemed disposition of a PubCo Common Share by a Non-Resident Plum Holder (other than to PubCo, unless purchased by PubCo in the open market in the manner in which shares are normally purchased by any member of the public in an open market), the Non-Resident Plum Holder will generally realize a capital gain (or a capital loss) equal to the amount by which the proceeds of disposition in respect of such PubCo Common Share, net of any reasonable costs of disposition, exceed (or are exceeded by) the
194
adjusted cost base of the PubCo Common Share to the Non-Resident Plum Holder. For the purpose of determining the adjusted cost base to a Non-Resident Plum Holder of PubCo Common Shares, when a PubCo Common Share is acquired, the cost of the newly acquired PubCo Common Share will be averaged with the adjusted cost base of all of the PubCo Common Shares owned by the Non-Resident Plum Holder as capital property immediately before that acquisition. The adjusted cost base of a PubCo Common Share to a Non-Resident Plum Holder may be subject to certain adjustments.
Generally, one-half of the amount of any capital gain (a “taxable capital gain”) realized by a Non-Resident Plum Holder in a taxation year must be included in computing such Non-Resident Plum Holder’s income for that year, and one-half of any capital loss (an “allowable capital loss”) realized by a Resident Plum Holder in a taxation year must be deducted from any taxable capital gains realized by the Resident Plum Holder in the year, subject to and in accordance with the provisions of the Tax Act.
Non-Resident Plum Holders whose PubCo Common Shares may constitute taxable Canadian property should consult their own advisors.
Dividends on PubCo Common Shares
Dividends paid or credited, or deemed to be paid or credited, to a Non-Resident Plum Holder on the PubCo Common Shares will be subject to Canadian withholding tax under the Tax Act at the rate of 25% of the gross amount of the dividend unless reduced by the terms of an applicable tax treaty or convention between Canada and the country in which the Non-Resident Plum Holder is resident. For example, under the Canada-United States Tax Convention (1980) (the “Treaty”), the withholding tax rate in respect of a dividend paid to a person who is the beneficial owner of the dividend and who is resident in the United States for the purposes of, and is entitled to full benefits under, the Treaty is generally reduced to 15%.
TRC Shareholders
The following is, as of the date hereof, a summary of the principal Canadian federal income tax considerations under the Tax Act in respect of the Plan of Arrangement that are generally applicable to a beneficial owner of TRC Common Shares who at all relevant times and for purposes of the Tax Act: (a) deals at arm’s length with each of TRC, Plum and PubCo; (b) is not and will not be affiliated with each of TRC, Plum and PubCo; and (c) holds TRC Common Shares, and will hold PubCo Common Shares received following the TRC Amalgamation pursuant to the Plan of Arrangement, as capital property (each such beneficial owner in this section, a “TRC Holder”).
This summary is based upon the current provisions of the Tax Act, taking into account all of the Tax Proposals, and an understanding of the current administrative practices and assessing policies of the CRA published in writing by it and made publicly available prior to the date hereof. This summary assumes the Tax Proposals will be enacted in the form proposed; however, no assurance can be given that the Tax Proposals will be enacted in the form proposed, or at all.
This summary is not applicable to a TRC Holder: (a) that is a “financial institution” (as defined in the Tax Act for the purposes of the “mark-to-market rules”); (b) that is a “specified financial institution” (as defined in the Tax Act); (c) an interest in which is, or whose TRC Common Shares are, a “tax shelter” or a “tax shelter investment” (as defined in the Tax Act); (d) whose functional currency for purposes of the Tax Act is the currency of a country other than Canada; (e) that is a “foreign affiliate” (as defined in the Tax Act) of a taxpayer resident in Canada; (f) that has entered into or will enter into a “synthetic disposition arrangement”, “synthetic equity arrangement, or a “derivative forward agreement” (as such terms are defined in the Tax Act) with respect to TRC Common Shares or PubCo Common Shares; (g) that receives dividends on its PubCo Common Shares under or as part of a “dividend rental arrangement” (as defined in the Tax Act); or (h) that is exempt from tax under Part I of the Tax Act. All such TRC Holders should consult with their own tax advisors to determine the tax consequences to them of the Plan of Arrangement.
This summary is not exhaustive of all possible Canadian federal income tax considerations applicable to TRC Holders in respect of the Plan of Arrangement and, except for the Tax Proposals, does not otherwise take into account or anticipate any changes in the law, whether by way of legislative, governmental or judicial decision
195
or action, or in the administrative practices or assessing policies of the CRA, nor does it take into account other federal or any provincial, territorial or foreign tax laws or considerations, which may differ significantly from the tax considerations described herein.
This summary is of a general nature only and is not intended to be, nor should it be construed to be, legal or tax advice to any particular TRC Holder, and no representations with respect to the income tax consequences to any TRC Holder are made. Consequently, TRC Holders should consult their own tax advisors for advice with respect to the tax consequences to them of acquiring Common Shares pursuant to the Plan of Arrangement, having regard to their particular circumstances.
This summary is not applicable to any holder of conversion or exchange rights to acquire TRC Common Shares, and the tax considerations relevant to such holders are not discussed herein. Any such Persons should consult their own tax advisor with respect to the tax consequences of the Plan of Arrangement having regard to their particular circumstances.
Currency Conversion
Subject to certain exceptions that are not discussed herein, for the purposes of the Tax Act, all amounts relating to the acquisition, holding or disposition of securities (including dividends, adjusted cost base and proceeds of disposition) must be expressed in Canadian dollars. Amounts denominated in another currency must be converted into Canadian dollars as determined in accordance with the Tax Act, generally based on the Bank of Canada spot exchange rate on the date such amounts arise or such other rate of exchange as is acceptable to the Minister of National Revenue (Canada). The amount of dividends to be included in the income of, and the amount of capital gains or capital losses realized by, a TRC Holder may be affected by fluctuation in the relevant Canadian dollar exchange rate.
TRC Holders Resident in Canada
This portion of the summary is generally applicable to a TRC Holder who, at all relevant times, for purposes of the Tax Act and any applicable income tax treaty or convention is, or is deemed to be, resident in Canada (a “Resident TRC Holder”).
Certain Resident TRC Holders whose TRC Common Shares might not otherwise qualify as capital property may, in certain circumstances, be eligible to make an irrevocable election in accordance with subsection 39(4) of the Tax Act to have their TRC Common Shares, PubCo Common Shares received under the Plan of Arrangement and every other “Canadian security” (as defined in the Tax Act) owned by such Resident TRC Holder in the taxation year in which the election is made or in any subsequent taxation year, be deemed to be capital property. Resident TRC Holders should consult their own tax advisors as to whether they hold TRC Common Shares or will hold their PubCo Common Shares as capital property and whether such election can or should be made.
TRC Amalgamation
Under the Tax Act, a Resident TRC Holder who is not a Dissenting Resident TRC Holder (as defined below) should not realize a capital gain or a capital loss as a result of the exchange of that Resident TRC Holder’s TRC Common Shares for PubCo Common Shares (and no other consideration) pursuant to the TRC Amalgamation in the Plan of Arrangement. The cost to that Resident Holder of the PubCo Common Shares received on the TRC Amalgamation will be equal to the total adjusted cost base of the TRC Common Shares to that Resident TRC Holder immediately before the TRC Amalgamation.
A Resident TRC Holder who, under the Plan of Arrangement, is paid for their TRC Common Shares pursuant to the valid exercise of a statutory dissent right (a “Dissenting Resident TRC Holder”) will be considered to have disposed of those TRC Common Shares for proceeds of disposition equal to the amount paid, other than interest awarded by a court. Under certain published administrative practices of the CRA, such a disposition of TRC Common Shares should generally give rise to a capital gain or capital loss (rather than a deemed dividend) equal to the amount by which the proceeds of disposition of those TRC Common Shares exceed (or are exceeded by) the aggregate adjusted cost base of those TRC Common Shares to that Dissenting Resident TRC Holder. Because of the
196
uncertainty under the Tax Act as to whether such amount paid to a Dissenting Resident TRC Holder will give rise to a capital gain (or capital loss) rather than a deemed dividend, Dissenting Resident TRC Holders should consult their own tax advisors in this regard.
Dividends on PubCo Common Shares
In the case of a Resident TRC Holder who is an individual (including certain trusts), dividends (including deemed dividends) received on PubCo Common Shares will be included in the Resident TRC Holder’s income and be subject to the gross up and dividend tax credit rules applicable to taxable dividends received by an individual from taxable Canadian corporations, including the enhanced gross up and dividend tax credit for “eligible dividends” properly designated as such by PubCo. There may be limitations on the ability of PubCo to designate dividends as eligible dividends.
In the case of a Resident TRC Holder that is a corporation, such dividends (including deemed dividends) received on PubCo Common Shares will be included in the Resident TRC Holder’s income and will normally be deductible in computing such Resident TRC Holder’s taxable income, subject to certain restrictions and special rules under the Tax Act. In certain circumstances, subsection 55(2) of the Tax Act will treat a taxable dividend received or deemed to be received by a Resident TRC Holder that is a corporation as proceeds of disposition or a capital gain. Resident TRC Holders that are corporations should consult their own tax advisors with respect to the application of subsection 55(2) of the Tax Act having regard to their own circumstances.
A Resident TRC Holder that is a “private corporation” or “subject corporation,” as such terms are defined in the Tax Act, may be liable to pay a refundable tax under Part IV of the Tax Act on dividends received or deemed to be received on PubCo Common Shares to the extent that such dividends are deductible in computing the Resident TRC Holder’s taxable income for the year.
Disposition of PubCo Common Shares
A Resident TRC Holder who disposes of, or is deemed to have disposed of, a PubCo Common Share (other than to PubCo, unless purchased by PubCo in the open market in the manner in which shares are normally purchased by any member of the public in the open market) will realize a capital gain (or incur a capital loss) equal to the amount by which the proceeds of disposition in respect of the PubCo Common Share exceed (or are exceeded by) the aggregate of the adjusted cost base to the Resident TRC Holder of such PubCo Common Share immediately before the disposition or deemed disposition and any reasonable expenses incurred for the purpose of making the disposition. The adjusted cost base to a Resident TRC Holder of a PubCo Common Share will be determined by averaging the cost of that PubCo Common Share with the adjusted cost base (determined immediately before the acquisition of the PubCo Common Share) of all other PubCo Common Shares held as capital property at that time by the Resident TRC Holder. The tax treatment of capital gains and capital losses is discussed in greater detail below under the subheading “— Taxation of Capital Gains and Losses.”
Taxation of Capital Gains and Losses
Generally, one-half of the amount of any capital gain (a “taxable capital gain”) realized by a Resident TRC Holder in a taxation year must be included in computing such Resident TRC Holder’s income for that year, and one-half of any capital loss (an “allowable capital loss”) realized by a Resident TRC Holder in a taxation year must be deducted from any taxable capital gains realized by the Resident TRC Holder in the year, subject to and in accordance with the provisions of the Tax Act. The Tax Proposals propose to increase the capital gains inclusion rate from one half to two thirds for corporations and trusts, and from one half to two thirds for individuals on the portion of capital gains realized in a taxation year that exceed C$250,000. These Tax Proposals are intended to apply for capital gains realized on or after June 25, 2024, subject to certain transitional rules. Resident TRC Holders are advised to consult advisors regarding the possible implications of these Tax Proposals in their particular circumstances.
The amount of any capital loss realized on the disposition or deemed disposition of PubCo Common Shares by a Resident TRC Holder that is a corporation may be reduced by the amount of dividends received or deemed to have been received by it on such shares or shares substituted for such shares to the extent and in the circumstances
197
specified by the Tax Act. Similar rules may apply where a Resident TRC Holder that is a corporation is a member of a partnership or a beneficiary of a trust that owns PubCo Common Shares, directly or indirectly, through a partnership or trust. Resident TRC Holders to whom these rules may be relevant should consult their own tax advisors.
Minimum Tax
Capital gains realized (or deemed to be realized) and dividends received (or deemed to be received) by a Resident TRC Holder that is an individual or a trust, other than certain specified trusts, may give rise to minimum tax under the Tax Act. Such Resident TRC Holders should consult their own advisors with respect to the application of the minimum tax.
Additional Refundable Tax
A Resident TRC Holder that is throughout the relevant taxation year a “Canadian-controlled private corporation” (as defined in the Tax Act) or “substantive CCPC” (as defined in the Tax Act) also may be liable to pay a special additional tax (refundable in certain circumstances) on its “aggregate investment income” (as defined in the Tax Act) for the year which will generally include taxable capital gains and dividends.
TRC Holders Not Resident in Canada
The following portion of this summary is generally applicable to a TRC Holder who, for purposes of the Tax Act and at all relevant times, is neither resident nor deemed to be resident in Canada and does not use or hold, and will not be deemed to use or hold, PubCo Common Shares in a business carried on in Canada (each, a “Non-Resident TRC Holder”).
Special considerations, which are not discussed in this summary, may apply to a Non-Resident TRC Holder that is (a) an insurer that carries on an insurance business in Canada and elsewhere; (b) an “authorized foreign bank” as defined in the Tax Act; or (c) a “foreign affiliate,” as defined in the Tax Act, of a person resident in Canada. Such Non-Resident TRC Holders should consult their own advisors.
TRC Amalgamation
Under the Tax Act, a Non-Resident TRC Holder who is not a Dissenting Non-Resident TRC Holder (as defined below) should not realize a capital gain or a capital loss as a result of the exchange of that Non-Resident Holder’s TRC Common Shares for PubCo Common Shares (and no other consideration) pursuant to the Amalgamation. The cost to that Non-Resident TRC Holder of the PubCo Common Shares received on the TRC Amalgamation will be equal to the total adjusted cost base of the TRC Common Shares to that Non-Resident Holder immediately before the TRC Amalgamation.
A Non-Resident TRC Holder who, under the Plan of Arrangement, is paid for their TRC Common Shares pursuant to the valid exercise of a statutory dissent right (a “Dissenting Non-Resident TRC Holder”) will be considered to have disposed of those TRC Common Shares for proceeds of disposition equal to the amount paid, other than interest awarded by a court. Under certain published administrative practices of the CRA, such a disposition of TRC Common Shares should generally give rise to a capital gain or capital loss (rather than a deemed dividend) equal to the amount by which the proceeds of disposition of those TRC Common Shares exceed (or are exceeded by) the aggregate adjusted cost base of those TRC Common Shares to that Dissenting Non-Resident TRC Holder. Because of the uncertainty under the Tax Act as to whether such amount paid to a Dissenting Non-Resident TRC Holder will give rise to a capital gain (or capital loss) rather than a deemed dividend, Dissenting Non-Resident TRC Holders should consult their own tax advisors in this regard. Any interest awarded by a court and paid by TRC or PubCo to a Dissenting Non-Resident TRC Holder in connection with the valid exercise of such holder’s statutory dissent rights should not be subject to withholding tax under the Tax Act.
198
Taxation of Dividends
Dividends paid or credited, or deemed to be paid or credited, to a Non-Resident TRC Holder on the PubCo Common Shares will generally be subject to the consequences above under the heading “— Plum Shareholders — Non-Residents of Canada — Dividends on PubCo Common Shares”.
Disposition of PubCo Common Shares
A Non-Resident TRC Holder that disposes, or is deemed to dispose, of PubCo Common Shares will generally be subject to the consequences above under the heading “— Plum Shareholders — Non-Residents of Canada — Disposition of PubCo Common Shares”.
199
PubCo Closing Articles
This section describes the material provisions of the PubCo Closing Articles which will govern the rights of the PubCo Shareholders after the consummation of the TRC Amalgamation but does not purport to describe all of the terms thereof. The following summary is qualified in its entirety by reference to the complete text of the form of the PubCo Closing Articles, attached hereto as Annex E. Plum Shareholders and other interested parties are urged to read the PubCo Closing Articles in their entirety.
Pursuant to the terms of the Business Combination Agreement, the PubCo Closing Articles will become the articles of PubCo in accordance with the terms of the Plan of Arrangement effective as of the Plum Amalgamation Effective Time. For more information about the PubCo Closing Articles, see the subsections entitled ““Proposal No. 1 — The Domestication Proposal,” “Proposal No. 2 — The Business Combination Proposal,” “Proposal No. 3 — The Advisory Organizational Documents Proposals”, “Proposal No. 4 — The Incentive Plan Proposal” and “Proposal No. 5 — The Adjournment Proposal.”
Shares and Share Certificates
The authorized share structure of PubCo consists of shares of the classes described in the Notice of Articles of PubCo. The directors may resolve for specific shares, or any or all classes shares in the capital of PubCo to be uncertificated shares. For the certificated shares registered in a shareholder’s name, such shareholder is entitled to one share certificate for each class or series of such shares or a non-transferable written acknowledgement of such shareholder’s right to obtain such a share certificate. Shareholders are entitled to obtain a replacement for a share certificate or acknowledgement if the share certificate or acknowledgement is worn out, defaced, lost, stolen or destroyed.
Issue of Shares
PubCo may allot, issue, sell or otherwise dispose of unissued shares, and issued shares held by PubCo. The issue price for a share with par value must be equal to or greater than the par value of the share. PubCo may pay a reasonable commission or allow a reasonable discount to any person in consideration of that person’s purchase or agreement to purchase the shares. No share may be issued until it is fully paid. PubCo may issue share purchase warrants, options and rights upon such terms and conditions as the directors determine.
Share Transfers
A transfer of a share must not be registered unless PubCo, the transfer agent or the registrar has received a written instrument of transfer in respect of the share, the share certificate if such share certificate has been issued by PubCo, the non-transferable written acknowledgment of the shareholder’s right to obtain a share certificate if such acknowledgement has been issued by PubCo and, such other evidence if any as PubCo, the transfer agent or the registrar may require to prove the transfer of the share.
Purchase, Redeem or Otherwise Acquire Shares
If authorized by the directors, PubCo may purchase, redeem or otherwise acquire any of its shares at the price and upon the terms determined by the directors.
PubCo must not make a payment or provide any other consideration to purchase, redeem or otherwise acquire any of its shares if there are reasonable grounds for believing that PubCo is insolvent.
Alterations
PubCo may, by ordinary resolution or a resolution of the directors, create or eliminate one more classes or series of shares, increase or reduce the maximum number of shares authorized to be issued in any class or series of shares, subdivide or consolidate all or any of its unissued or fully paid issued shares, decrease or the par value of shares, increase the par value of shares if none of the shares of that class of shares are allotted or issued, change all or any of its unissued or fully paid issued shares with par value into shares without par value or vice versa, alter the identifying name of any of its shares, or otherwise alter its shares.
200
PubCo may create, vary or delete special rights or restrictions attached to any class or series of shares.
PubCo may change its name or adopt or change any translation of its name by resolution of the directors.
PubCo may alter the PubCo Closing Articles by ordinary resolution or by resolution of the directors.
Meetings of Shareholders
PubCo must hold its first annual general meeting within 18 months after the date on which it was incorporated, and after that must hold an annual general meeting at least once in each calendar year and not more than 15 months after the last annual reference date. If all the shareholders who are entitled to vote at an annual general meeting consent in writing by a unanimous resolution to all of the business that is required to be transacted at that annual general meeting, the annual general meeting is deemed to have been held on the date of the unanimous resolution.
The board of directors may call a meeting of shareholders at any time. PubCo must provide notice of the date, time and location of any meeting of shareholders to each shareholder entitled to attend the meeting at least 10 days before the meeting or, if PubCo is a public company, 21 days before the meeting. If the meeting of shareholders includes special business, the notice of the meeting must state the general nature of the special business; and, if the special business includes considering, approving, ratifying, adopting or authorizing any document or the signing of or giving of effect to any document, have attached to it a copy of the document or state that a copy of the document will be available for inspection by shareholders at the Company’s records office, or at such other reasonably accessible location in British Columbia as is specified in the notice during statutory business hours on any one or more specified days before the day set for the holding of the meeting. The directors may set a record date for notice and a record date for voting.
Any general meeting may be held in any location in or outside of British Columbia. The directors may determine that a meeting of shareholders be held by telephonic, electronic, hybrid or other communication facilities. Any vote at a meeting of shareholders may be held entirely or partially by means of telephonic, electronic, hybrid or other communication medium.
Proceedings at Meetings of Shareholders
The following business is considered “special business” at a meeting of shareholders:
(a) at a meeting of shareholders that is not an annual general meeting, all business is special business except business relating to the conduct of or voting at the meeting;
(b) at an annual general meeting, all business is special business except for:
i. business relating to the conduct of or voting at the meeting;
ii. consideration of any financial statements of the Company presented to the meeting;
iii. consideration of any reports of the directors or auditor;
iv. the setting or changing of the number of directors;
v. the election or appointment of directors;
vi. the appointment of an auditor;
vii. the setting of the remuneration of an auditor;
viii. business arising out of a report of the directors not requiring the passing of a special resolution or an exceptional resolution;
ix. any other business which may be transacted at a meeting of shareholders without prior notice of the business being given to the shareholders.
The majority of votes required for the Company to pass a special resolution at a general meeting of shareholders is two-thirds of the votes cast on the resolution.
201
Quorum for the transaction of business at a meeting of shareholders is at least one person who is, or who represents by proxy, one or more shareholders who, in the aggregate, hold at least five percent of the issued shares entitled to be voted at the meeting. If there is only one shareholder entitled to vote at a meeting of shareholders, the quorum is that shareholder. If a quorum is present at the opening of any meeting of shareholders, the shareholders present or represented may proceed with the business of the meeting notwithstanding that a quorum is not present throughout the meeting. If a quorum is not present within one-half hour from the time set for holding of the meeting of shareholders, in the case of a general meeting requisitioned by shareholders, the meeting is dissolved, and in the case of any other meeting of shareholders, the meeting stands adjourned to the same day in the next week at the same time and place.
At a meeting of shareholders, in addition to the shareholders and proxyholders, the directors, the president, the secretary, the assistant secretary, any lawyer of PubCo, the auditor of PubCo, any persons invited by the directors or the chair and any persons required to be present under legislation are entitled to be present.
At a meeting of shareholders, the chair shall be the chair of the board or, if the chair of the board is absent or unwilling to act as chair, the president.
If a poll is demanded at a meeting of shareholders, the poll must be taking at the meeting or within seven days after the date of the meeting, and the result of the poll is deemed to be the decision of the meeting. The demand for the poll may be withdrawn by the person who demanded it. A shareholder entitled to more than one vote need not cast all the votes in the same way on a poll.
Votes of Shareholders
On a vote by a show of hands, every shareholder or proxyholder present entitled to vote on the matter has one vote. On a poll, every shareholder entitled to vote has one vote in respect of each share entitled to be voted on the matter and held by such shareholder. Every shareholder of PubCo entitled to vote at a meeting of shareholders may, by proxy, appoint one or more (but not more than two) proxy holders to attend the meeting and act with the powers conferred by the proxy. A proxy may be revoked by a signed instrument in writing received at the registered office of PubCo up to the last business day before the meeting date or at the meeting by the chair of the meeting.
Directors
The first directors are the persons designated as directors of the Company in the Notice of Articles. The number of directors is set at the number of directors that is equal to the number of PubCo’s first directors — if PubCo is a public company, the number of directors is set at the greater of three and the most recently set of the number of directors set by a resolutions of the directors, and if PubCo is not a public company, the number of directors is set by a resolution of the directors.
The shareholders may elect or appoint the directors needed to fill any vacancies up to the set number of directors. If the shareholders do not elect or appoint the directors to fill any vacancies, then the directors may appoint directors to fill such vacancies.
A director is not required to hold shares as qualification for his or her office.
The directors are entitled to the remuneration for acting as directors, if any, as the directors may from time to time determine. PubCo must reimburse each director for the reasonable expenses that he or she may incur in and about the business of PubCo.
The directors shall be divided into three classes:
1. Class I. Class I directors shall initially serve for a term expiring the first annual general meeting following the effectiveness of the PubCo Closing Articles
2. Class II. Class II directors shall initially serve for a term expiring at the second annual general meeting following the effectiveness of the PubCo Closing Articles
3. Class III. Class III directors shall initially serve for a term expiring at the third annual general meeting following the effectiveness of the PubCo Closing Articles
202
Election and Removal of Directors
At every annual general meeting, the shareholders entitled to vote at the annual general meeting must elect the number of directors.
If PubCo fails to hold an annual general meeting or the shareholder fails to elect or appoint any directors, then each director then in office continues to hold office until the earlier of when his or her successor is elected or appointed and when he or she otherwise ceases to hold office.
Any casual vacancy in the board of directors may be filled by the directors.
Between annual general meetings, the directors may appoint one or more additional directors, but the number of additional directors appointed must not at any time exceed one-third of the number of first directors, if, at the time of the appointments, one or more of the first directors have not yet completed their first term of office; or in any other case, one-third of the number of the current directors who were elected or appointed as directors. Any director so appointed ceases to hold office immediately before the next election or appointment of directors, but is eligible for re-election or re-appointment.
PubCo may remove any director before the expiration of his or her term of office by special resolution. In that event, the shareholders may elect, or appoint by ordinary resolution, a director to fill the resulting vacancy. If the shareholders do not elect or appoint a director to fill the resulting vacancy contemporaneously with the removal, then the directors may appoint or the shareholders may elect, or appoint by ordinary resolution, a director to fill that vacancy.
The directors may remove any director before the expiration of his or her term of office if the director is convicted of an indictable offence, or if the director ceases to be qualified to act as a director of a company and does not promptly resign, and the directors may appoint a director to fill the resulting vacancy.
Powers and Duties of Directors
The directors must manage or supervise the management of the business and affairs of PubCo. The directors may by power of attorney appoint any person to be the attorney of PubCo.
Interests of Directors and Officers
A director who holds a disclosable interest in a contract or transaction into which the Company has entered or proposes to enter is not entitled to vote on any directors’ resolution to approve that contract or transaction, unless all the directors have a disclosable interest in that contract or transaction, in which case any or all of those directors may vote on such resolution.
A director who holds a disclosable interest in a contract or transaction into which the Company has entered or proposes to enter and who is present at the meeting of directors at which the contract or transaction is considered for approval may be counted in the quorum at the meeting.
A director or senior officer must disclose the nature and extent of any conflicts of interest it has or could have with its duty or interest as a director or senior officer.
A director or officer may act in any professional capacity for PubCo, except as auditor of PubCo.
Proceedings of Directors
The directors may meet together as they think fit, and meetings of the directors held at regular intervals may be held at the place, time and on the notice, if any, as the directors may from time to time determine. A director may participate in a meeting of directors in person or by telephone or electronic means.
Questions arising at any meeting of directors are to be decided by a majority of votes and, in the case of an equality of votes, the chair of the meeting has a second or casting vote.
203
The chair at a meeting of directors can be the chair of the board, if any; in the absence of the chair of the board, the president, if any, if the president is a director; or any other director chosen by the directors if the chair of the board and the president (i) are not present at the meeting within 15 minutes after the time set for holding the meeting, (ii) are not willing to chair the meeting, or (iii) have advised any other director that they will not be present at the meeting.
The quorum necessary for the transaction of the business of the directors may be set by the directors to a number not less than a majority of the directors in office, and, if not so set, is deemed to be a majority of the directors in office, or, if the number of directors is set at one, is deemed to be set at one director, and that director may constitute a meeting.
A resolution of the directors may be passed without a meeting if each director entitled to vote on the resolutions consents to it in writing. In the case of a resolution to approve a contract or transaction in respect of which a director has disclosed that he or she has or may have a disclosable interest, such resolution may be passed if each of the other directors who have not made such a disclosure consents in writing to the resolution.
Executive and Other Committees
The directors may, by resolution, appoint an executive committee consisting of director(s), such member(s) of the committee having all of the directors’ powers, except the power to fill vacancies on the board of directors, the power to remove a director, the power to change the membership of any committee of the directors and such other powers as may be set out in the resolution or any subsequent directors’ resolution.
The directors may, by resolution appoint any other committee(s) consisting of director(s) and delegate to such committee any of the directors’ powers, except the power to fill vacancies on the board of directors, the power to remove a director, the power to change the membership of any committee of the directors and such other powers as may be set out in the resolution or any subsequent directors’ resolution.
Officers
The directors may from time to time appoint and terminate the appointment of any officers. For each officer, the directors may determine the duties of the officer, confer on the officer any powers exercisable by the directors and revoke, withdraw, alter or vary any of the duties or powers of the officer. One person may hold more than one position as an officer of the Company. Any person appointed as the chair of the board or as a managing director must be a director. Any other officer need not be a director.
Indemnification
PubCo must indemnify each eligible party and legal personal representatives of each eligible party against all eligible penalties to which such person is or may be liable. An “eligible party” means an individual who is or was a director or officer of PubCo; is or was a director or officer of another corporation at a time when the corporation is or was an affiliate of PubCo or at the request of PubCo; or at the request of PubCo, is or was, or holds or held a position equivalent to that of, a director or officer of a partnership, trust, joint venture or other unincorporated entity. PubCo may agree to indemnify any person against eligible penalties in connection with the performance of services by that person for PubCo.
Dividends
Directors of PubCo may declare dividends and authorize payment of such dividends as they deem advisable. Dividends may be paid wholly or partly in money or by the distribution of specific assets or of fully paid shares or of bonds, debentures or other securities of PubCo or any other corporation. All dividends must be declared and paid according to the number of shares held. Fractional dividends may be disregarded in making payment of a dividend.
Accounting Records and Auditor
No shareholder of PubCo is entitled to inspect or obtain a copy of any accounting records of the Company.
204
Notices
Any notice to be sent by the PubCo to a person may be sent by mail, by fax, by email, by physical delivery to the intended recipient, or as otherwise permitted by any securities legislation in Canada or the United States. A notice that is mailed by ordinary mail is deemed to be received on the day (Saturdays, Sundays and holidays excepted) following the date of mailing. A notice that is faxed or emailed to a person is deemed to be received on the day it was faxed or emailed, respectively. A certificate signed by the secretary or other officer of PubCo, or any other corporation acting in such capacity stating that a notice was sent is conclusive evidence of that fact. If on two consecutive occasions, PubCo receives a returned notice, statement or report because the shareholder cannot be located, PubCo will not be required to send any further records to the shareholder until the shareholder informs PubCo in writing of their new address.
Seal
PubCo’s seal must be attested by the signatures of any two directors, any officer together with any director, any sole director, or any one or more directors or officers or persons as may be determined by the directors. Notwithstanding the foregoing, for the purpose of certifying under seal a certificate of incumbency of the directors or officers of PubCo, the seal may be attested by the signature of any director or officer or the signature of any other person as may be determined by the directors.
Prohibitions
No share or designated security may be sold, transferred or otherwise disposed of without the consent of the directors, such consent which may be withheld without any reason.
205
REGULATORY APPROVALS RELATED TO THE BUSINESS COMBINATION
The transactions contemplated by the Business Combination Agreement, including the Business Combination, are not presently believed to be subject to any federal or state regulatory requirement or approval.
Court Approval
The Arrangement requires approval by the Court under Section 291 of the BCBCA. TRC received the Interim Order on [•], 2025, providing for the calling, holding and conducting of the Plum Meeting and the TRC Meeting and other procedural matters and a Notice of Application for the Final Order to approve the Arrangement was filed. A copy of the Interim Order and the Notice of Application for the Final Order was attached as Annex N — “Interim Order”.
The Court hearing in respect of the Final Order is expected to take place at [•] a.m. (Pacific Standard Time), on [•], or as soon thereafter as counsel for TRC may be heard, at the Supreme Court of British Columbia, located at 800 Smith Street, Vancouver, British Columbia, Canada, V6Z 2E1. At the hearing, the Court will consider, among other things, the fairness of the terms and conditions of the Arrangement and the rights and interests of every person affected. TRC has been advised by its legal counsel that the Court has broad discretion under the BCBCA when making orders with respect to a plan of arrangement and that the Court will consider, among other things, the fairness and reasonableness of the Arrangement, both from a substantive and procedural point of view. The Court may approve the Arrangement in any manner the Court may direct, subject to compliance with such terms and conditions, if any, as the Court deems fit. Depending on the nature of any required amendments, TRC or Plum may determine not to proceed with the Arrangement.
Under the terms of the Interim Order, each Plum Shareholder will have the right to appear and make submissions at the application for the Final Order. Any person desiring to appear at the hearing of the application for the Final Order may do so but must comply with certain procedural requirements described in the Interim Order, including filing with the Court registry a Response to Petition, in the form prescribed by the British Columbia Supreme Court Civil Rules, and an Affidavit containing supporting evidence, including exhibits, if any, and serving same on TRC’s counsel, as applicable, at the address set out below, no later than [•] p.m. (Pacific Standard Time) on [•]:
McMillan LLP
1500-1055 West Georgia Street
Vancouver, BC V6E 4N7
Attention: Arman Farahani, Partner
Email: arman.farahani@mcmillan.ca
Tel: 604.691.7430
Plum Shareholders who wish to participate in or be represented at the Court hearing for the Final Order should consult their legal advisors as to the necessary requirements.
Competition and Antitrust
General
At any time before or after the consummation of the Business Combination, the U.S. Federal Trade Commission (the “FTC”), the Antitrust Division of the U.S. Department of Justice (the “Antitrust Division”), non-U.S. competition authorities or others, including under the Competition Act, could take action under antitrust laws with respect to the Business Combination, including seeking to enjoin consummation of the Business Combination, or to condition approval of the Business Combination on the divestiture of assets of Plum, TRC or their respective subsidiaries or to impose restrictions on the operations of PubCo or its subsidiaries that would apply after the consummation of the Business Combination. Private parties may also bring objections or legal actions under antitrust laws under certain circumstances.
The Business Combination may be challenged on antitrust grounds and, if such a challenge is made, that the challenge may be successful. Similarly, the antitrust approvals necessary to consummate the Business Combination and the other transactions contemplated by the Business Combination Agreement may not be obtained and the
206
granting of these approvals may involve the imposition of conditions to such consummation. These conditions or changes could result in the conditions to each party’s obligations to consummate the Business Combination not being satisfied prior to the Business Combination end date (which is summarized in the subsection entitled “The Business Combination — Termination” elsewhere in this proxy statement/prospectus) or any extensions thereof, which would give any party to the Business Combination Agreement the right to terminate the Business Combination Agreement without consummating the Business Combination.
Please see the subsections entitled “The Business Combination — Covenants of the Parties,” elsewhere in this proxy statement/prospectus, and “The Business Combination — Conditions to Closing of the Business Combination — Conditions to the Obligations of Each Party” elsewhere in this proxy statement/prospectus for information concerning Plum’s and TRC’s covenants and closing conditions related to antitrust filings and approvals.
United States/Canada Antitrust Clearance
The transactions contemplated by the Business Combination Agreement, including the Business Combination, are not presently believed to be subject to reporting under the HSR Act or the Competition Act, which prevents transactions meeting certain size and nexus tests, and which are not otherwise exempt, from being completed until required information and materials are furnished to the Antitrust Division and the FTC or the Canadian Competition Bureau (the “Competition Bureau”), respectively and the related waiting period expires or is terminated early.
Whether or not the parties are subject to the notice and waiting period requirements of the HSR Act, and if so, even if the waiting period has been terminated or expired, the Antitrust Division or the FTC, as well as a foreign regulatory agency or government (including the Competition Bureau), state or private person, may challenge the transactions at any time before or after its completion. The Antitrust Division or the FTC may try to prevent the transactions or seek to impose restrictions or conditions on one or more of the parties as a condition of not challenging the transactions. Depending on the nature of any restrictions or conditions, these restrictions or conditions may jeopardize or delay completion of the transactions, or lessen the anticipated benefits of the transactions. In addition, in certain circumstances under the Competition Act, the Commissioner of Competition (the “Commissioner”) has up to one year to challenge the transaction following its completion.
Stock Exchange Listings
Plum and TRC anticipate that, following consummation of the Business Combination, Plum Class A Shares, Plum Units and Plum Warrants will be no longer qualified on the OTC Pink, and Plum will be deregistered under the Exchange Act. PubCo Common Shares and PubCo Warrants currently are not traded on a stock exchange. PubCo has applied to have the PubCo Common Shares and PubCo Public Warrants listed on the NASDAQ. Listing is subject to the approval of NASDAQ in accordance with its original listing requirements. There is no assurance that NASDAQ will approve PubCo’s listing application. Any such listing of the PubCo Common Shares and PubCo Warrants will be conditional upon PubCo fulfilling all of the listing requirements and conditions of NASDAQ. It is anticipated that upon the Closing the PubCo Common Shares and PubCo Warrants will be listed on the NASDAQ under the ticker symbols “TREO” and “TREOW,” respectively. Following the Closing, it is anticipated that the TRC Common Shares will be delisted from the TSX-V, and TRC will apply to have TRC cease to be a reporting issuer in the jurisdictions in which it is currently a reporting issuer.
207
UNAUDITED PRO FORMA CONDENSED CONSOLIDATED FINANCIAL INFORMATION
The following unaudited pro forma condensed combined balance sheet of PubCo as of January 31, 2025 and the unaudited pro forma condensed combined statement of operations of PubCo for the six months ended January 31, 2025 and the year ended July 31, 2024 present the combination of the financial information of PubCo, Plum and TRC after giving effect to the Business Combination and related adjustments described in the accompanying notes. PubCo, Plum and TRC are collectively referred to herein as the “Companies,” and the Companies, subsequent to the Business Combination, are referred to herein as “PubCo.”
The unaudited pro forma condensed combined statement of operations for the six months ended January 31, 2025 and the year ended July 31, 2024 give pro forma effect to the Business Combination as if it had occurred on August 1, 2023. The unaudited pro forma condensed combined statement of operations for the six months ended January 31, 2025 is derived from the following: The unaudited pro forma quarterly statement of operations, as of January 31, 2025, of Plum was derived from its December 31, 2024 financial statements, which are included elsewhere in this proxy statement/prospectus. The unaudited pro forma quarterly statement of operations of TRC as of January 31, 2025 is from its January 31, 2025 financial statements, which are included elsewhere in this proxy statement/prospectus. The unaudited pro forma condensed combined statement of operations for the year ended July 31, 2024 is derived from the following: The unaudited pro forma annual statement of operations, as of July 31, 2024, of Plum was derived from its June 30, 2024 financial statements, which are not included elsewhere in this proxy statement/prospectus, added to its December 31, 2023 financial statements, which are included elsewhere in this proxy statement/prospectus, minus its June 30, 2023 financial statements, which are not included elsewhere in this proxy statement/prospectus. The annual statement of operations of TRC as of July 31, 2024 is from its July 31, 2024 financial statements, which are included elsewhere in this proxy statement/prospectus. The unaudited annual statement of operations of PubCo as of July 31, 2024 predates its inception and are derived from its December 31, 2024 financial statements, which are included elsewhere in this proxy statement/prospectus. Since no definitive documentation has been executed in connection with the PIPE Investment, the PIPE Investment is not yet probable, and thus the effects of the PIPE Investment are not included in the pro forma financial statements.
The unaudited pro forma condensed combined financial information is based on and should be read in conjunction with the audited historical financial statements of each of PubCo, Plum and TRC and the notes thereto, as well as the disclosures contained in the sections titled “Plum’s Management’s Discussion and Analysis of Financial Condition and Results of Operations” and “TRC’s Management’s Discussion and Analysis of Financial Condition and Results of Operations,” contained elsewhere in this proxy statement/prospectus.
The unaudited pro forma condensed combined financial information has been presented for illustrative purposes only and does not necessarily reflect what PubCo’s financial condition or results of operations would have been had the Business Combination occurred on the dates indicated. Further, the unaudited pro forma condensed combined financial information also may not be useful in predicting the future financial condition and results of operations of PubCo. The actual financial position and results of operations may differ significantly from the pro forma amounts reflected herein due to a variety of factors. The unaudited pro forma adjustments represent management’s estimates based on information available as of the date of this proxy statement/prospectus and are subject to change as additional information becomes available and analyses are performed.
On August 22, 2024, Plum, Amalco, PubCo, and TRC entered into the Business Combination Agreement pursuant to which (i) Plum shall transfer by way of continuation from the Cayman Islands to the Province of British Columbia and continue as a corporation under the BCBCA (the “Domestication”), (ii) following the Domestication, Plum shall amalgamate with PubCo (the “Plum Amalgamation”) to form one corporate entity and PubCo will survive the Plum Amalgamation, and (iii) immediately following the Plum Amalgamation, TRC and Amalco shall amalgamate (the “TRC Amalgamation” and, together with the Plum Amalgamation, the “Amalgamations”) to form one corporate entity and TRC will survive the TRC Amalgamation.
Pursuant to the Plum Amalgamation: (a) each Plum Unit shall be automatically divided, and the holder thereof shall be deemed to hold one Plum Class A Share and one-third of one Plum Warrant; (b) each Plum Common Shares will be exchanged on a one-for-one basis, for a PubCo Common Share; and (c) each Plum Warrant shall automatically be converted into a PubCo Assumed Plum Warrant to purchase PubCo Common Shares.
Pursuant to the TRC Amalgamation: (a) each TRC Common Share (other than Dissenting Shares) shall automatically be exchanged for the right to receive a number of PubCo Common Shares equal to the TRC Exchange Ratio; (b) each of the Dissenting Shares shall be cancelled and shall thereafter represent only the right to receive
208
the applicable payments set forth in the Plan of Arrangement; (c) each TRC Option shall be assumed by PubCo and converted into an option to purchase PubCo Common Shares; (d) each TRC RSU shall be assumed by PubCo and converted into Converted TRC RSU; (e) each TRC Warrant shall automatically be converted into a PubCo Assumed TRC Warrant; (f) the TRC Convertible Debenture shall survive the TRC Amalgamation in accordance with the terms thereof; and (g) each Amalco Share shall automatically be exchanged for one validly-issued, fully paid and nonassessable common share of TRC.
The unaudited pro forma condensed combined information contained herein assumes that the Plum’s shareholders approve the Business Combination. Plum’s public shareholders may elect to redeem their public shares for cash even if they approve the Business Combination. Plum cannot predict how many of its public shareholders will exercise their right to have their Class A Shares redeemed for cash. As a result, Plum has elected to provide the unaudited pro forma condensed combined financial information under two different redemption scenarios, which produce different allocations of total PubCo equity between holders of the ordinary shares. As described in greater detail in Note 1, Basis of Pro Forma Presentation, of the unaudited pro forma condensed combined financial statements, the first scenario, or “no redemption scenario,” assumes that none of Plum’s public shareholders will exercise their right to have their Plum public shares redeemed for cash, and the second scenario, or “maximum redemption scenario,” assumes that holders of the maximum number of public shares that could be redeemed. The actual results will be within the parameters described by the two scenarios. However, there can be no assurances regarding which scenario will be closest to the actual results. Under both scenarios, TRC is considered the accounting acquirer, as further discussed in Note 1, Basis of Pro Forma Presentation, of the unaudited pro forma condensed combined financial statements.
The number of PubCo Common Shares to be issued to TRC security holders will be based upon the TRC Exchange Ratio, determined by dividing (a) the Price per TRC Share by (b) $10.00. The Price per TRC Share is determined by dividing (a) the Arrangement Consideration by (b) the Fully-Diluted TRC Shares. Arrangement Consideration means the sum of (a) $500,000,000, plus (b) the Aggregate Exercise Price, plus (c) the gross proceeds received by TRC in connection with any Permitted Financing. Aggregate Exercise Price means the aggregate dollar amount payable to TRC upon (a) the conversion of the TRC Convertible Debenture in accordance with its terms and (b) the exercise of all vested In-the-Money TRC Options and vested In-the-Money TRC Warrants that are outstanding immediately prior to the TRC Amalgamation Effective Time. Fully-Diluted TRC Shares means, without duplication, the total number of issued and outstanding TRC Common Shares as of immediately prior to the TRC Amalgamation Effective Time, determined on a fully-diluted basis as the sum of (a) the number of TRC Common Shares outstanding immediately prior to the TRC Amalgamation Effective Time and (b) the number of TRC Common Shares issuable (i) in respect of all issued and outstanding TRC RSUs, (ii) upon exercise of all vested In-the-Money TRC Options, (iii) upon exercise of all vested In-the-Money TRC Warrants and (iv) upon conversion of the TRC Convertible Debenture (including the number of TRC Common Shares issuable in respect of all vested In-the-Money TRC Warrants issuable upon the conversion thereof), in each case, in accordance with the terms thereof; provided, that, for the avoidance of doubt, Fully-Diluted TRC Shares shall not include any TRC Common Shares issuable upon exercise of any unvested In-the-Money TRC Options, unvested In-the-Money TRC Warrants, Out-of-the-Money TRC Options or Out-of-the-Money TRC Warrants. The TRC Exchange Ratio of 0.87084460 set forth in this proxy statement/prospectus was calculated based upon an Aggregate Exercise Price of $5,888,590, assumed Permitted Financings of $0.00, and Fully-Diluted TRC Shares of 58,091,718.
The historical financial information of Plum and TRC has been adjusted in the unaudited pro forma condensed combined financial information to give effect to events that are (1) directly attributable to the Business Combination and (2) factually supportable. The pro forma adjustments are prepared to illustrate the estimated effect of the Business Combination and certain other adjustments.
The Business Combination will be accounted for as a reverse recapitalization because TRC has been determined to be the accounting acquirer under Financial Accounting Standards Board’s Accounting Standards Codification Topic 805, Business Combinations (“ASC 805”) under both the no redemption and maximum redemption scenarios. The determination is primarily based on the evaluation of the following facts and circumstances taking into consideration both the no redemption and maximum redemption scenario:
• the pre-combination equityholders of TRC will hold the majority of voting rights in PubCo;
• the pre-combination equityholders of TRC will have the right to appoint the majority of the directors on the PubCo Board;
209
• the senior management of TRC will comprise the senior management of PubCo; and
• the operations of TRC will comprise the ongoing operations of PubCo.
Under the reverse recapitalization model, the Business Combination will be treated as TRC issuing equity for the net assets of Plum, with no goodwill or intangible assets recorded.
The unaudited pro forma condensed combined financial information has been prepared using the assumptions below with respect to the potential redemption of Plum’s Class A Shares into cash:
• Assuming No Redemptions: This presentation assumes that no Plum shareholders exercise redemption rights with respect to their public shares.
• Assuming Maximum Redemptions: This presentation assumes that all of Plum’s public shareholders exercise redemption rights with respect to their Class A Shares. This scenario assumes that 151,833 Class A Shares are redeemed for an aggregate redemption payment of approximately $1,711,089.
If the actual facts are different than these assumptions, then the amounts and shares outstanding in the unaudited pro forma condensed combined financial information will be different.
The unaudited pro forma condensed combined financial information does not reflect the income tax effects of the pro forma adjustments as any change in the deferred tax balance would be offset by an increase in the valuation allowance given that TRC incurred significant losses during the historical periods presented.
The following summarizes the pro forma PubCo Common Shares outstanding under the no redemption and maximum redemption scenarios:
|
Assuming |
Assuming |
|||||||||
|
Shares |
% |
Shares |
% |
|||||||
|
Plum Public Shareholders(1) |
1,016,833 |
2.3 |
% |
865,000 |
2.0 |
% |
||||
|
Plum Initial Shareholders(2) |
7,062,500 |
15.9 |
% |
7,062,500 |
16.0 |
% |
||||
|
Total Plum |
8,079,333 |
18.2 |
% |
7,927,500 |
18.0 |
% |
||||
|
|
|
|||||||||
|
TRC Shareholders(3) |
35,073,456 |
79.1 |
% |
35,073,456 |
79.3 |
% |
||||
|
Share Awards issued to Investment Bankers(4) |
1,188,950 |
2.7 |
% |
1,188,950 |
2.7 |
% |
||||
|
Total Shares at Closing |
44,341,739 |
100.0 |
% |
44,189,906 |
100.0 |
% |
||||
____________
(1) Under the No Redemptions scenario, 1,016,833 is comprised of 151,833 shares held by current public shareholders and 865,000 shares held by Sponsor or Former Sponsor. Under the Max Redemptions scenario, the 865,000 is comprised only of 865,000 shares held by Sponsor or Former Sponsor, all of which are subject to lock-ups.
(2) Under both No Redemptions and Max Redemptions scenarios, 7,062,500 is comprised of 6,731,320 shares held by Sponsor or Former Sponsor, which are subject to lock-ups, and 331,180 shares by other parties subject to non-redemption agreements.
(3) Under both No Redemptions and Max Redemptions scenarios, 35,073,456 is comprised of the product of: the summation of 35,674,480 shares held by existing TRC public shareholders and 4,600,738 shares issued to settle TRC consultant compensation; and the TRC Exchange Ratio of 0.87084460.
(4) Under both No Redemptions and Max Redemptions scenarios, 1,188,950 is comprised of the summation of fees settled in shares to Jett Capital and Cohen & Company, of 638,950 shares and 550,000 shares, respectively.
The following unaudited pro forma condensed combined balance sheet as of January 31, 2025 and the unaudited pro forma condensed combined statements of operations for the six months ended January 31, 2025 and year ended July 31, 2024 are based on the historical financial statements of Plum and TRC. The unaudited pro forma adjustments are based on information currently available, and assumptions and estimates underlying the unaudited pro forma adjustments are described in the accompanying notes. Actual results may differ materially from the assumptions used to present the accompanying unaudited pro forma condensed combined financial information.
210
PRO FORMA CONDENSED CONSOLIDATED BALANCE SHEET AS OF JANUARY 31, 2025
|
As at |
Tactical |
Plum |
Plum III |
Pro forma |
Pro forma |
Pro forma |
Pro forma |
||||||||||||||||||
|
January 31 |
December 31 |
December 31 |
|
Note(s) |
(Consolidated) |
|
Note(s) |
(Consolidated) |
|||||||||||||||||
|
$ |
$ |
$ |
$ |
$ |
$ |
$ |
|||||||||||||||||||
|
ASSETS |
|
|
|
|
|
|
|
||||||||||||||||||
|
Current assets |
|
|
|
|
|
|
|
||||||||||||||||||
|
Cash and cash equivalents |
299,114 |
|
27,418 |
|
— |
|
1,711,089 |
|
A |
2,287,621 |
|
(1,711,089 |
) |
B |
576,532 |
|
|||||||||
|
|
|
|
350,000 |
|
5 |
|
|
|
|||||||||||||||||
|
|
|
|
(100,000 |
) |
6 |
|
|
|
|||||||||||||||||
|
Accounts receivable |
28,880 |
|
23,280 |
|
— |
|
|
52,160 |
|
|
52,160 |
|
|||||||||||||
|
Prepaid expenses |
31,211 |
|
36,706 |
|
— |
|
700,000 |
|
2 |
767,917 |
|
|
|
767,917 |
|
||||||||||
|
359,205 |
|
87,404 |
|
— |
|
2,661,089 |
|
3,107,698 |
|
(1,711,089 |
) |
1,396,609 |
|
||||||||||||
|
Non-current assets |
|
|
|
|
|
|
|
||||||||||||||||||
|
Investments held in Trust Account |
— |
|
25,630,285 |
|
— |
|
(23,975,464 |
) |
3 |
— |
|
|
— |
|
|||||||||||
|
|
|
|
56,268 |
|
4 |
|
|
|
|||||||||||||||||
|
|
|
|
(1,711,089 |
) |
A |
|
|
|
|||||||||||||||||
|
Deferred acquisition costs |
144,977 |
|
— |
|
— |
|
|
|
144,977 |
|
|
|
144,977 |
|
|||||||||||
|
144,977 |
|
25,630,285 |
|
— |
|
(25,630,285 |
) |
144,977 |
|
— |
|
144,977 |
|
||||||||||||
|
TOTAL ASSETS |
504,182 |
|
25,717,689 |
|
— |
|
(22,969,196 |
) |
3,252,675 |
|
(1,711,089 |
) |
1,541,586 |
|
|||||||||||
|
LIABILITIES |
|
|
|
|
|
|
|
||||||||||||||||||
|
Current liabilities |
|
|
|
|
|
|
|
||||||||||||||||||
|
Accounts payable and accrued liabilities |
4,040,325 |
|
1,946,965 |
|
42,027 |
|
8,075,206 |
|
2 |
14,104,523 |
|
|
14,104,523 |
|
|||||||||||
|
Promissory note |
— |
|
1,204,867 |
|
— |
|
350,000 |
|
5 |
— |
|
|
— |
|
|||||||||||
|
|
|
|
|
|
|
(1,554,867 |
) |
6 |
|
|
|
|
|
|
|||||||||||
|
4,040,325 |
|
3,151,832 |
|
42,027 |
|
6,870,339 |
|
14,104,523 |
|
— |
|
14,104,523 |
|
||||||||||||
|
Long term liabilities |
|
|
|
|
|
|
|
||||||||||||||||||
|
Warrant liabilities |
— |
|
2,170,651 |
|
— |
|
|
2,170,651 |
|
|
2,170,651 |
|
|||||||||||||
|
Convertible notes |
424,299 |
|
— |
|
— |
|
|
|
424,299 |
|
|
|
424,299 |
|
|||||||||||
|
424,299 |
|
2,170,651 |
|
— |
|
— |
|
2,594,950 |
|
— |
|
2,594,950 |
|
||||||||||||
|
TOTAL LIABILITIES |
4,464,624 |
|
5,322,483 |
|
42,027 |
|
6,870,339 |
|
16,699,473 |
|
— |
|
16,699,473 |
|
|||||||||||
|
COMMITMENTS |
— |
|
25,630,285 |
|
— |
|
(23,975,464 |
) |
3 |
— |
|
|
— |
|
|||||||||||
|
|
|
|
56,268 |
|
4 |
|
|
|
|||||||||||||||||
|
|
|
|
(1,711,089 |
) |
A |
|
|
|
|||||||||||||||||
|
EQUITY |
|
|
|
|
|
|
|
||||||||||||||||||
|
Share capital |
5,991,568 |
|
793 |
|
— |
|
(5,277,899 |
) |
1 |
4,635,278 |
|
(1,711,089 |
) |
B |
2,924,189 |
|
|||||||||
|
|
|
|
1,381,595 |
|
2 |
|
|
|
|||||||||||||||||
|
|
|
|
828,132 |
|
7 |
|
|
|
|||||||||||||||||
|
|
|
|
1,711,089 |
|
A |
|
|
|
|||||||||||||||||
|
Obligation to issue shares |
828,132 |
|
— |
|
— |
|
(828,132 |
) |
7 |
— |
|
|
— |
|
|||||||||||
|
Additional paid-in capital |
1,527,685 |
|
— |
|
— |
|
1,454,867 |
|
6 |
2,982,552 |
|
|
2,982,552 |
|
|||||||||||
|
Accumulated deficit |
(12,181,217 |
) |
(5,235,872 |
) |
(42,027 |
) |
5,277,899 |
|
1 |
(20,938,018 |
) |
|
(20,938,018 |
) |
|||||||||||
|
|
|
|
(8,756,801 |
) |
2 |
|
|
|
|||||||||||||||||
|
Accumulated other comprehensive income (loss) |
(126,610 |
) |
— |
|
— |
|
|
(126,610 |
) |
|
(126,610 |
) |
|||||||||||||
|
TOTAL EQUITY |
(3,960,442 |
) |
(5,235,079 |
) |
(42,027 |
) |
(4,209,250 |
) |
(13,446,798 |
) |
(1,711,089 |
) |
(15,157,887 |
) |
|||||||||||
|
TOTAL EQUITY AND LIABILITIES |
504,182 |
|
25,717,689 |
|
— |
|
(22,969,196 |
) |
3,252,675 |
|
(1,711,089 |
) |
1,541,586 |
|
|||||||||||
211
PRO FORMA CONDENSED CONSOLIDATED INCOME STATEMENT
FOR THE SIX MONTHS ENDED JANUARY 31, 2025
|
Tactical |
Plum |
Plum III |
Pro forma |
Pro forma |
||||||||||||||||
|
For the |
For the |
For the |
|
Note(s) |
(Consolidated) – |
|||||||||||||||
|
$ |
$ |
$ |
$ |
$ |
||||||||||||||||
|
EXPENSES |
|
|
|
|
|
|
|
|
||||||||||||
|
Consulting fees |
|
326,689 |
|
|
— |
|
|
— |
|
|
326,689 |
|
||||||||
|
Depreciation |
|
357 |
|
|
— |
|
|
— |
|
|
357 |
|
||||||||
|
Foreign exchange loss (gain) |
|
3,284 |
|
|
— |
|
|
— |
|
|
3,284 |
|
||||||||
|
General and administrative expenses |
|
33,350 |
|
|
2,027,498 |
|
|
42,027 |
|
|
2,102,875 |
|
||||||||
|
Investor relations |
|
13,254 |
|
|
— |
|
|
— |
|
|
13,254 |
|
||||||||
|
Professional fees |
|
84,626 |
|
|
— |
|
|
— |
|
|
84,626 |
|
||||||||
|
Property investigation costs |
|
41,791 |
|
|
— |
|
|
— |
|
|
41,791 |
|
||||||||
|
Stock-based compensation |
|
1,035,356 |
|
|
— |
|
|
— |
|
|
1,035,356 |
|
||||||||
|
Transfer agent, regulatory and listing fees |
|
8,058 |
|
|
— |
|
|
— |
|
|
|
8,058 |
|
|||||||
|
|
1,546,765 |
|
|
2,027,498 |
|
|
42,027 |
|
— |
|
3,616,290 |
|
||||||||
|
OTHER EXPENSES (INCOME) |
|
|
|
|
|
|
|
|
||||||||||||
|
Accretion of interest |
|
36,469 |
|
|
— |
|
|
— |
|
|
36,469 |
|
||||||||
|
Interest and dividend income on investments held in Trust Account |
|
— |
|
|
(533,955 |
) |
|
— |
|
533,955 |
4 |
|
— |
|
||||||
|
Loss (gain) on change in fair value of warrant |
|
— |
|
|
1,326,509 |
|
|
— |
|
|
1,326,509 |
|
||||||||
|
Transaction costs |
|
1,982,786 |
|
|
— |
|
|
— |
|
|
|
1,982,786 |
|
|||||||
|
|
2,019,255 |
|
|
792,554 |
|
|
— |
|
533,955 |
|
3,345,764 |
|
||||||||
|
NET LOSS (INCOME) |
|
3,566,020 |
|
|
2,820,052 |
|
|
42,027 |
|
533,955 |
|
6,962,054 |
|
|||||||
|
OTHER COMPREHENSIVE LOSS (INCOME) |
|
|
|
|
|
|
|
|
||||||||||||
|
Foreign currency translation differences for foreign operations |
|
(168,151 |
) |
|
— |
|
|
— |
|
|
|
(168,151 |
) |
|||||||
|
|
(168,151 |
) |
|
— |
|
|
— |
|
— |
|
(168,151 |
) |
||||||||
|
LOSS AND COMPREHENSIVE LOSS |
|
3,397,869 |
|
|
2,820,052 |
|
|
42,027 |
|
533,955 |
|
6,793,903 |
|
|||||||
|
Basic and diluted weighted average number of common shares outstanding |
|
35,674,480 |
|
|
|
|
|
|
|
|||||||||||
|
Basic and diluted net income (loss) per share |
$ |
(0.10 |
) |
|
|
|
|
|
|
|||||||||||
|
|
|
|
|
|
|
|
|
|||||||||||||
|
Basic and diluted weighted average shares outstanding, Class A ordinary shares |
|
|
|
3,149,199 |
|
|
|
|
|
|||||||||||
|
Basic and diluted net (loss) income per share, Class A ordinary shares |
|
|
$ |
(0.28 |
) |
|
|
|
|
|||||||||||
|
Basic and diluted weighted average shares outstanding, Class B ordinary shares |
|
|
|
7,062,500 |
|
|
|
|
|
|||||||||||
|
Basic and diluted net (loss) income per share, Class B ordinary shares |
|
|
$ |
(0.28 |
) |
|
|
|
|
|||||||||||
|
|
|
|
|
|
|
|
|
|||||||||||||
|
Basic and diluted weighted average number of common shares outstanding |
|
|
|
|
|
100 |
|
|
|
|||||||||||
|
Basic and diluted net income (loss) per share |
|
|
|
|
$ |
(420.27 |
) |
|
|
|||||||||||
|
|
|
|
|
|
|
|
|
|||||||||||||
|
Basic and diluted weighted average shares outstanding |
|
|
|
|
|
|
|
44,189,906 |
|
|||||||||||
|
Basic and diluted net income (loss) per share |
|
|
|
|
|
|
$ |
(0.15 |
) |
|||||||||||
212
PRO FORMA CONDENSED CONSOLIDATED INCOME STATEMENT
FOR THE YEAR ENDED JULY 31, 2024
|
Tactical |
Plum |
Plum III |
Pro forma |
Pro forma |
|||||||||||||||
|
For the |
For the |
For the |
|||||||||||||||||